Bessemer's State of the Cloud 2024, two years on
We graded ten calls from Bessemer Venture Partners' June 2024 report against public-market and private AI data to October 30, 2026
by Yijia Liang · November 12, 2026 · 8 min read

The full 17-slide deck behind this post: the scorecard, every rebuilt exhibit, and the sources and method, with data as of October 30, 2026.
Download · FreeOn June 20, 2024, Bessemer Venture Partners published State of the Cloud 2024 and called it “a eulogy for the legacy cloud.” Earlier editions were built on public cloud multiples. This one bet on AI at every layer of the stack: Big Tech-backed model giants, developers turned into code reviewers, voice agents, Vertical AI worth 10x legacy vertical software, and an AI revival of consumer cloud.
We had Compound rebuild the report’s exhibits with data to October 30, 2026 and grade its ten testable calls. Four were right, six are too early to call, and none is wrong yet. The public-market call landed, and the model layer grew faster than Bessemer expected. Most of the AI calls run to 2027 to 2030.
Four right, six too early
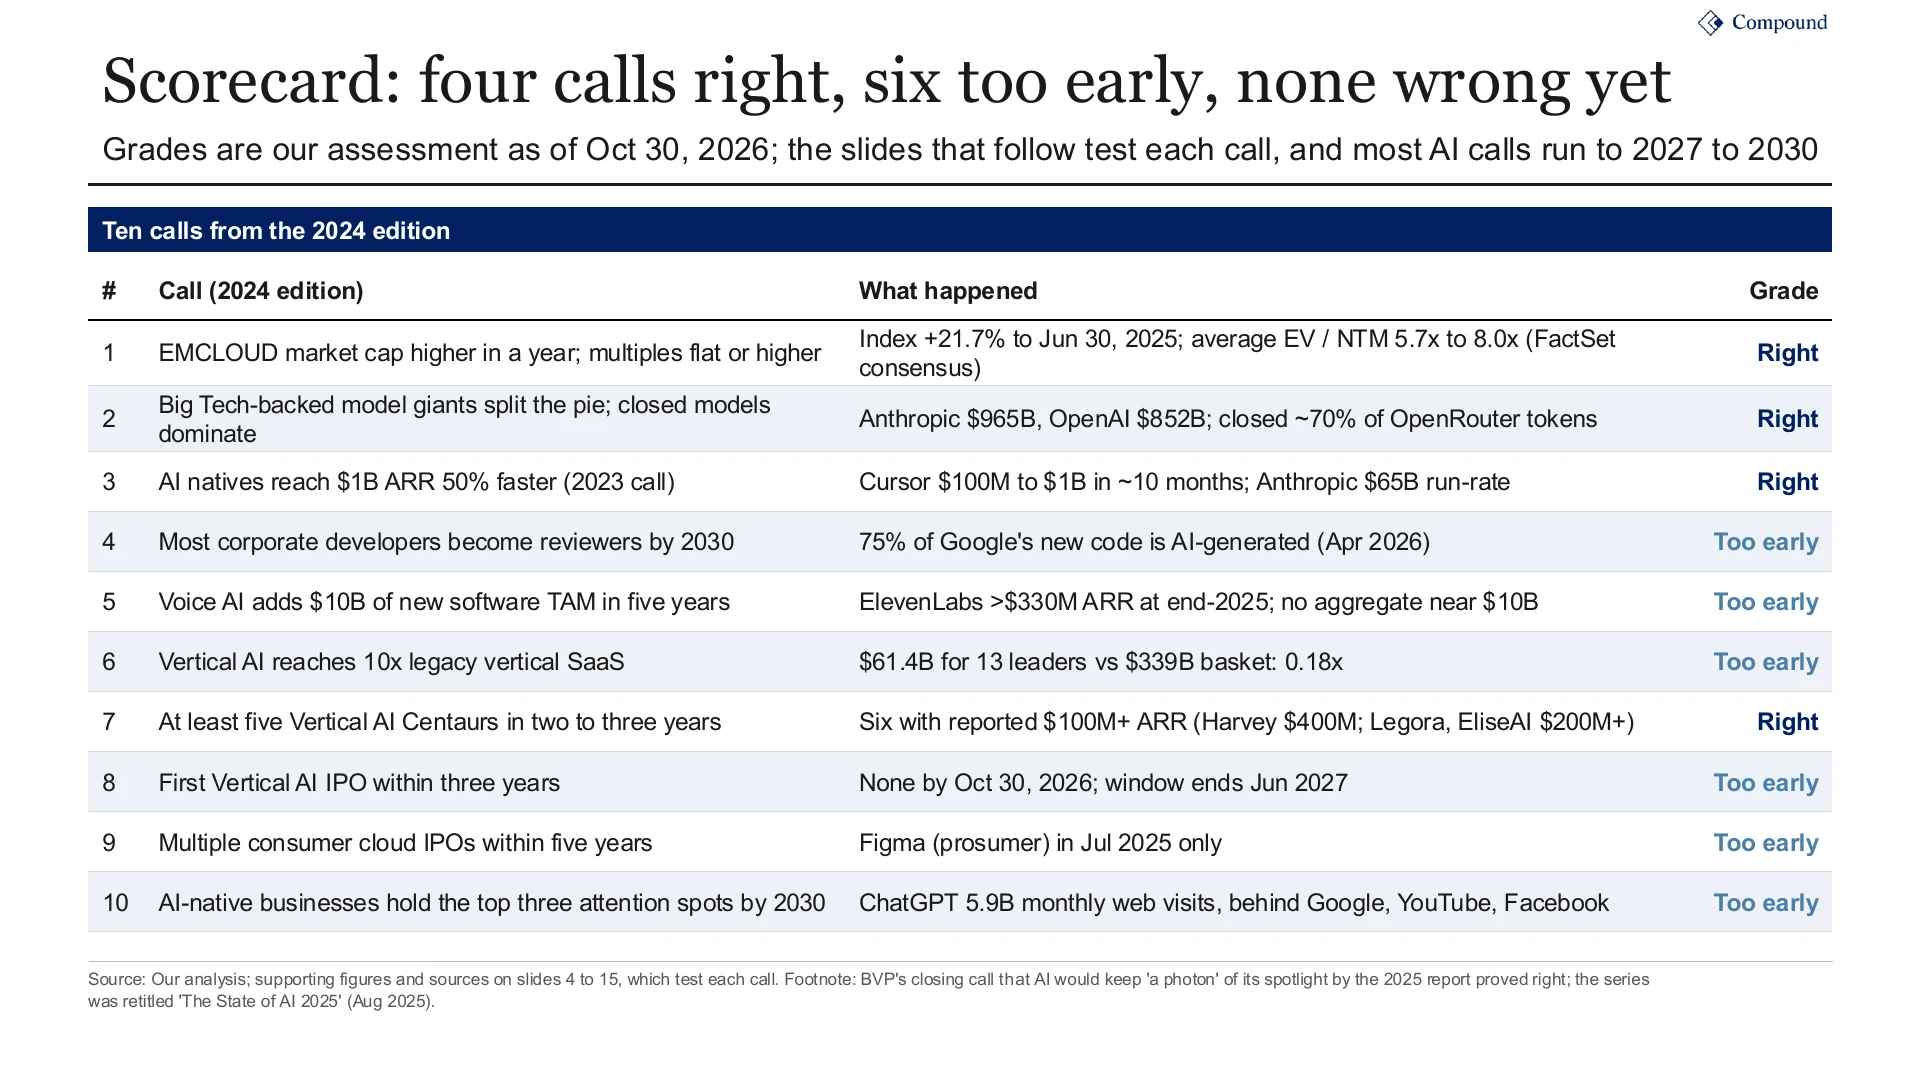
| Call | What happened by October 30, 2026 | Grade |
|---|---|---|
| EMCLOUD market cap higher in a year; multiples flat or higher | Index +21.7% to June 30, 2025; average EV/NTM revenue 5.7x to 8.0x | Right |
| Big Tech-backed model giants split the pie; closed models dominate | Anthropic valued at $965B, OpenAI at $852B; closed models ~70% of OpenRouter tokens | Right |
| AI natives reach $1B ARR 50% faster (from the 2023 edition) | Cursor went from $100M to $1B in about 10 months | Right |
| Most corporate developers become code reviewers by 2030 | 75% of Google’s new code is AI-generated (April 2026) | Too early |
| Voice AI adds $10B of new software TAM in five years | ElevenLabs above $330M ARR at end-2025; no aggregate near $10B | Too early |
| Vertical AI reaches 10x legacy vertical SaaS | $61.4B for 13 leaders vs $339B for a top-20 vertical SaaS basket: 0.18x | Too early |
| At least five Vertical AI Centaurs in two to three years | Six with reported $100M+ ARR | Right |
| First Vertical AI IPO within three years | None yet; the window closes June 2027 | Too early |
| Multiple consumer cloud IPOs within five years | Figma, a prosumer company, in July 2025 only | Too early |
| AI-native businesses hold the top three attention spots by 2030 | ChatGPT at 5.9B monthly web visits, behind Google, YouTube and Facebook | Too early |
Cloud multiples round-tripped
Bessemer said public cloud had returned to “historical norms”, with its index at about 5.9x forward revenue. On our rebuild of the BVP Nasdaq Emerging Cloud Index (EMCLOUD) from its constituents, the average was 5.7x on the report date. It rose to 8.1x in October 2025, fell in the spring 2026 software selloff, when the median touched 3.2x, and ended October 2026 at 7.2x average and 4.9x median. NVIDIA, the AI premium the report pointed to, compressed from 22.1x to 7.9x.
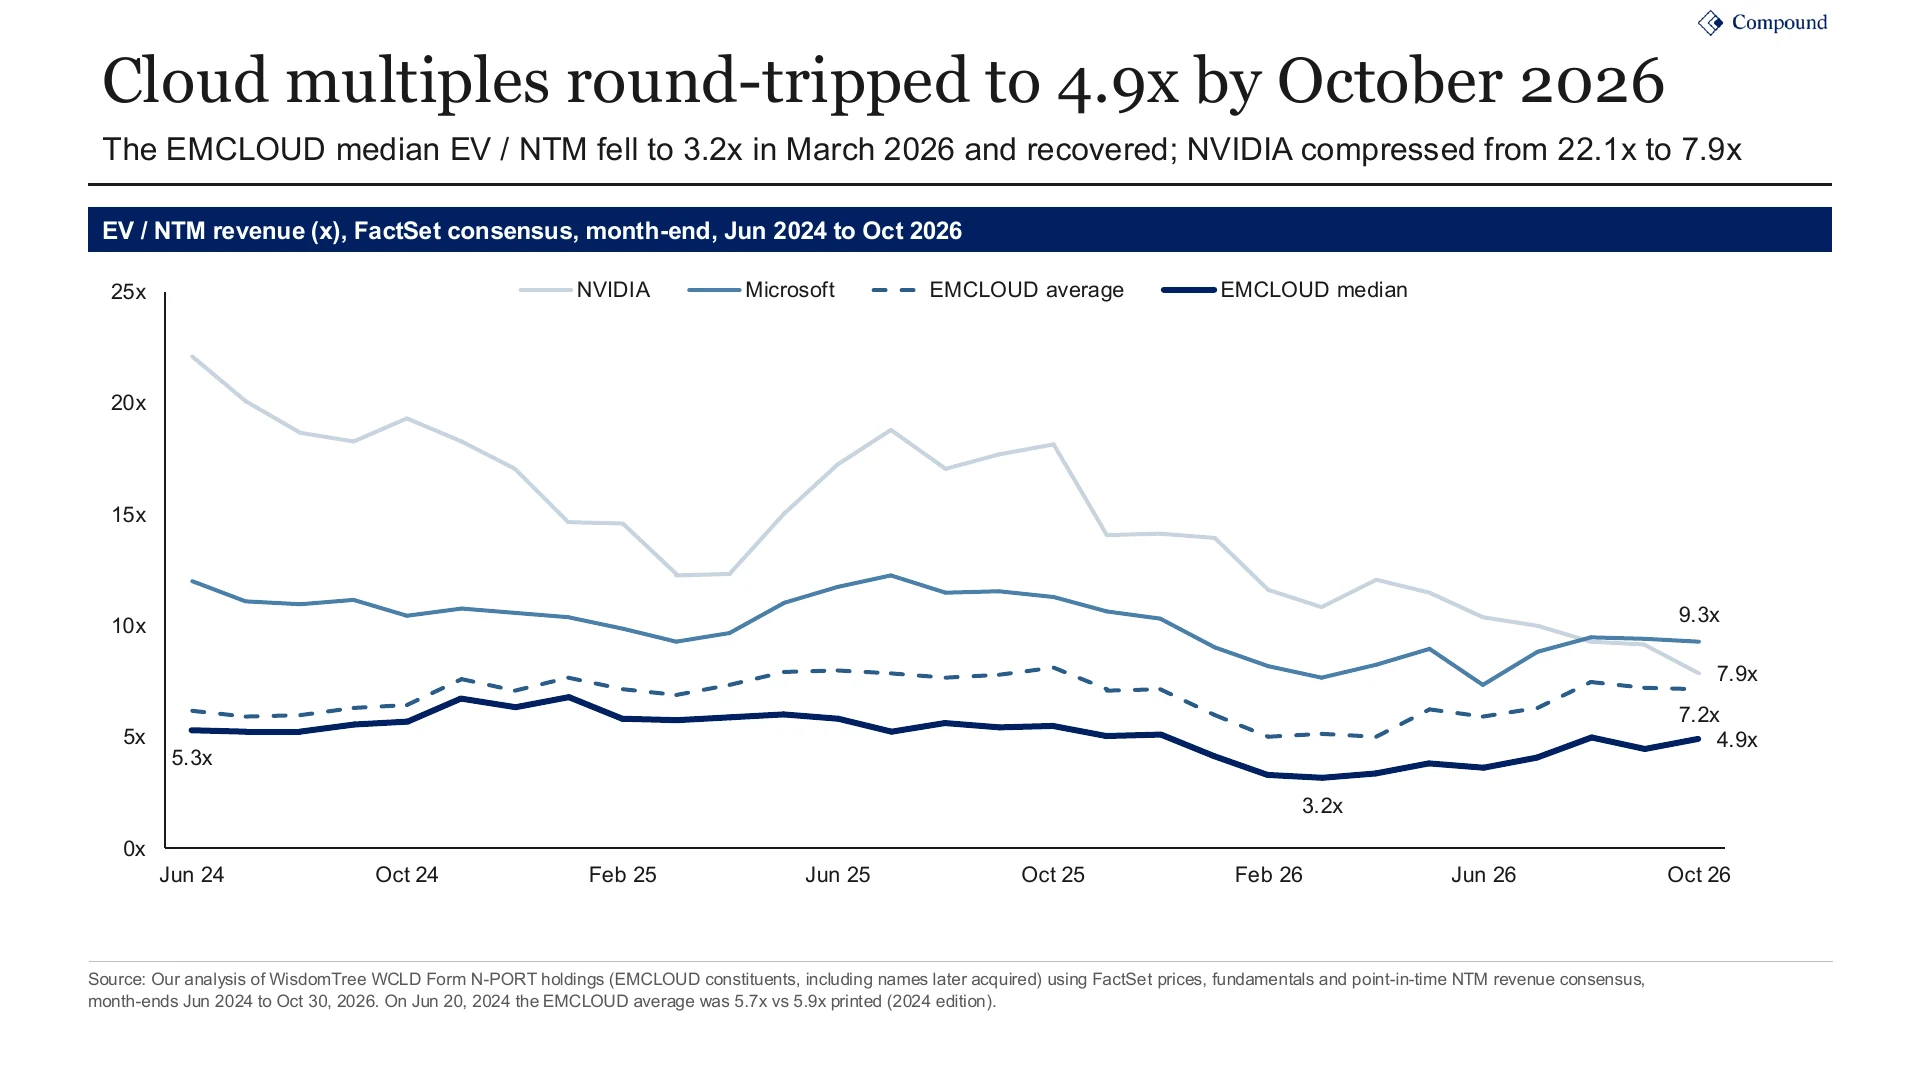
The constituents’ combined market cap rose 72%, to $2.52T, partly because Palantir and Palo Alto Networks joined the index. That is still below the $2.7T peak of November 2021. The index itself rose 48.8% from the report date, ahead of the Nasdaq Composite (+43.5%) and the S&P 500 (+38.5%), but it closed 31% below its 2021 high.
The partners’ one-year call was right
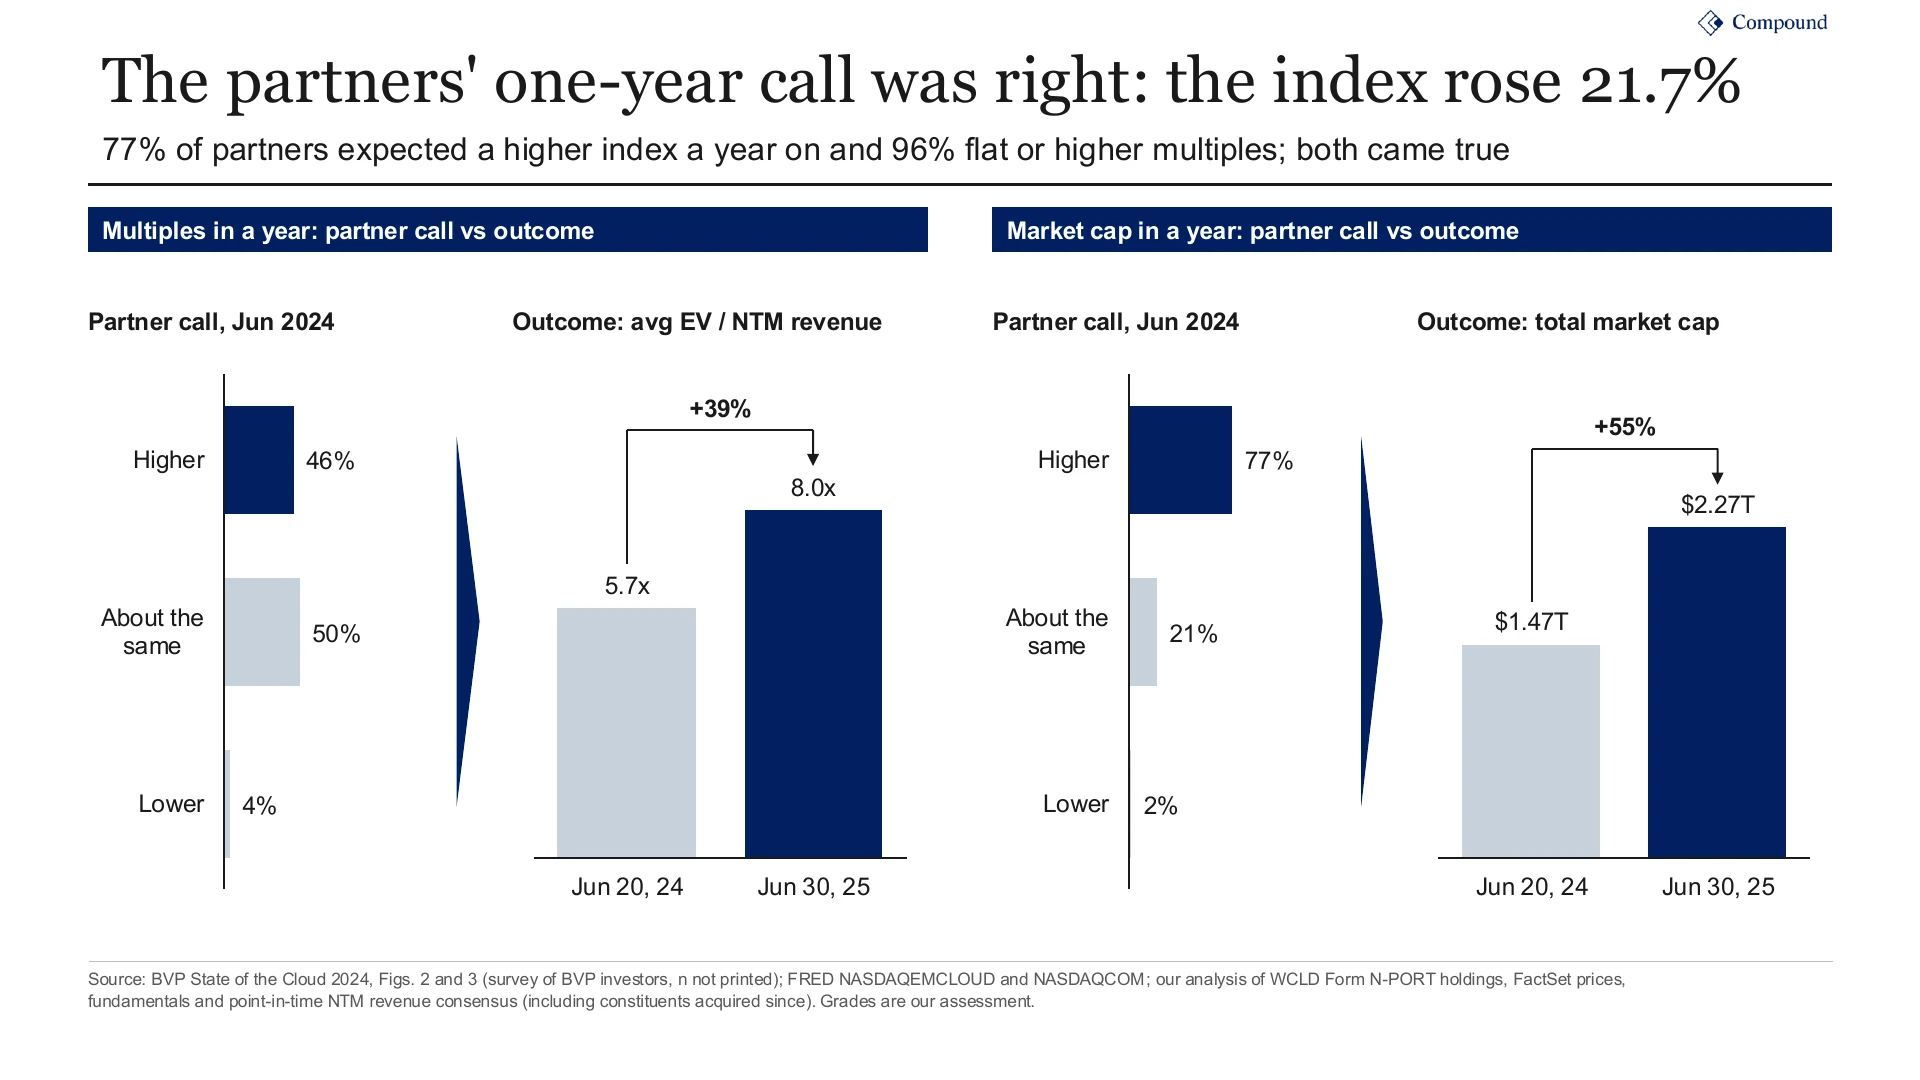
Bessemer surveyed its investors on where the index would be a year later. 77% expected a higher market cap and 96% expected multiples to be flat or higher. Both came true: by June 30, 2025, constituent market cap was up 55%, to $2.27T, and the average multiple had risen from 5.7x to 8.0x.
Growth still sets cloud valuations. Across EMCLOUD constituents, a point of forward revenue growth carried about 4.8 times the valuation weight of a point of free cash flow margin in October 2026. The 2023 edition printed 2:1.
The model layer grew faster than Bessemer expected
Bessemer expected “AI Model Giants” backed by cloud strategics to win the model layer, and it printed OpenAI at a $3.4B run-rate. Both pairings it named deepened: Microsoft holds about 27% of OpenAI Group PBC, and Amazon’s investment in Anthropic reached $8B. Anthropic is now valued at $965B and OpenAI at $852B. xAI, which was not in Bessemer’s chart, was folded into SpaceX at a $250B valuation, and Builder.ai, a Microsoft-backed name in the chart, entered insolvency in May 2025.
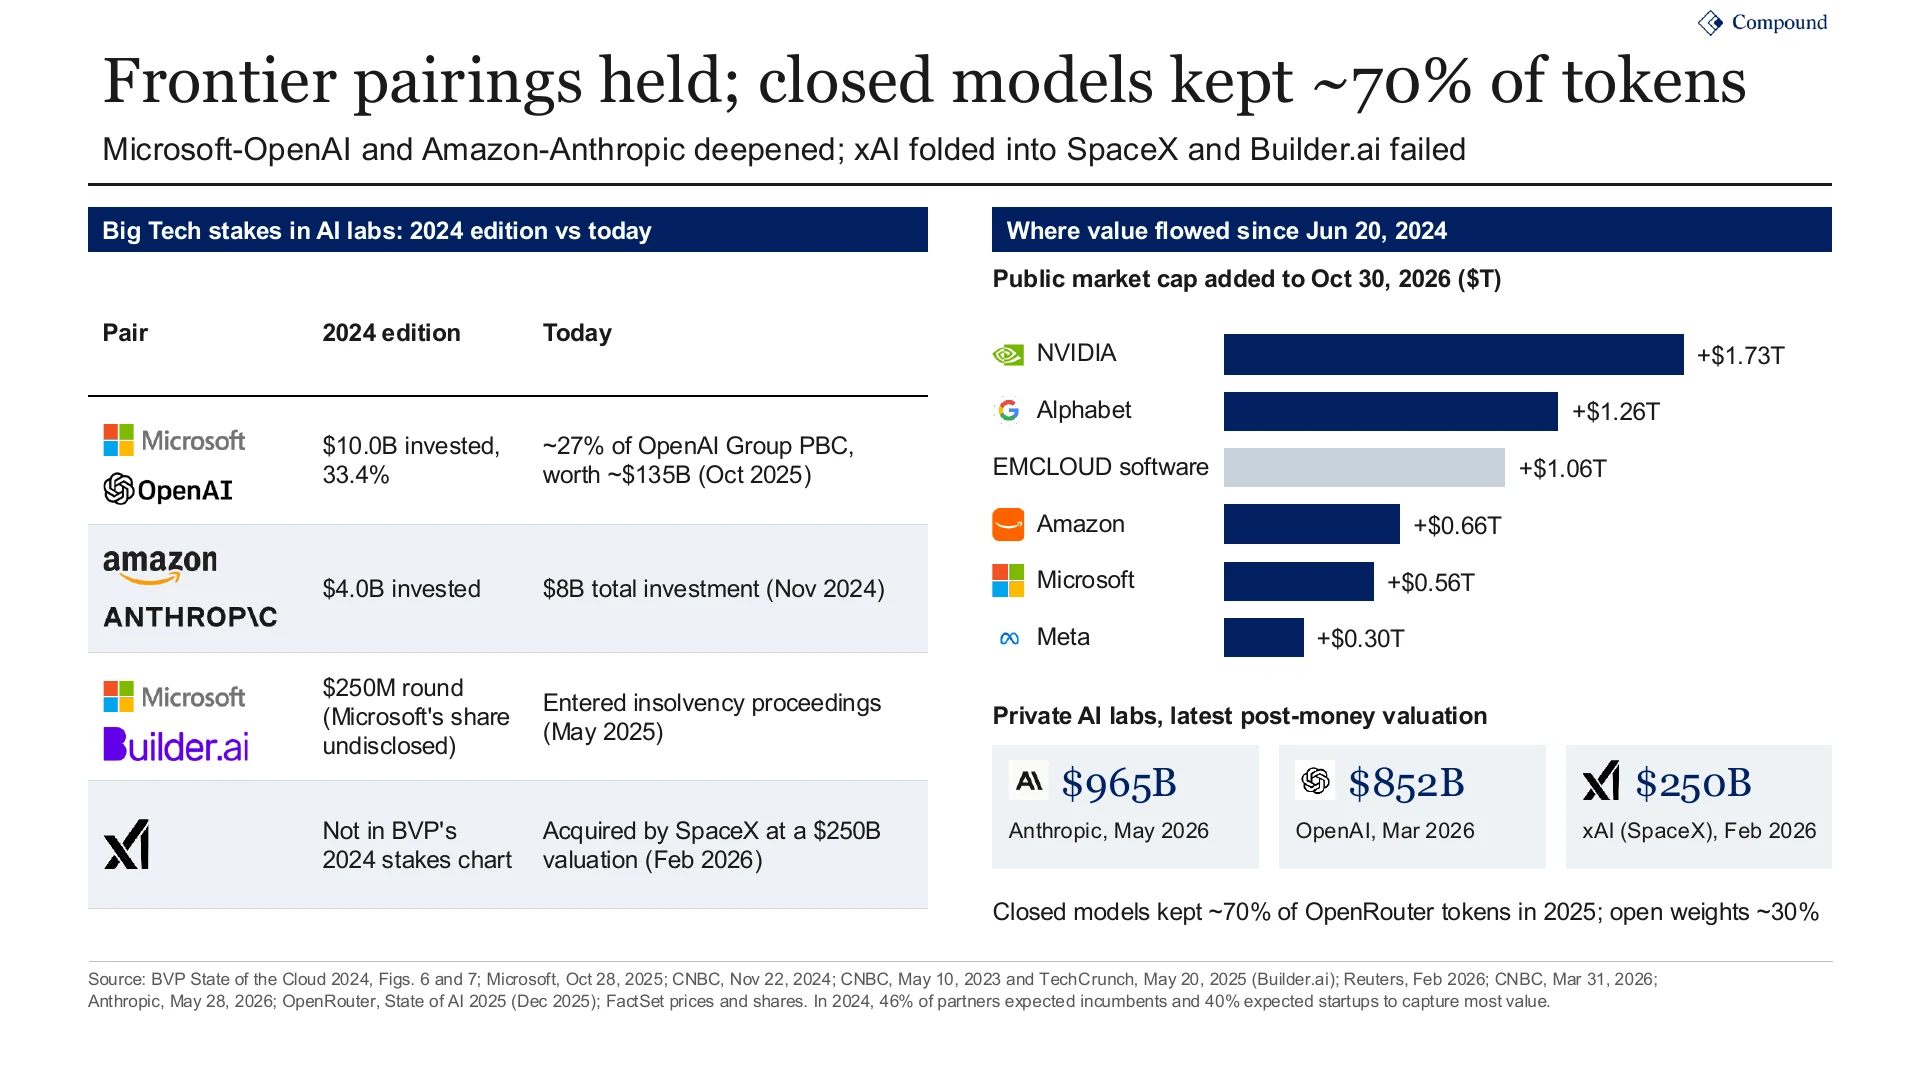
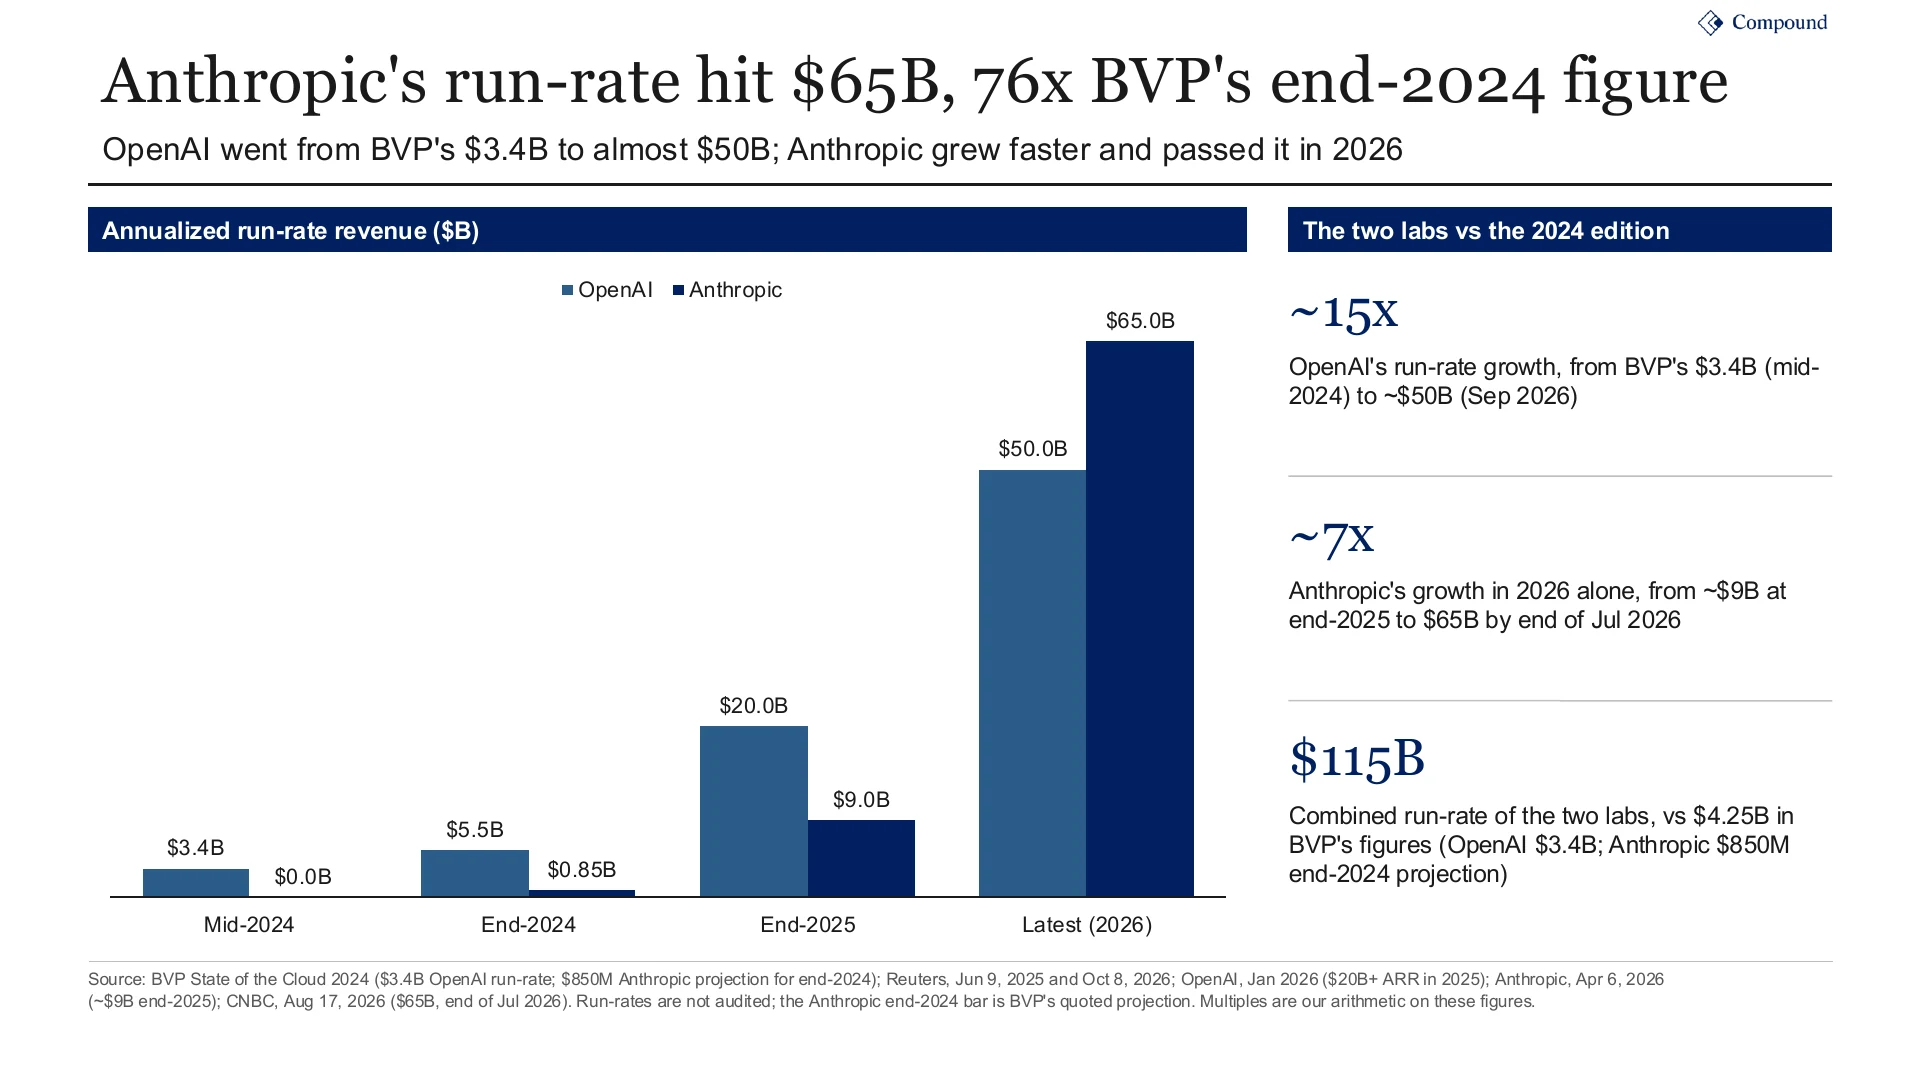
The labs’ revenue moved faster still. OpenAI’s run-rate grew about 15x, from $3.4B to about $50B. Anthropic went from Bessemer’s end-2024 projection of $850M to $65B by the end of July 2026, passing OpenAI. Model-layer funding, $23B in 2023 on Morgan Stanley’s count, reached $89B in 2025 and $178B in the first quarter of 2026 alone, on Crunchbase’s.
AI now writes most new code
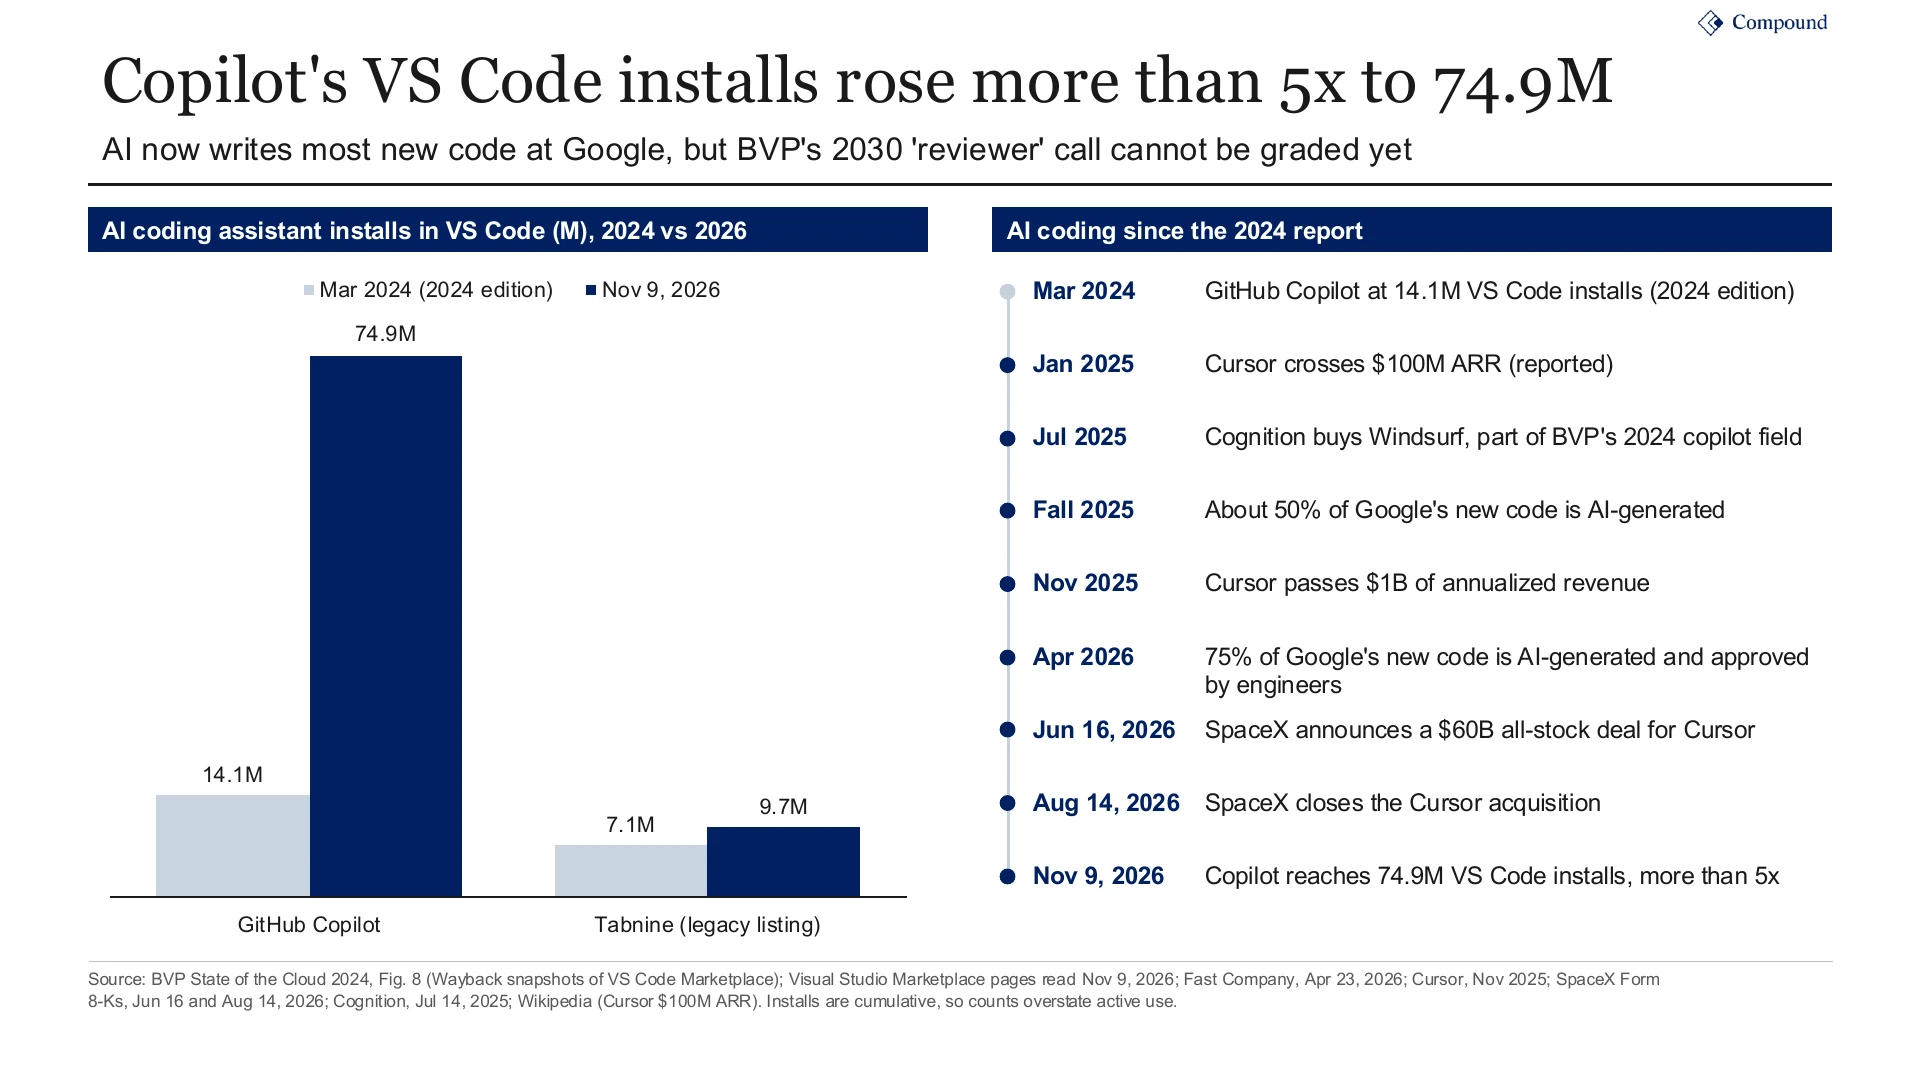
Bessemer charted 14.1M VS Code installs for GitHub Copilot and predicted that by 2030 most corporate developers would be code reviewers. Copilot now has 74.9M installs, though installs are cumulative and overstate active use. Cursor passed $1B of annualized revenue in November 2025, and SpaceX closed a $60B acquisition of it in August 2026. Google says 75% of its new code is AI-generated. That points the right way, but the call is about 2030.
Vertical AI at 0.18x legacy software
This call splits in two. Bessemer expected at least five Vertical AI Centaurs, companies with $100M of ARR, within two to three years. Six have reported it: Harvey, OpenEvidence, Legora, Abridge, EliseAI and EvenUp. But it also expected Vertical AI to reach at least 10x the market cap of legacy vertical software. The 13 leaders we count are worth $61.4B at their latest rounds, against $339B for the 20 largest US-listed vertical software companies. That is 0.18x. Getting to 10x would take about $3.4T.
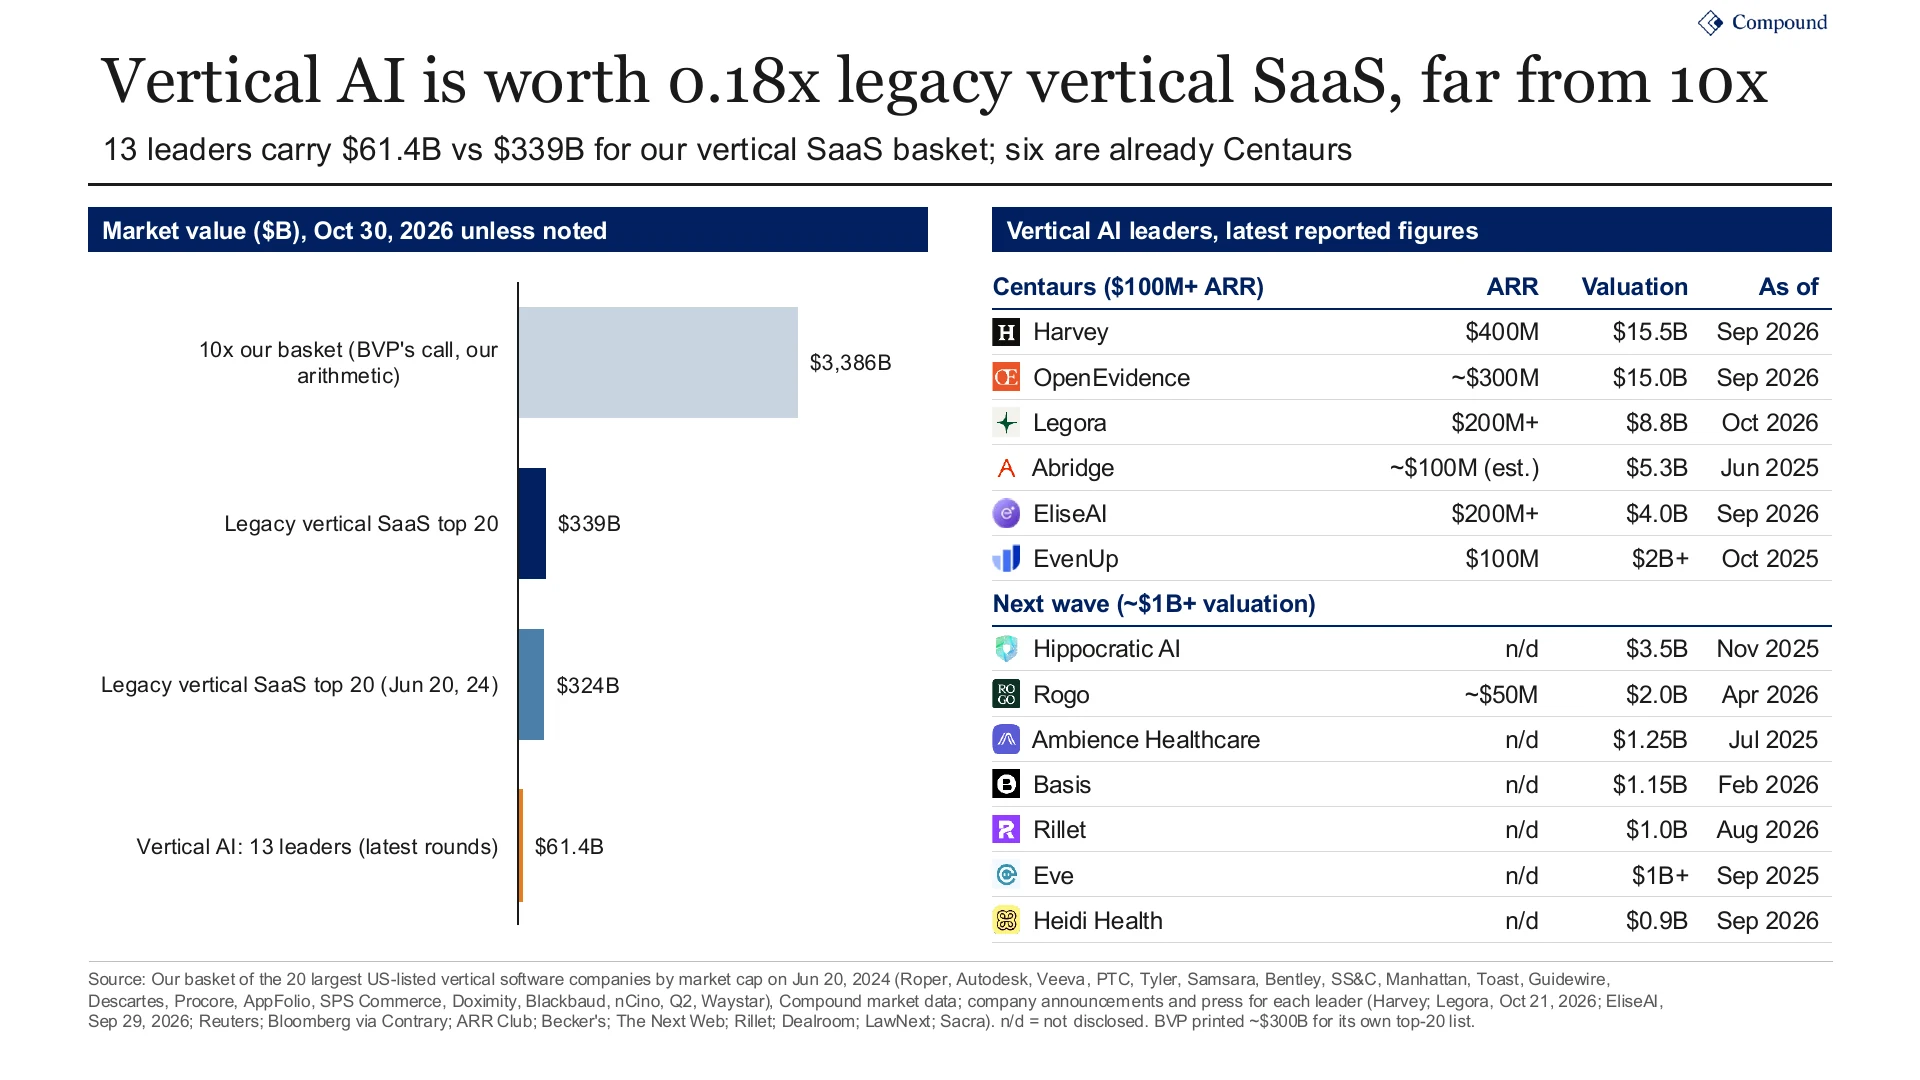
The list counts AI-native companies serving one industry with a dated public figure. It is close to complete for Centaurs and a selection below that. Adding 20 more $1B companies would lift the ratio to about 0.24x. No Vertical AI company has gone public yet, and the window for that call closes in June 2027.
Consumer AI without IPOs
ChatGPT’s web visits more than doubled, from 2.5B a month in May 2024, level with Reddit, to 5.9B in September 2026, and OpenAI reports 1.2B weekly users across web and app. That still puts it behind Google, YouTube and Facebook. Bessemer’s target is the top three spots by 2030. Its call for multiple consumer cloud IPOs within five years has one partial answer so far, Figma in July 2025.
What the report missed
The largest moves of the past two years were not in the report. The four hyperscalers’ trailing twelve-month capex rose 3.9x, from $158B to $615B. Public software sold off: EMCLOUD fell 18.6% below its report-date level by April 10, 2026. Ownership concentrated, with SpaceX absorbing both xAI and Cursor. And the labs out-earned the apps: Anthropic’s $65B run-rate passed OpenAI’s, about $50B.
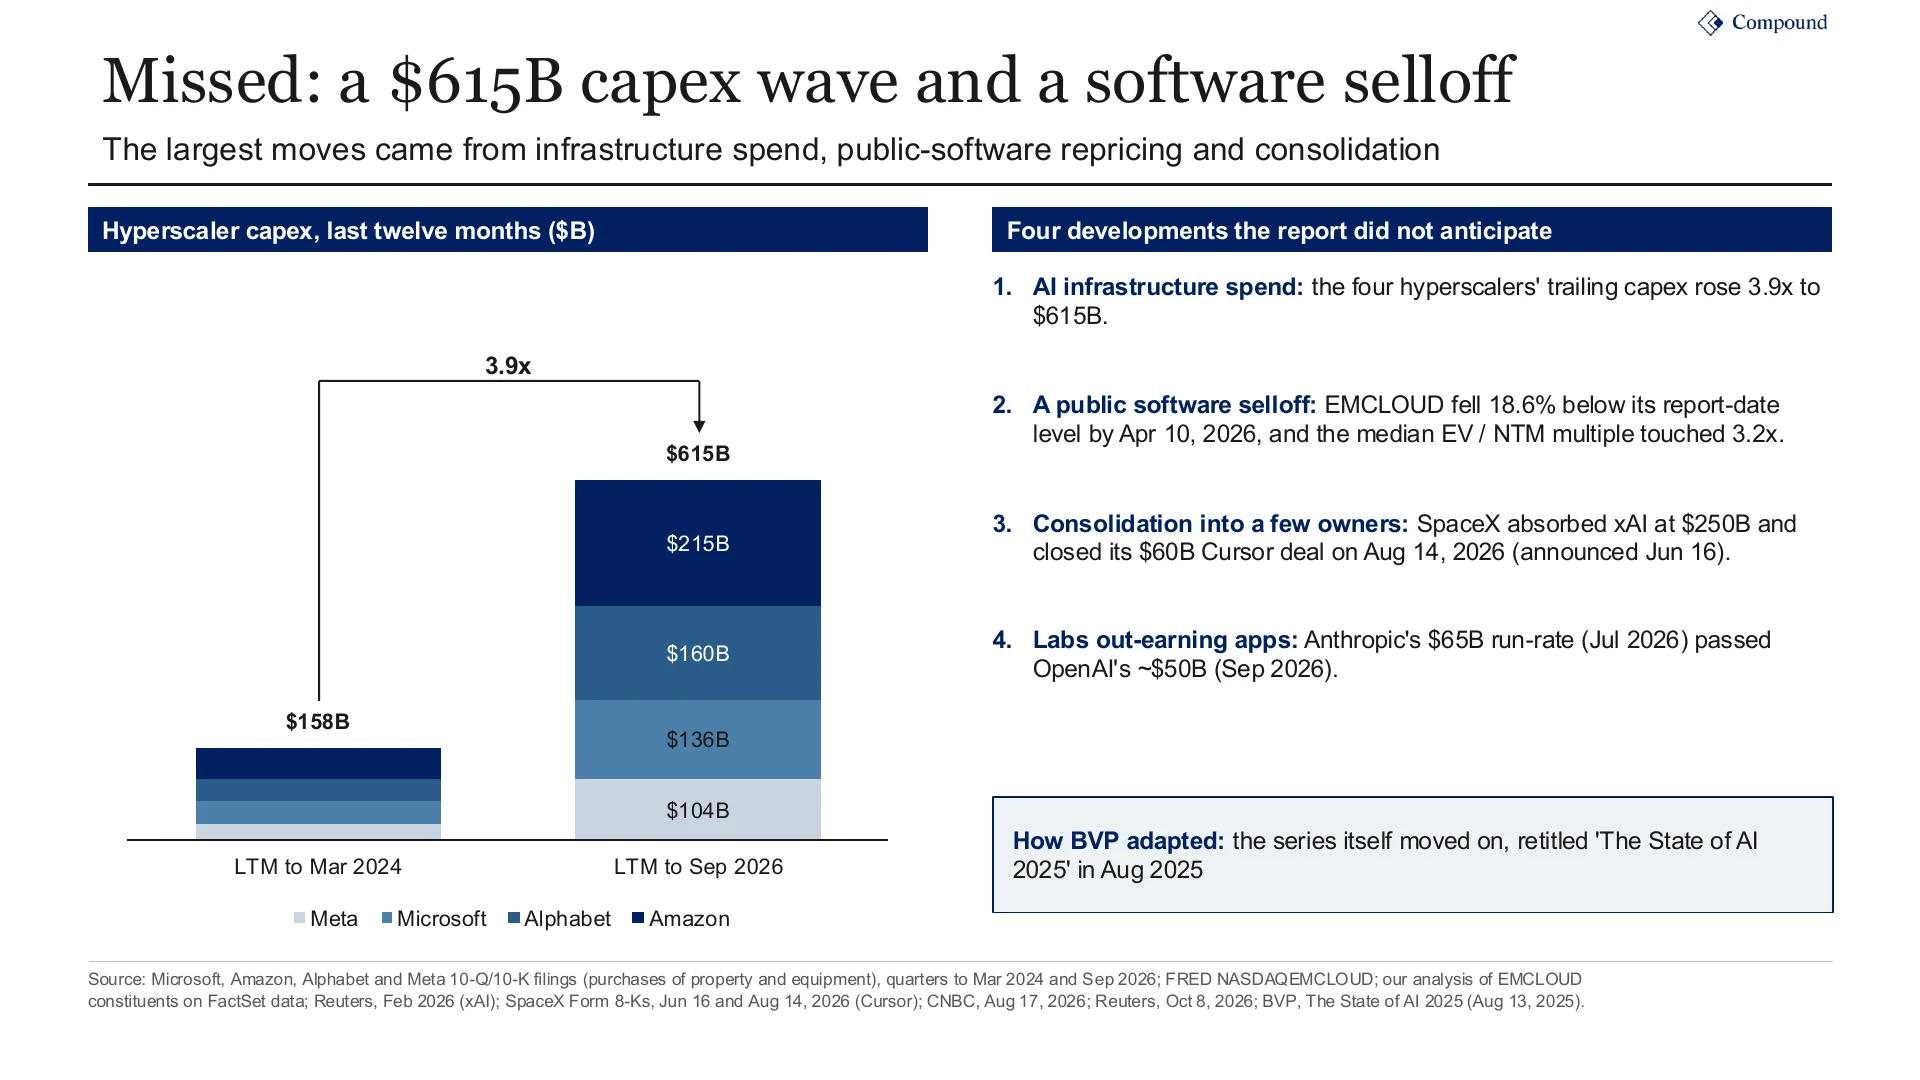
Bessemer adapted with the market. Its closing prediction, that AI would not give up “a photon of its current spotlight” by the next report, was right, and in August 2025 it retitled the series The State of AI 2025.
How we built it
Compound read the 2024 report and its 23 exhibits, plus the 2023 edition as the public-market baseline, and turned each forecast into a measurable test. It rebuilt EMCLOUD from the WisdomTree Cloud Computing Fund’s quarterly holdings filings, including companies acquired since, and priced every constituent from FactSet with point-in-time consensus revenue on each date. Its recompute of the original matches closely: 5.7x on the report date against 5.9x printed, and a Rule of 40 premium of 1.7x against about 1.7x printed. Private figures come from company announcements and dated press, and each slide of the downloadable deck names its sources and dates. See industry research with Compound.
Frequently asked questions
What was Bessemer’s State of the Cloud 2024 report?
The annual cloud report from Bessemer Venture Partners, published June 20, 2024 and subtitled “The Legacy Cloud is dead, long live AI Cloud!” Built on a survey of 62 Bessemer investors, it set out five AI trends: model giants, AI coding, multimodal and voice agents, Vertical AI and consumer AI.
Was Bessemer right about the cloud in 2024?
So far, yes where the calls can be graded. Of ten calls we tested, four were right and six are too early to grade, mostly because they run to 2027 to 2030. None is wrong yet. The furthest from target is Vertical AI reaching 10x legacy vertical software, which stands at 0.18x.
Where do cloud software multiples stand in October 2026?
On our rebuild of EMCLOUD from its constituents, the average EV/NTM revenue was 7.2x and the median 4.9x on October 30, 2026, after a low of 3.2x for the median in March 2026. For the largest listed software companies, see our SaaS valuation multiples for 2026.
How big is Vertical AI compared with vertical SaaS?
The 13 Vertical AI leaders we track are worth $61.4B at their latest private valuations, against $339B for the 20 largest US-listed vertical software companies: 0.18x. Six of them have passed $100M of ARR.
Sources: Bessemer Venture Partners, State of the Cloud 2024 (June 20, 2024), State of the Cloud 2023 (April 11, 2023) and The State of AI 2025 (August 13, 2025); WisdomTree Cloud Computing Fund (WCLD) Form N-PORT holdings; FactSet prices, fundamentals and point-in-time NTM revenue consensus; FRED (NASDAQEMCLOUD, NASDAQCOM, SP500); Microsoft, Amazon, Alphabet and Meta 10-Q and 10-K filings; Crunchbase News; OpenRouter, State of AI 2025; Similarweb; Visual Studio Marketplace; company announcements from OpenAI, Anthropic, Microsoft, Cursor, Harvey and others, and dated press from Reuters, CNBC, TechCrunch and Forbes. Data as of October 30, 2026. Private valuations and run-rates are reported, not audited. Grades are our assessment.