CrowdStrike Q3 Earnings Preview: $0.33 EPS vs $0.31 Consensus
CrowdStrike reports Tuesday after the close. Our model puts net new ARR 9% above guidance, revenue 2.0% above consensus at $1.56 billion and EPS at $0.33 against $0.31.
CrowdStrike reports fiscal third-quarter results on Tuesday, Dec. 1, after the U.S. market close, with the call at 2 p.m. PT, the company said in a Nov. 4 announcement. The quarter ended Oct. 31.
Compound's model forecasts Q3 net new annual recurring revenue (ARR) of $376 million, 9% above the $345 million midpoint implied by CrowdStrike's guidance. We forecast revenue of $1.56 billion, 2.0% above the FactSet consensus of $1.53 billion, and non-GAAP EPS of $0.33 against a consensus of $0.31.
CRWD closed at $219.58 on Nov. 17, according to FactSet prices. That is 21.3% below its record close of $278.86 on Oct. 6 and 87.4% above where it ended 2025. The shares rose 20.5% on Aug. 27, the day after the second-quarter report.
We built an 11-page earnings preview deck on the model, in the format of our Nike Investor Day memo. The slides below come from it, and the deck and the Excel model are free to download at the end.
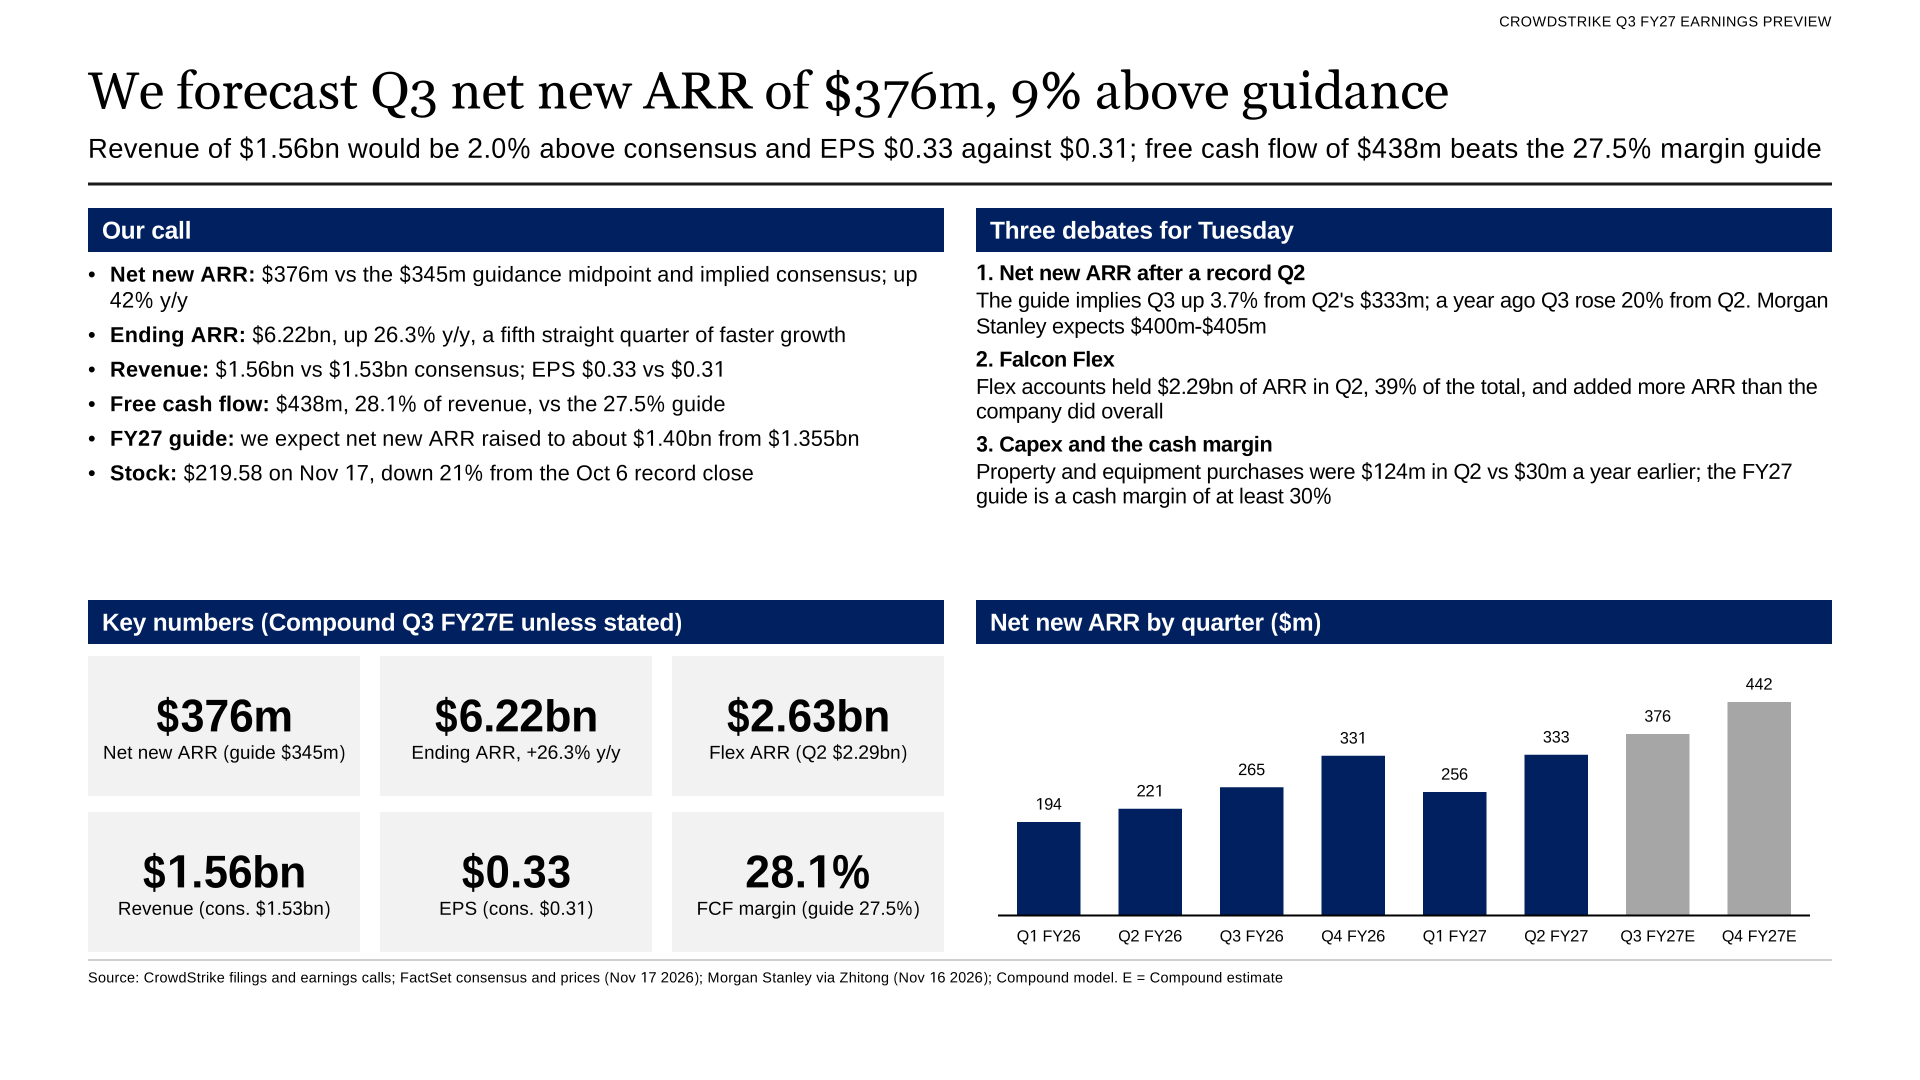
Executive summary: our call against guidance and consensus, and the three debates for Tuesday.
Forecast vs consensus
| Q3 FY27 | Guidance | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Net new ARR | $345M | $345M | $376M | +8.8% |
| Ending ARR | $6.19B | $6.19B | $6.22B | +0.5% |
| Revenue | $1.526B | $1.528B | $1.559B | +2.0% |
| Operating income | $374M | $376M | $399M | +6.1% |
| Operating margin | 24.5% | 24.6% | 25.6% | +1.0 pt |
| EPS | $0.31 | $0.31 | $0.33 | +5.6% |
| Free cash flow | $420M | n/a | $438M | n/a |
| Free cash flow margin | 27.5% | n/a | 28.1% | n/a |
Consensus is the FactSet mean as of Nov. 17. Net new ARR consensus is backed out of Morgan Stanley's Nov. 13 preview, which put its own estimate 15.8% to 17.2% above consensus, as reported by Zhitong (unconfirmed). Guidance is the midpoint of the ranges CrowdStrike gave on Aug. 26; free cash flow guidance applies the 27.5% margin to the revenue midpoint. Non-GAAP figures are as CrowdStrike reports them; per-share figures reflect the four-for-one split of July 1.
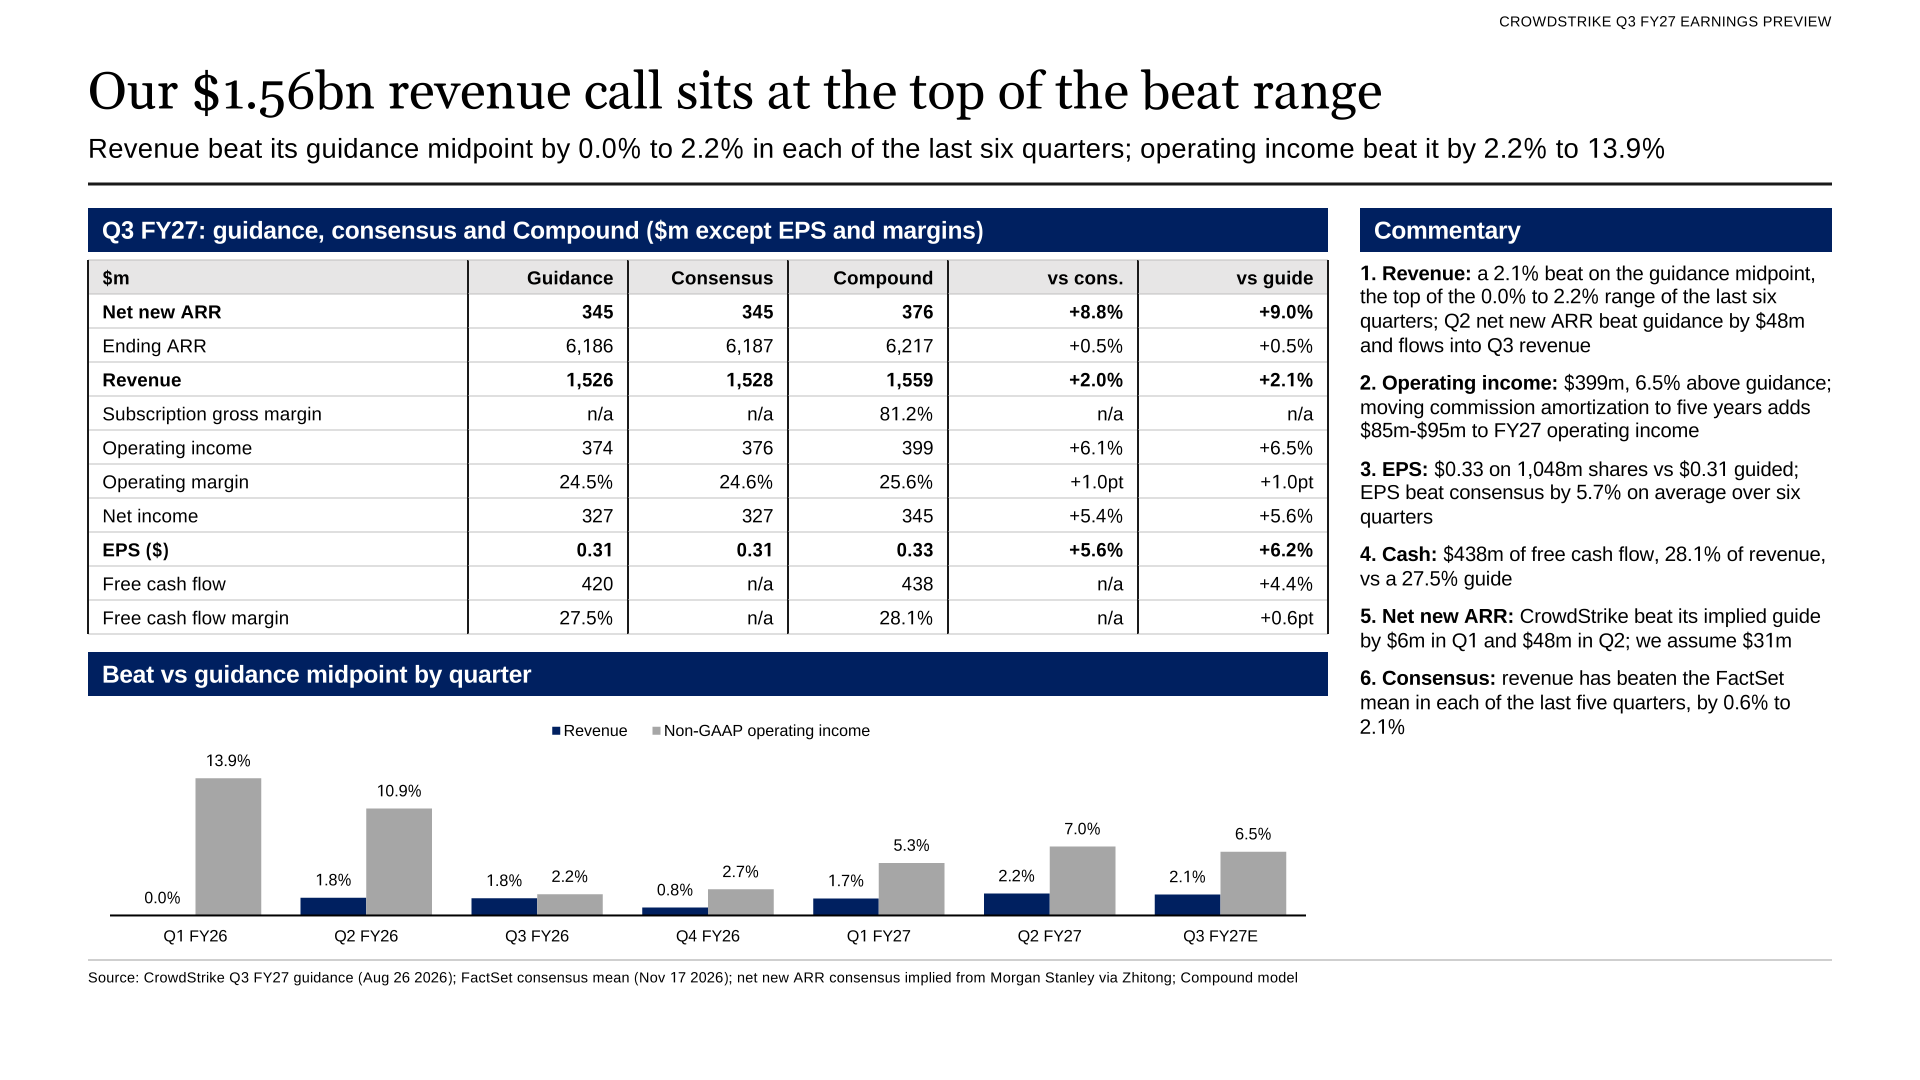
CrowdStrike beat its revenue guidance midpoint by 0.0% to 2.2% in each of the last six quarters; we assume 2.1%.
Net new ARR
On Aug. 26 CrowdStrike guided Q3 ending ARR of $6.184 billion to $6.188 billion. CFO Burt Podbere said on the call that this translates to net new ARR of $343 million to $347 million, up 29% to 31% from a year earlier. The midpoint is 3.7% above Q2's record $332.8 million. A year ago, Q3 net new ARR rose 20% from Q2.
CrowdStrike started guiding ARR this fiscal year. It beat the implied net new ARR midpoint by $6 million in Q1 and by $48 million in Q2. We assume a 9% beat, about the average of the two, for $376 million. Podbere said the company left Q2 with a record Q3 pipeline and that net and gross dollar retention both improved from Q1.
Morgan Stanley expects $400 million to $405 million, citing a survey in which 63% of partners said CrowdStrike business was ahead of plan, up from 40% in Q2, according to Zhitong's account of the note (unconfirmed). Q2 was CrowdStrike's best quarter on record, and we do not assume a repeat of its 17% beat.
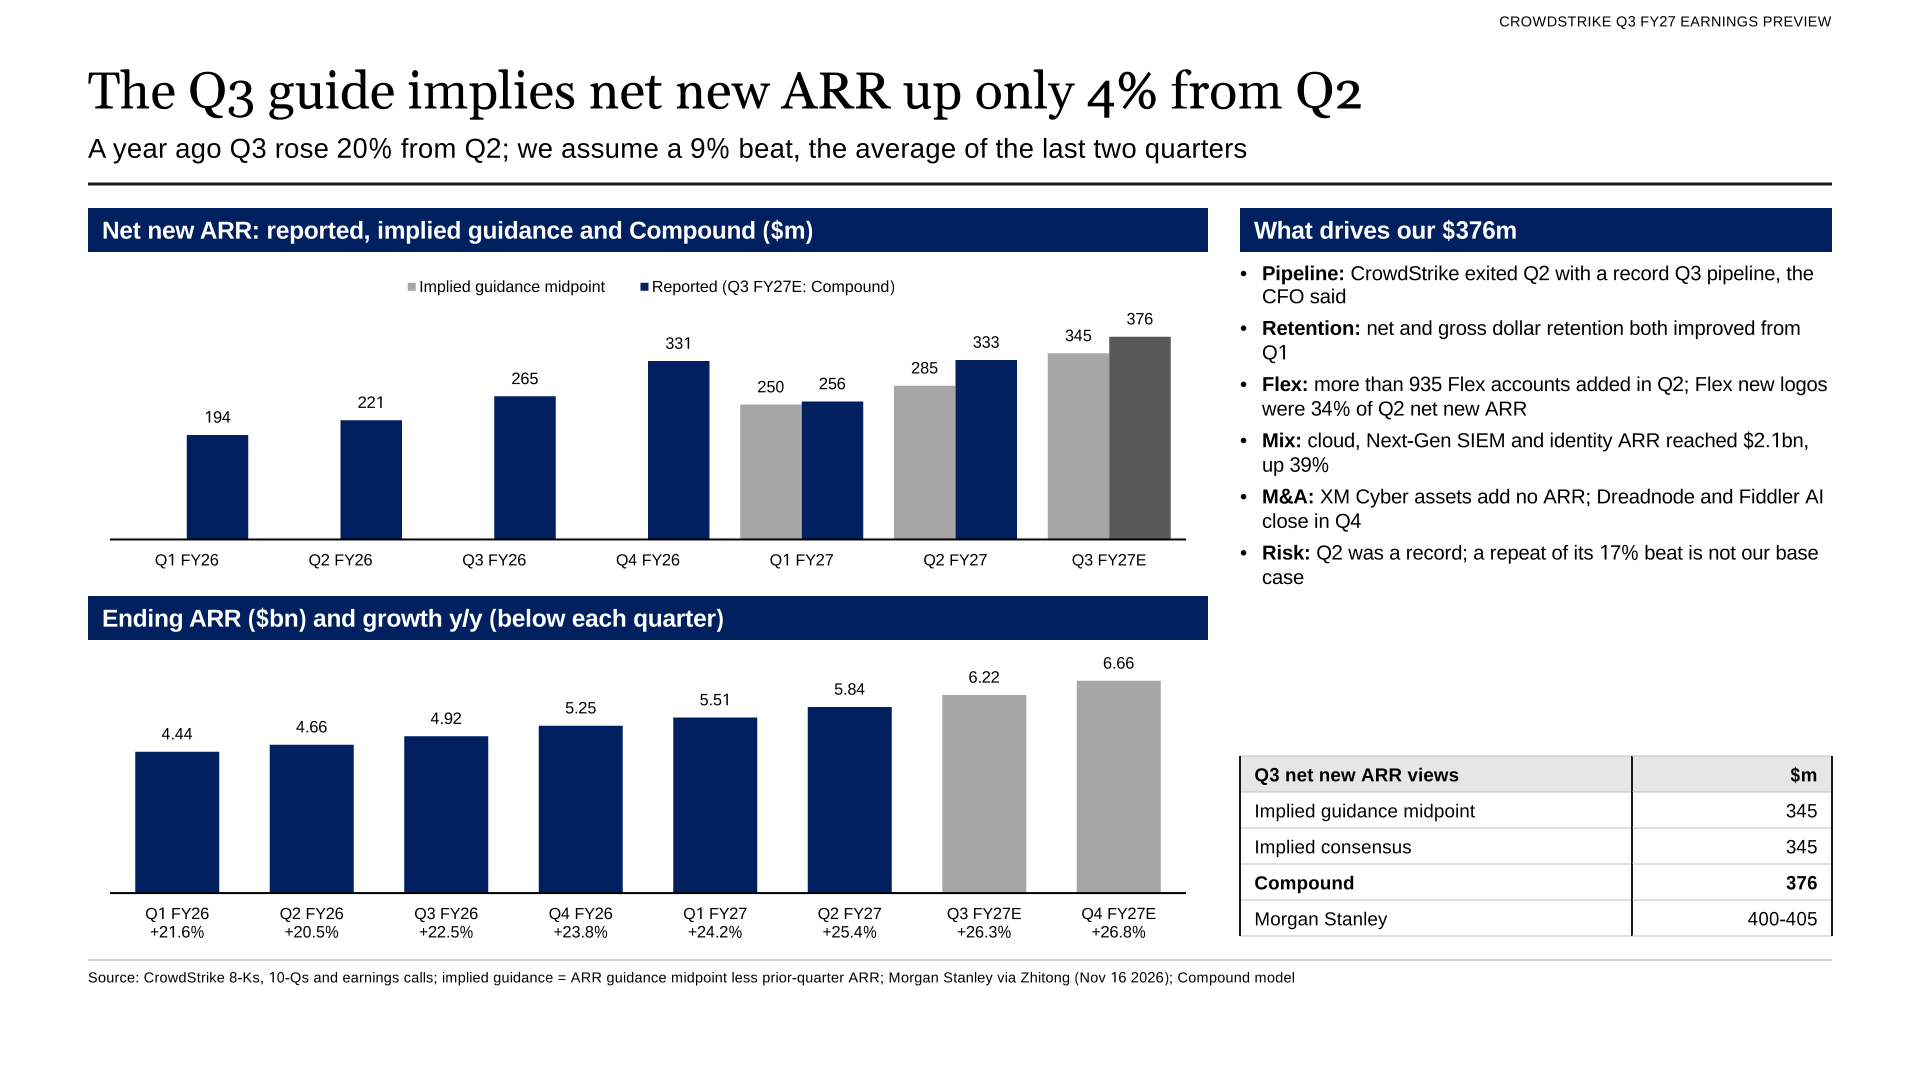
Net new ARR by quarter against the midpoint implied by ARR guidance, and ending ARR growth.
Ending ARR of $6.22 billion would be up 26.3% from a year earlier, after 25.4% in Q2. It would be the fifth straight quarter of faster ending ARR growth.
Falcon Flex
Falcon Flex lets customers commit to a platform spend upfront and draw it down across products. Accounts that have adopted it held more than $2.29 billion of ending ARR at the end of Q2, up 101% from a year earlier, CrowdStrike said on Aug. 26. That is 39% of total ARR, up from 27% in Q3 of fiscal 2026.
Flex account ARR rose $390 million in Q2, more than the $333 million of total net new ARR. ARR outside Flex accounts has stayed between $3.55 billion and $3.61 billion for four quarters, because conversions move existing customers into Flex. CEO George Kurtz said on the call that customers converting to Flex show an average ending ARR uplift of more than 40%, and that CrowdStrike added more than 935 Flex accounts in Q2.
We model Flex ARR rising 15% from Q2 to $2.63 billion, 42% of total ARR.
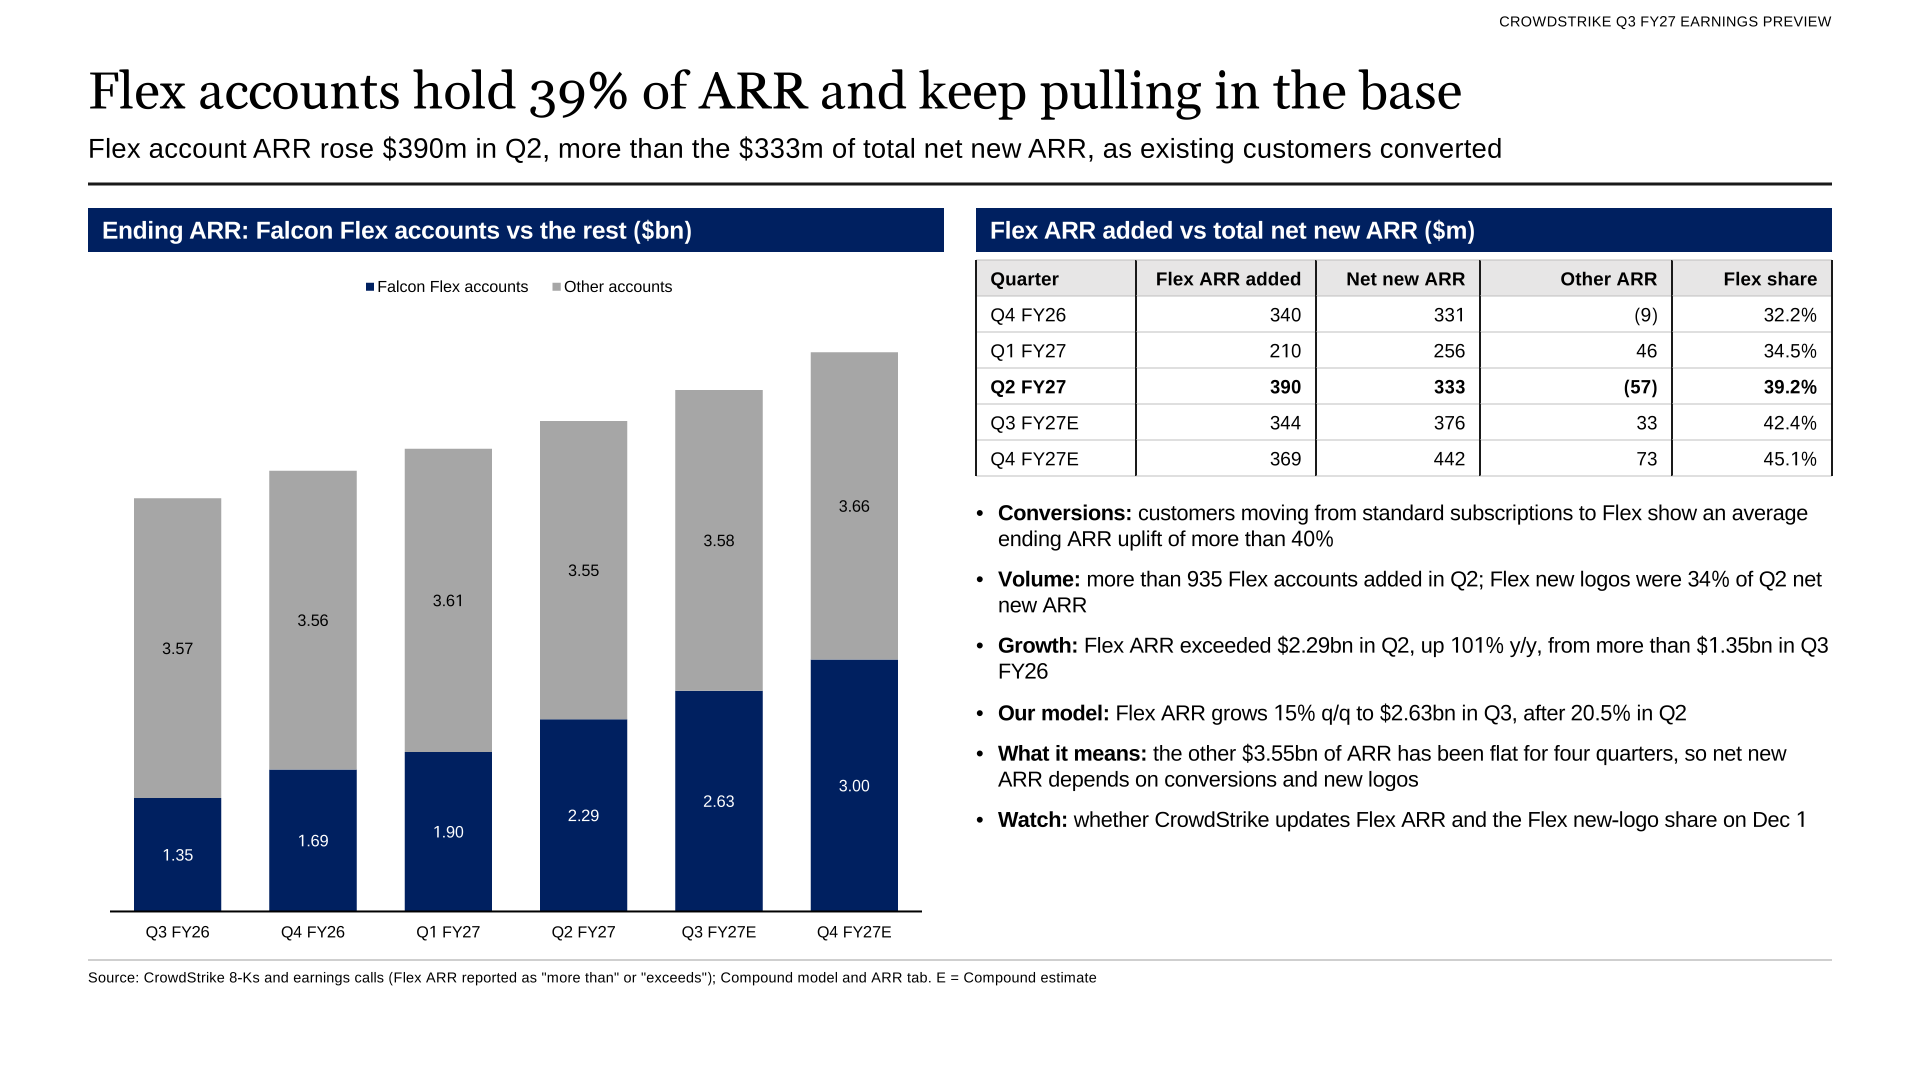
Falcon Flex accounts against the rest of ending ARR, and Flex ARR added each quarter against total net new ARR.
Margins and EPS
We forecast non-GAAP operating income of $399 million, a 25.6% margin, against guidance of $372.7 million to $375.9 million and a consensus of $376 million. CrowdStrike beat its operating income guidance midpoint by 2.2% to 13.9% in each of the last six quarters. This year it amortizes sales commissions over five years instead of four, which Podbere said in March would add $85 million to $95 million to fiscal 2027 operating income.
Our $0.33 EPS uses the 1.048 billion diluted shares and 21% tax rate in CrowdStrike's guidance. The EPS sensitivity in the model is a native Excel data table: each half point of sales and marketing spend moves Q3 EPS by about $0.006.
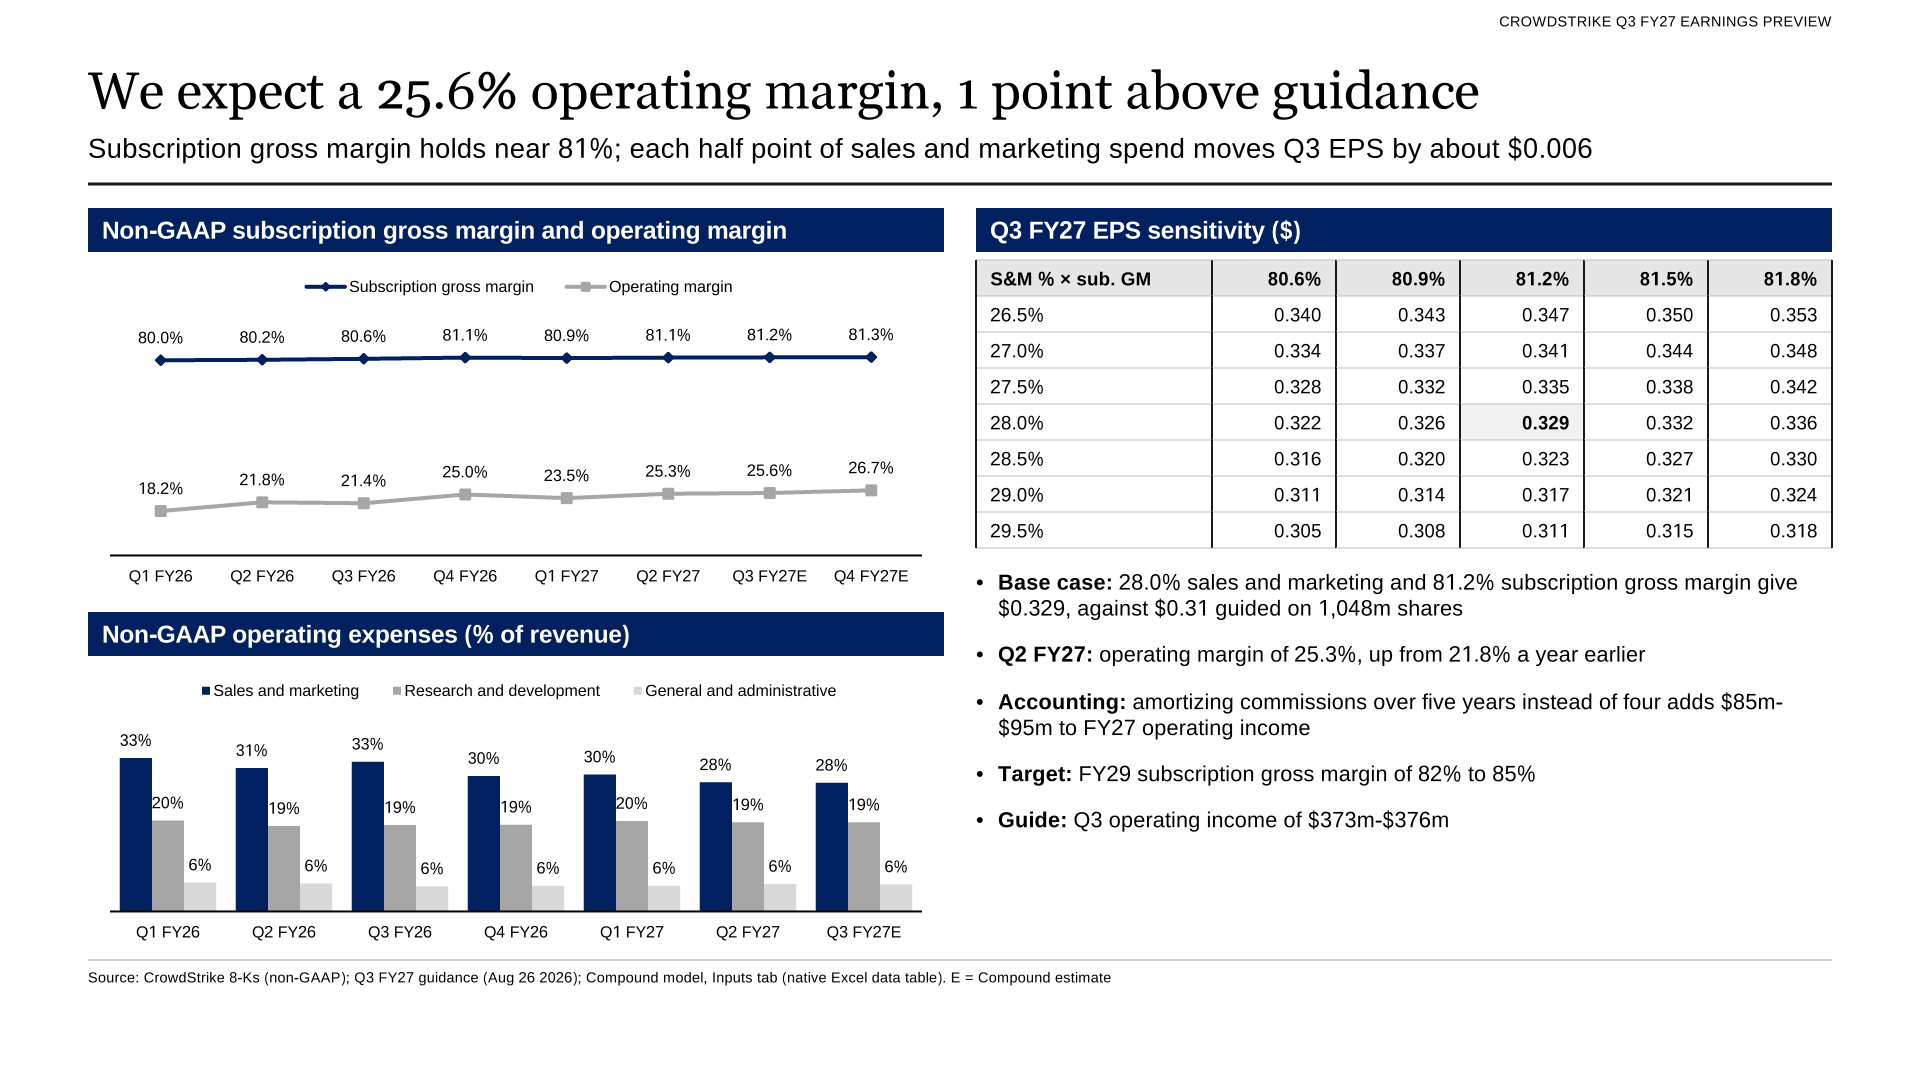
Margins by quarter and the EPS sensitivity from the model.
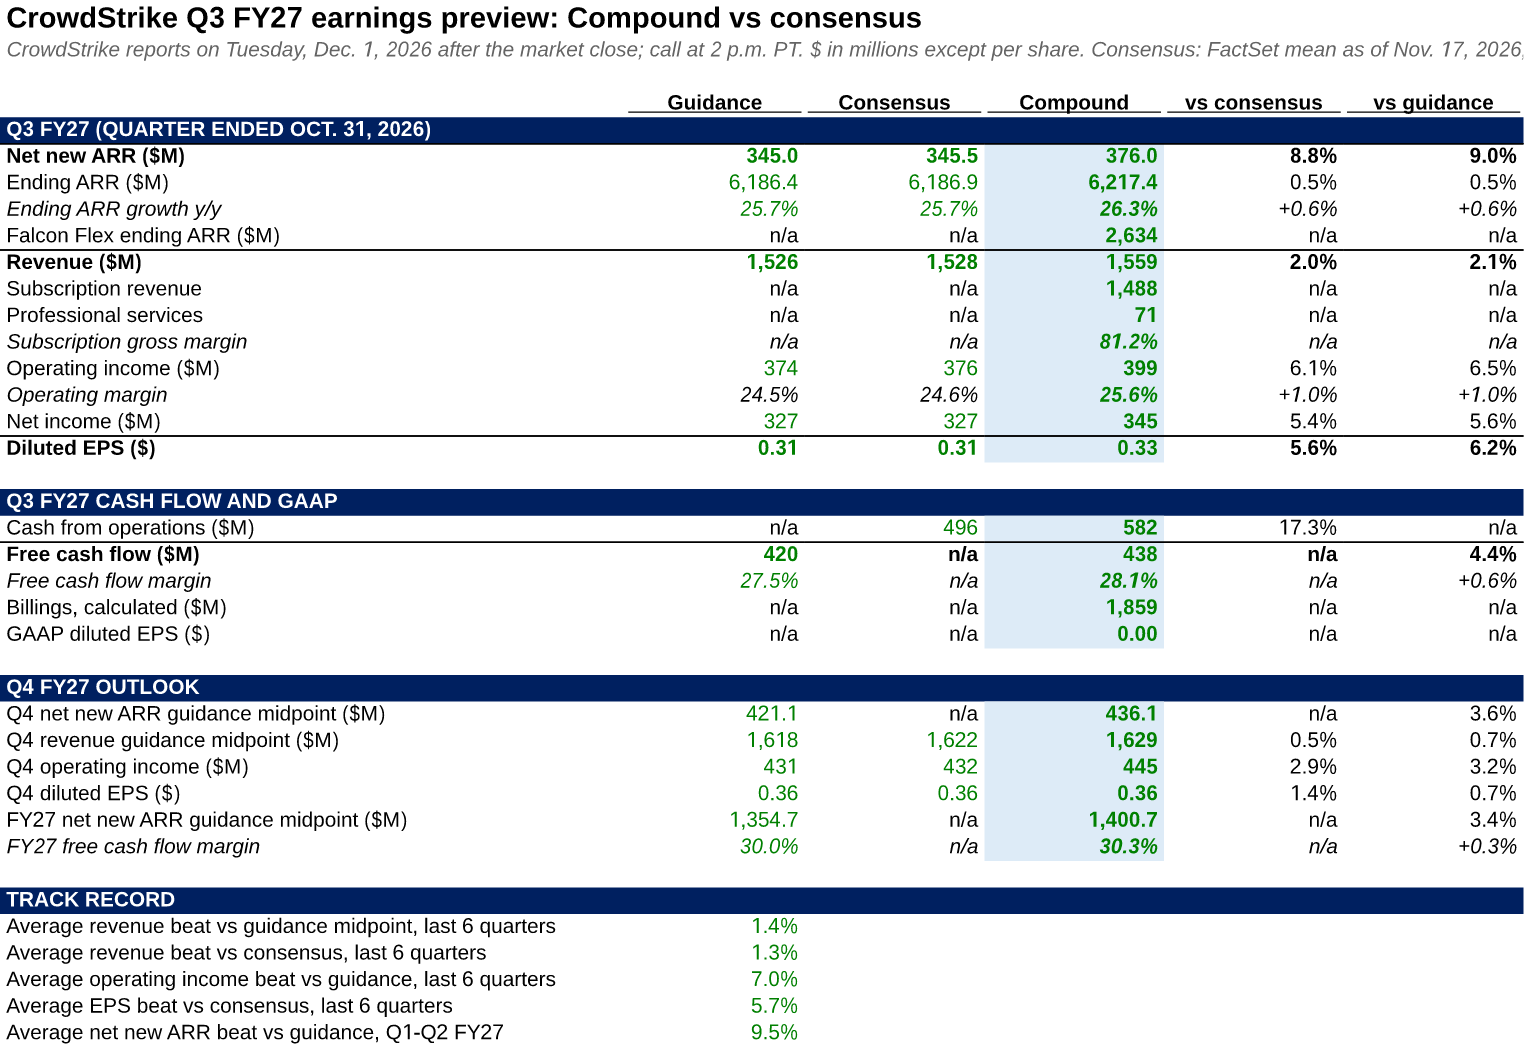
The Preview tab of the Excel model, which links every estimate to its drivers.
Free cash flow margin
Podbere guided a Q3 free cash flow margin of 27.5% at the midpoint and at least 30% for fiscal 2027 on Aug. 26. First-half free cash flow was $846 million, 29.6% of revenue.
We forecast Q3 free cash flow of $438 million, 28.1% of revenue. Capital spending is the drag: purchases of property and equipment were $124 million in Q2, against $30 million a year earlier, and we model $115 million. We assume deferred revenue rises $300 million in the quarter, against $228 million a year ago, and days sales outstanding of 71, against 76. Two days of DSO move the Q3 margin by about 2.2 percentage points.
Q2 free cash flow was 26% of revenue, against the 24.5% CrowdStrike had expected. On our numbers fiscal 2027 free cash flow is $1.84 billion, 30.3% of revenue.
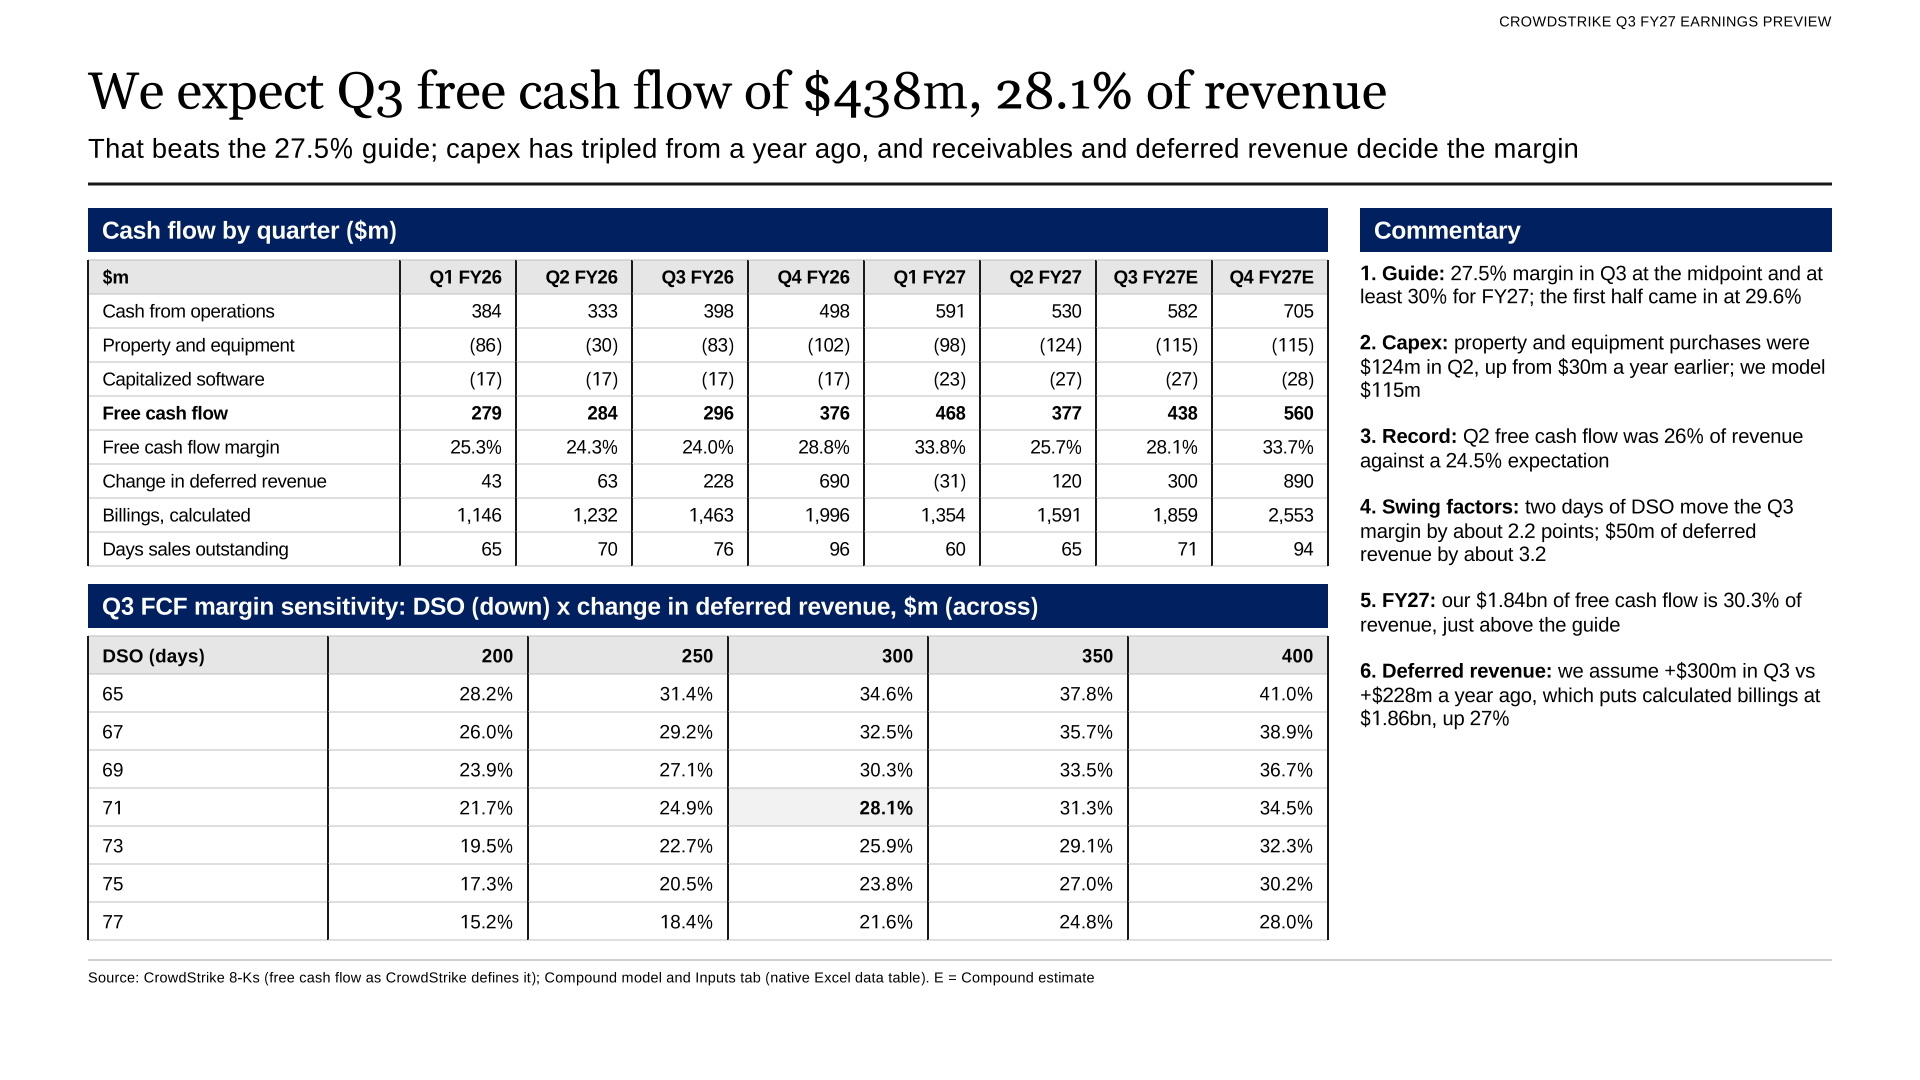
Cash flow by quarter and the free cash flow margin sensitivity from the model.
Q4 guidance
The August guide implies Q4 net new ARR of $421 million: fiscal 2027 net new ARR of $1.350 billion to $1.359 billion, less the first three quarters. CrowdStrike raised the full-year figure by $52 million in June after a $6 million Q1 beat, and by $64 million in August after a $48 million Q2 beat. We expect it to pass through our $31 million Q3 beat and add $15 million to Q4, for about $1.40 billion for the year.
Consensus for Q4 revenue is $1.62 billion, per FactSet. Over the last six quarters CrowdStrike's next-quarter revenue guidance midpoint ran 3.8% to 4.9% above the quarter it had just reported. A 4.5% step on our Q3 estimate gives about $1.63 billion.
At its Fal.Con investor briefing on Sept. 2, management said it expects at least 20% net new ARR growth in fiscal 2028 and a free cash flow margin of at least 32.5%, StreetAccount reported. On the current guide that is a floor of about $1.63 billion of net new ARR.
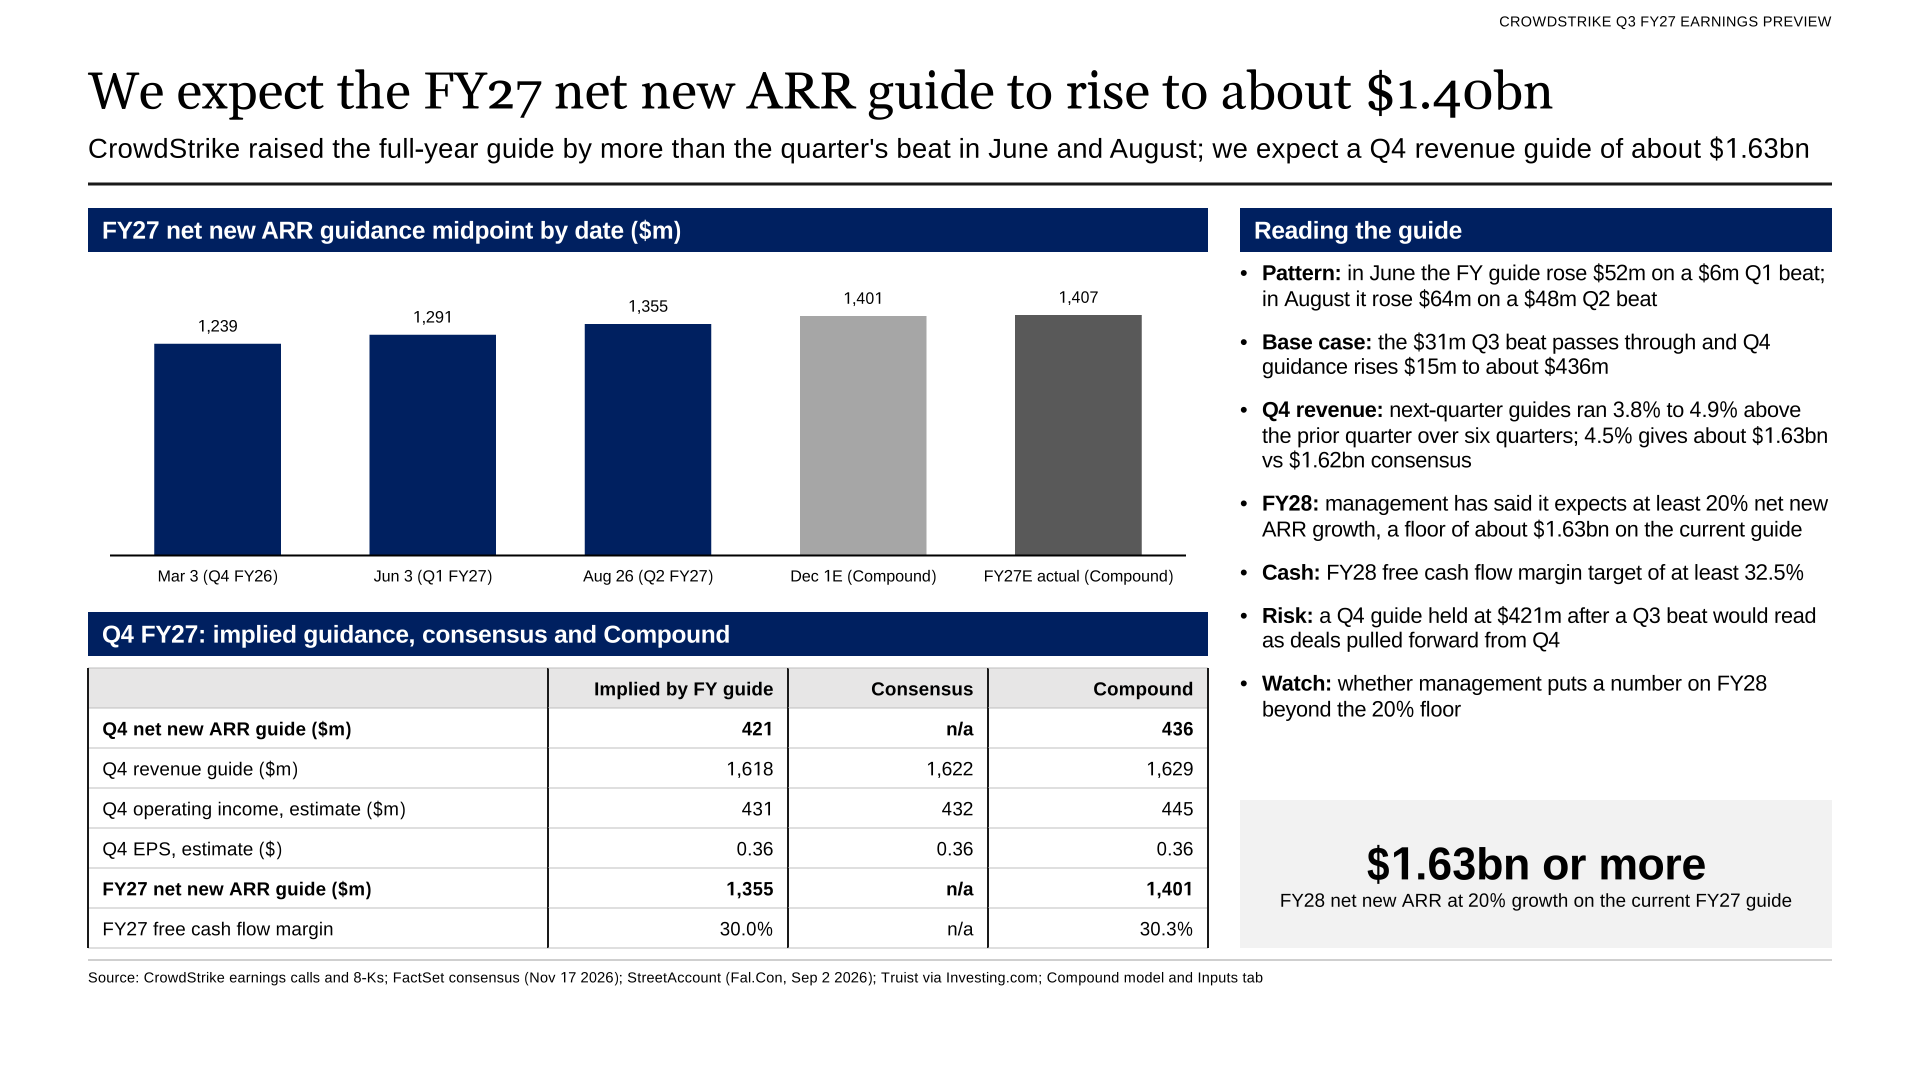
Fiscal 2027 net new ARR guidance by date, and the Q4 outlook against consensus.
Product areas
Cloud security, Next-Gen SIEM and identity ending ARR reached $2.1 billion in Q2, up 39%, Podbere said, 36% of the total. Kurtz said Next-Gen SIEM ending ARR passed $695 million, cloud passed $905 million, up more than 29%, and identity passed $585 million, up 34%. Podbere put Next-Gen SIEM growth at 60%. Kurtz said AI detection and response ending ARR nearly tripled from Q1.
Morgan Stanley said revenue from Falcon Guardian, CrowdStrike's product for securing AI agents, only began to appear in late October, so Q3 growth rests on SIEM, cloud and existing customers, according to Zhitong (unconfirmed).
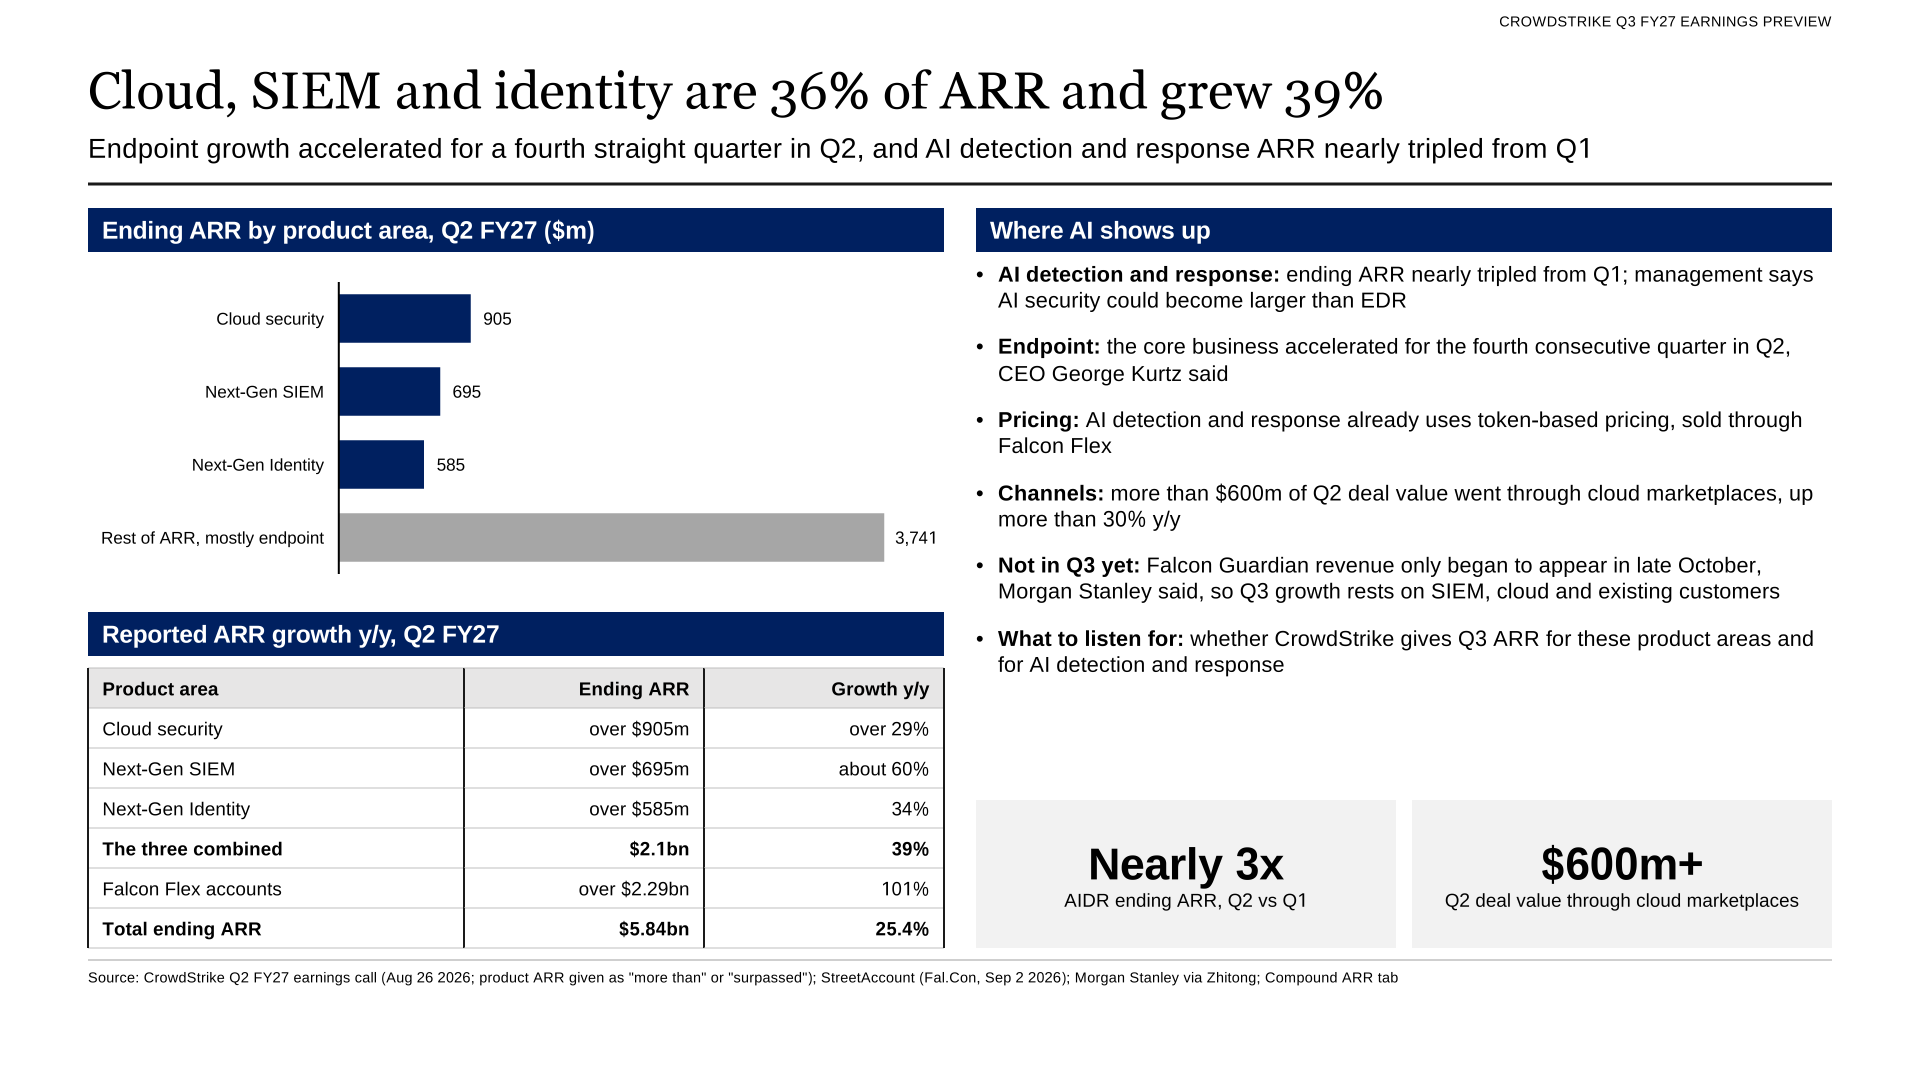
Ending ARR by product area in Q2, and where AI shows up.
The stock
CRWD rose 20.5% to $227.96 on Aug. 27, the day after the Q2 report, according to FactSet prices. It closed at a record $278.86 on Oct. 6.
Deutsche Bank upgraded the stock to buy on Nov. 2 with a $300 target, StreetAccount reported. The FactSet mean target is $255.65.
On Nov. 3 CrowdStrike agreed to buy Dreadnode and Fiddler AI on undisclosed terms, with both deals expected to close in its fiscal fourth quarter, StreetAccount reported.
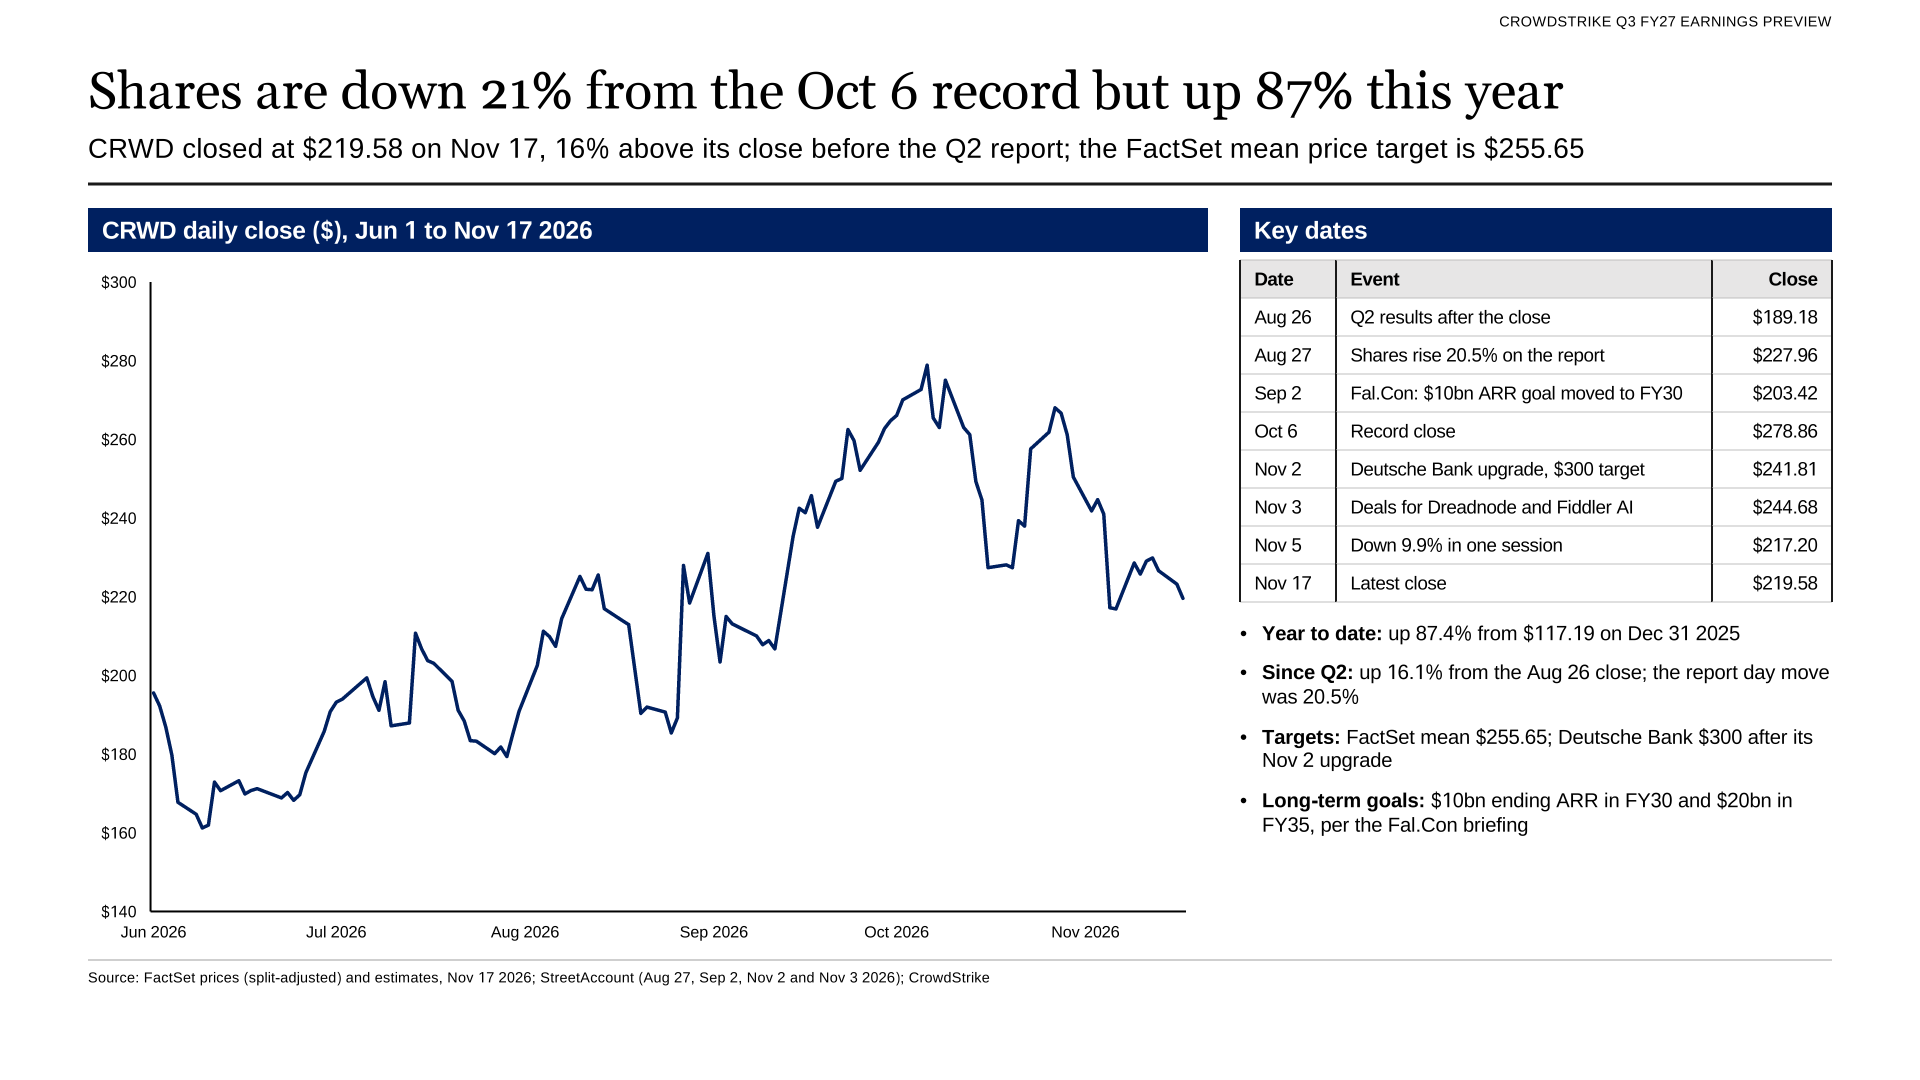
CRWD daily close since June, and the key dates.
What to watch on Tuesday
- Net new ARR against the $345 million guidance midpoint and our $376 million.
- Ending ARR growth against 25.4% in Q2; anything above that extends the run of faster growth to five quarters.
- Any update on Falcon Flex ARR, last at more than $2.29 billion.
- Free cash flow margin against the 27.5% guide, and capital spending against $124 million in Q2.
- The fiscal 2027 net new ARR guide against $1.355 billion, and Q4 revenue guidance against $1.62 billion consensus.
- Any fiscal 2028 figures beyond the floor of 20% net new ARR growth.
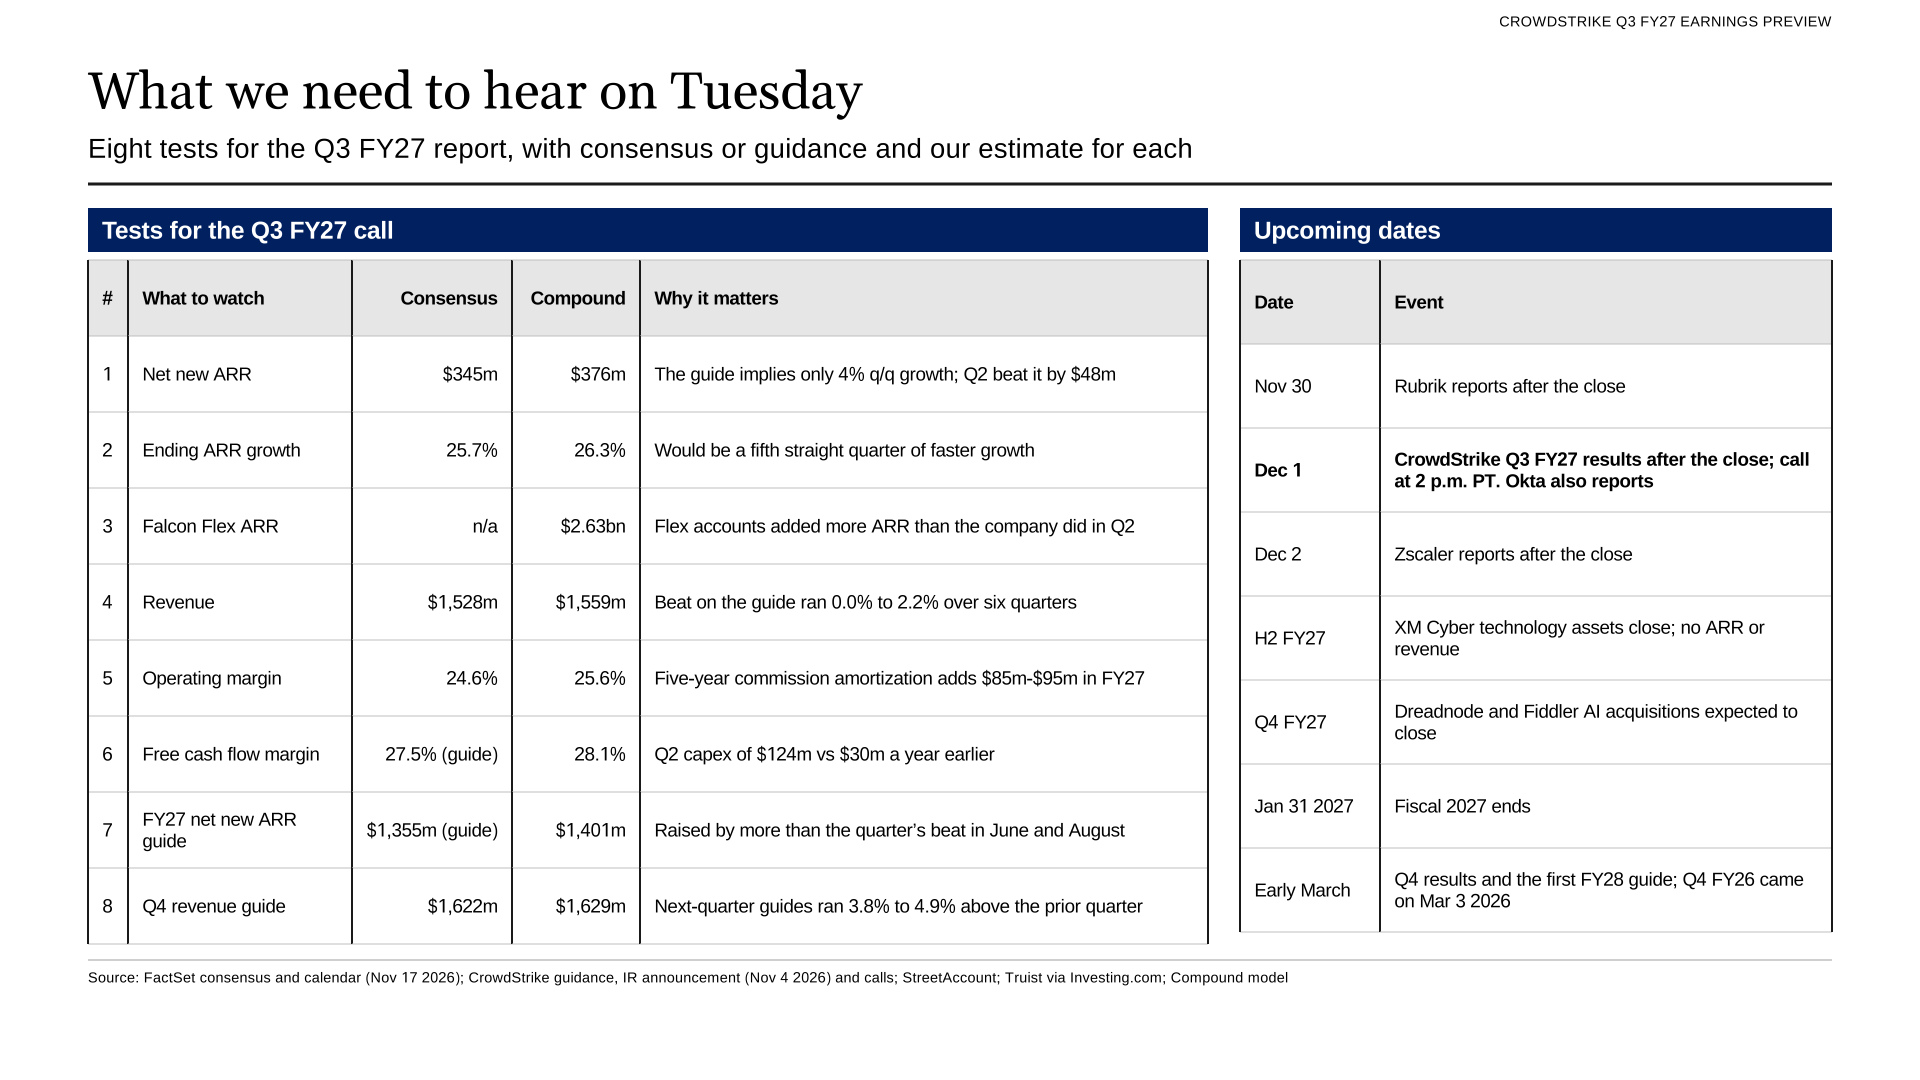
Eight tests for the report, with consensus and our estimate for each.
We will score this forecast against the reported numbers after the release on Dec. 1.
 CrowdStrike Q3 FY27 earnings preview deck (PowerPoint)The 11-page preview: executive summary, forecast against consensus, net new ARR, Falcon Flex, margins and EPS sensitivity, free cash flow, Q4 and fiscal 2027 guidance, product areas, the share price since June and the checklist for the report, with editable charts and tables.Download · Free
 CrowdStrike Q3 FY27 earnings model (Excel)Quarterly model from Q1 FY26: ARR and Falcon Flex, revenue build, non-GAAP and GAAP income statements, cash flow, balance sheet and working capital, guidance and consensus track record, Compound's Q3 and Q4 FY27 estimates, native Excel sensitivity tables and an ARR tab, with formulas and sources.Download · Free
 CrowdStrike Q3 FY27 earnings preview deck (PDF)The same 11 pages as a PDF.Download · Free
More from Compound News
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Read article →
Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Read article →
Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Read article →