Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Marvell Technology reports fiscal third-quarter results on Tuesday, Dec. 1, after the market closes, with a call at 1:30 p.m. PT, according to the company's Nov. 6 announcement. On Nov. 2, alongside its all-stock agreement to buy Lumentum, Marvell said Q3 revenue was consistent with the $3.15 billion midpoint of its guidance and narrowed the range to plus or minus 2%.
Compound's model forecasts Q3 revenue of $3.17 billion, 0.6% above the midpoint and 0.5% above the FactSet consensus of $3.154 billion. We forecast non-GAAP EPS of $1.11 against consensus and a guidance midpoint of $1.10, and a Q4 revenue guide of about $3.75 billion against a $3.737 billion consensus.
The stock closed at $148.74 on Nov. 17, down 40.9% from $251.65 on Oct. 28, the last close before reports of the Lumentum talks, and 53% below its June 4 record close of $316.43. It is still up 75% in 2026.
We built an 11-page earnings preview deck on the model. The slides below come from it, and the deck and the Excel model are free to download at the end.
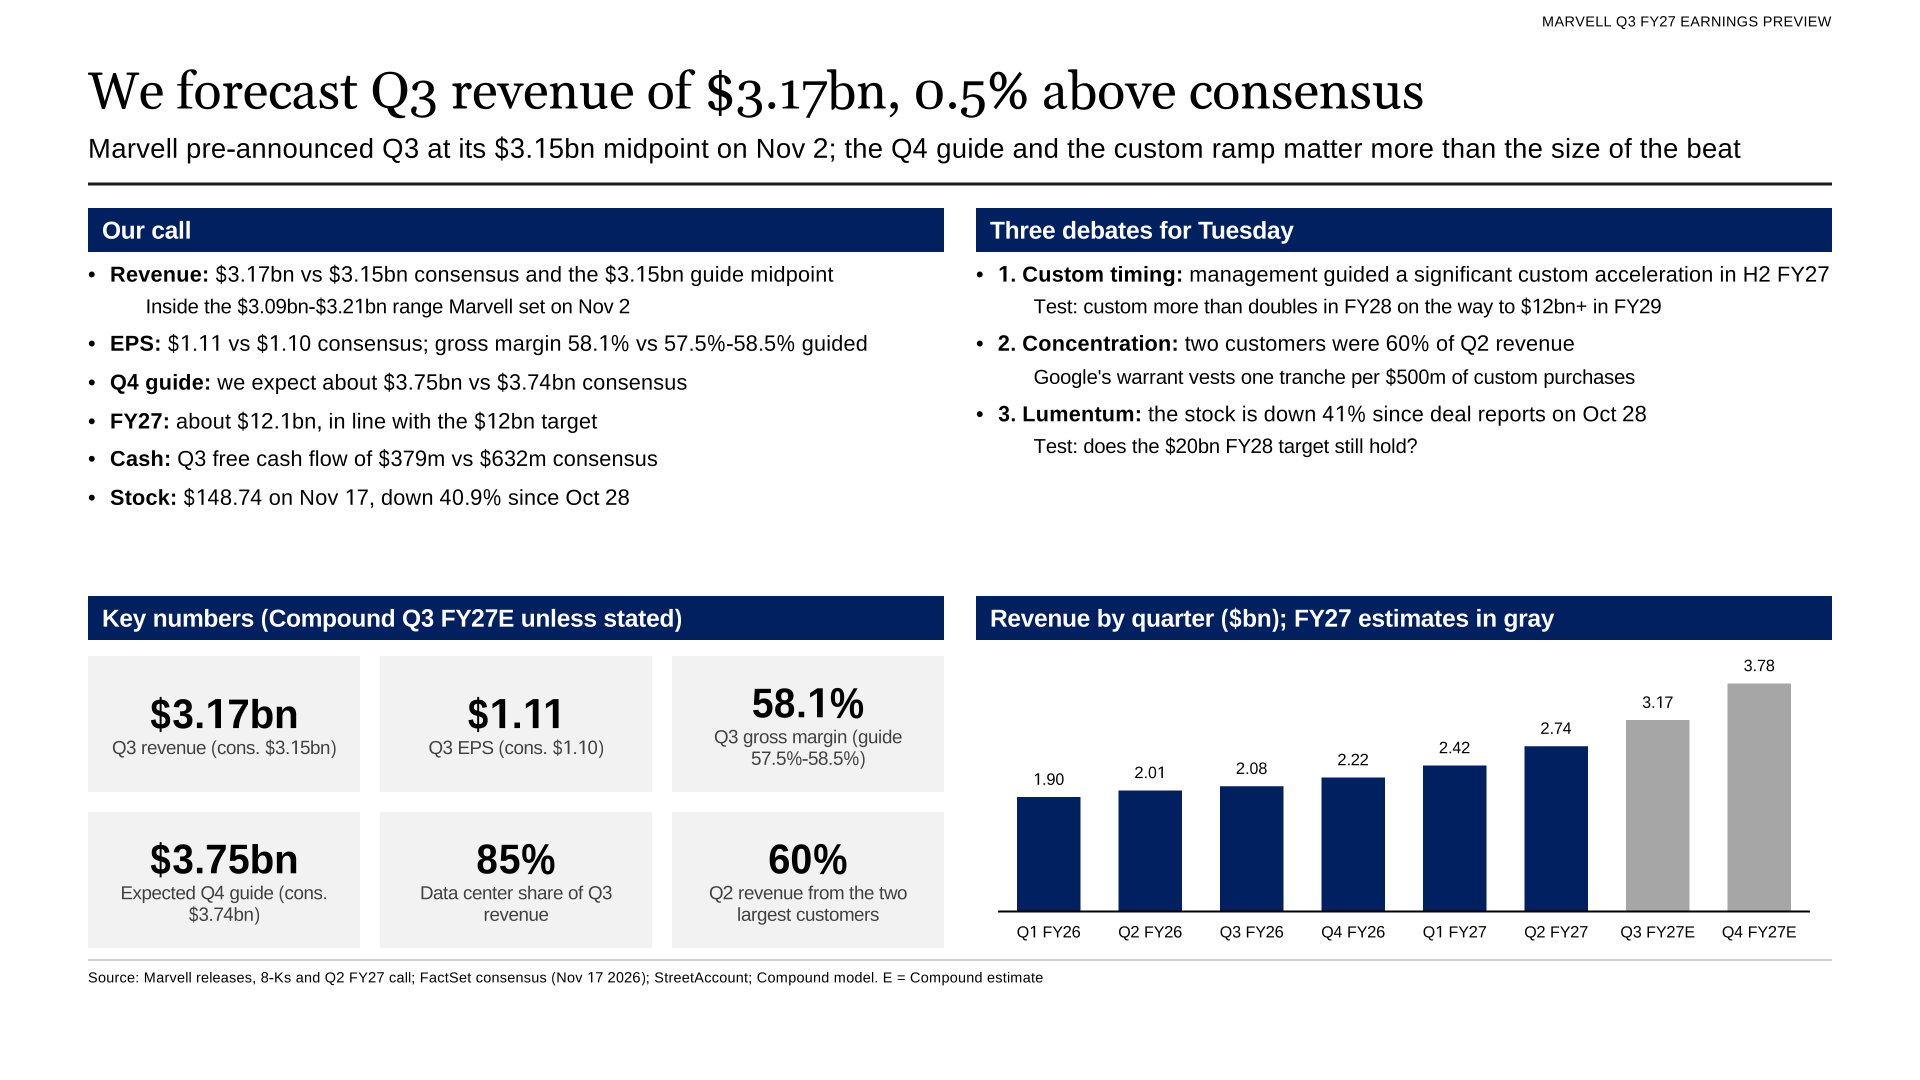
Executive summary: our call against consensus and the three debates for Tuesday.
Forecast vs consensus
| Q3 FY27 | Guidance | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Revenue ($M) | 3,150 | 3,154 | 3,170 | +0.5% |
| Data center ($M) | About 2,656 | n/a | 2,682 | n/a |
| Communications and other ($M) | About 494 | n/a | 488 | n/a |
| Non-GAAP gross margin | 57.5%-58.5% | 58.0% | 58.1% | +0.1 pt |
| Non-GAAP operating expenses ($M) | About 655 | n/a | 660 | n/a |
| Non-GAAP EPS ($) | 1.05-1.15 | 1.10 | 1.11 | +0.6% |
| GAAP EPS ($) | 0.48-0.58 | 0.56 | 0.53 | -4.2% |
| Free cash flow ($M) | n/a | 632 | 379 | -40.0% |
| Q4 revenue guide midpoint ($M) | n/a | 3,737 | 3,750 | +0.3% |
Consensus is the FactSet mean as of Nov. 17. StreetAccount has not yet published segment or margin consensus for the quarter, so the consensus gross margin is implied from FactSet's operating income consensus and Marvell's operating expense guidance. The data center and communications guidance figures are implied by management's growth rates.
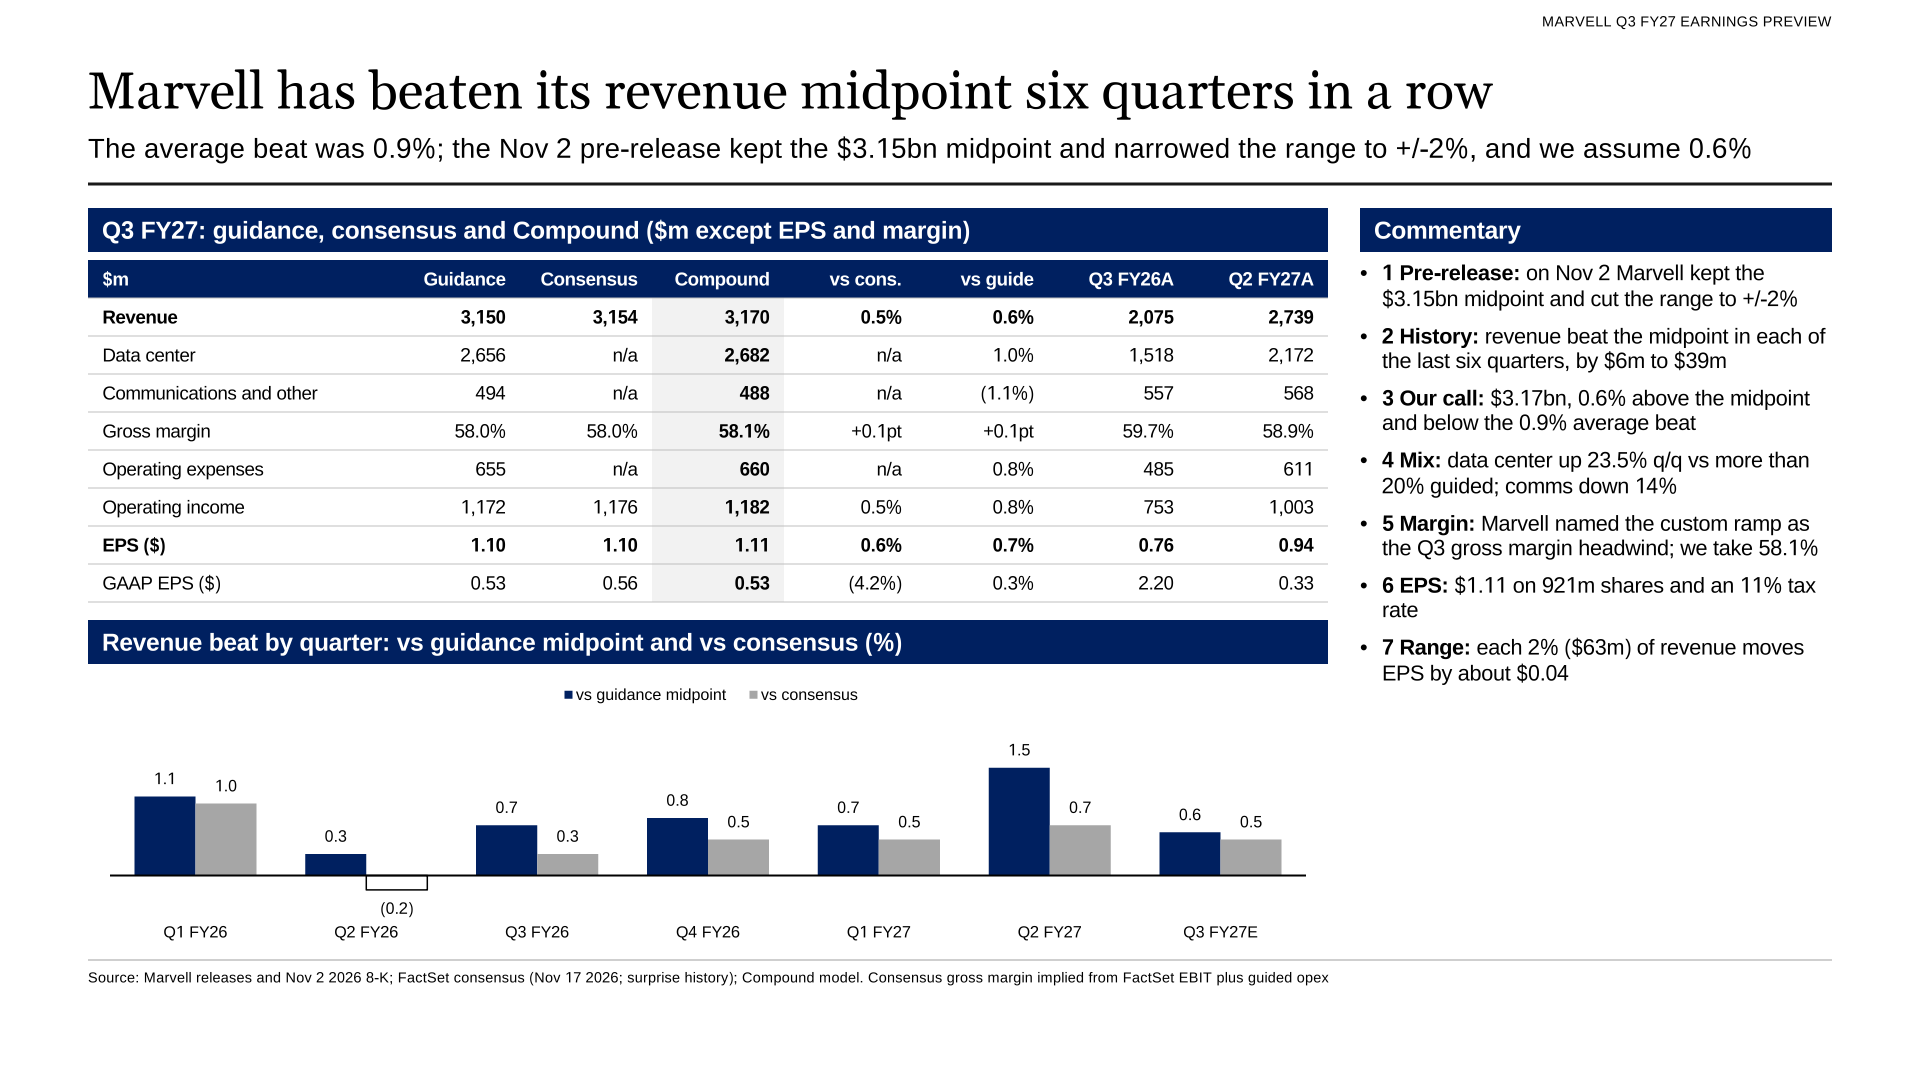
Marvell beat its revenue guidance midpoint in each of the last six quarters, by 0.3% to 1.5%; we assume 0.6%.
How we built the forecast
The model grows each end market from its second-quarter level. Data center grows 23.5% to $2.68 billion, after 18.5% in Q2. Marvell guided data center up more than 20% sequentially and about 75% year over year on its Aug. 27 call. Communications and other falls 14% to $488 million; management guided a low-to-mid-teens decline in Q3 and a sequential recovery in Q4.
Marvell beat its revenue midpoint by $6 million to $39 million in each of the last six quarters, an average of 0.9%. Our 0.6% sits below that average because the Nov. 2 update held the midpoint instead of raising it.
We put non-GAAP gross margin at 58.1%, against guidance of 57.5% to 58.5%. CFO Dan Durn said on the Aug. 27 call that the custom ramp is the sequential gross margin headwind in Q3 and that Q4 should stay in the same range. Operating expenses come in at $660 million, against guidance of about $655 million, with an 11% tax rate and 921 million diluted shares.
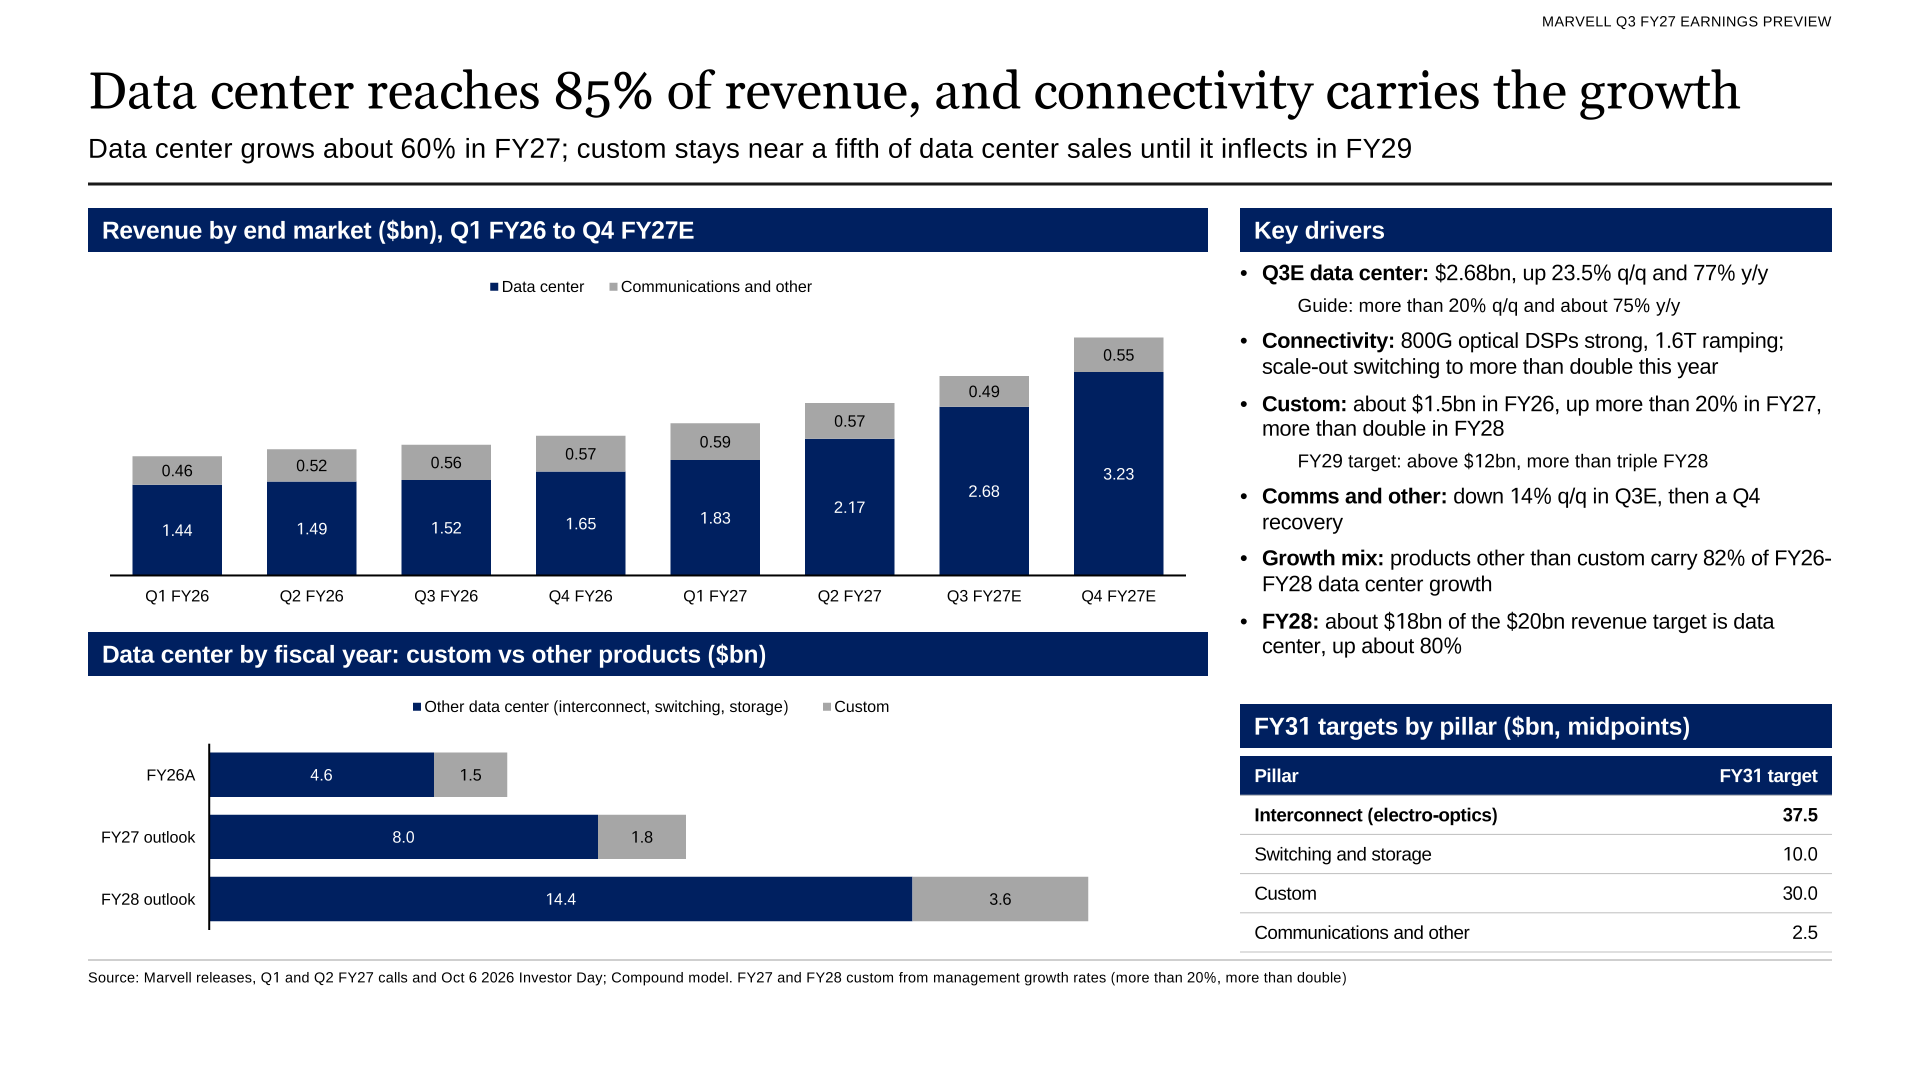
Data center is 85% of our Q3 estimate.
Custom silicon and electro-optics
Marvell does not report custom and connectivity revenue each quarter, so the split comes from management targets. Custom revenue was about $1.5 billion in fiscal 2026, out of $6.1 billion of data center revenue, CEO Matt Murphy said at the Oct. 6 Investor Day.
Marvell said in May that custom revenue would grow more than 20% in fiscal 2027, and in August that it would more than double in fiscal 2028. At Investor Day it raised the fiscal 2029 custom target to more than $12 billion, more than triple fiscal 2028.
Connectivity carries the growth until then. Murphy said in August that interconnect continues to lead, with 800G optical DSPs strong, 1.6T ramping and scale-out switching set to more than double this year. Marvell targets about $18 billion of data center revenue in fiscal 2028, out of about $20 billion in total. On those targets, products other than custom account for 82% of data center growth from fiscal 2026 to fiscal 2028.
For fiscal 2031, Marvell set a revenue range of $70 billion to $90 billion, with interconnect at about $37.5 billion and custom at about $30 billion at the midpoint, StreetAccount reported. The long-term model targets gross margin of 56% to 59% and operating margin of 44% to 46%.
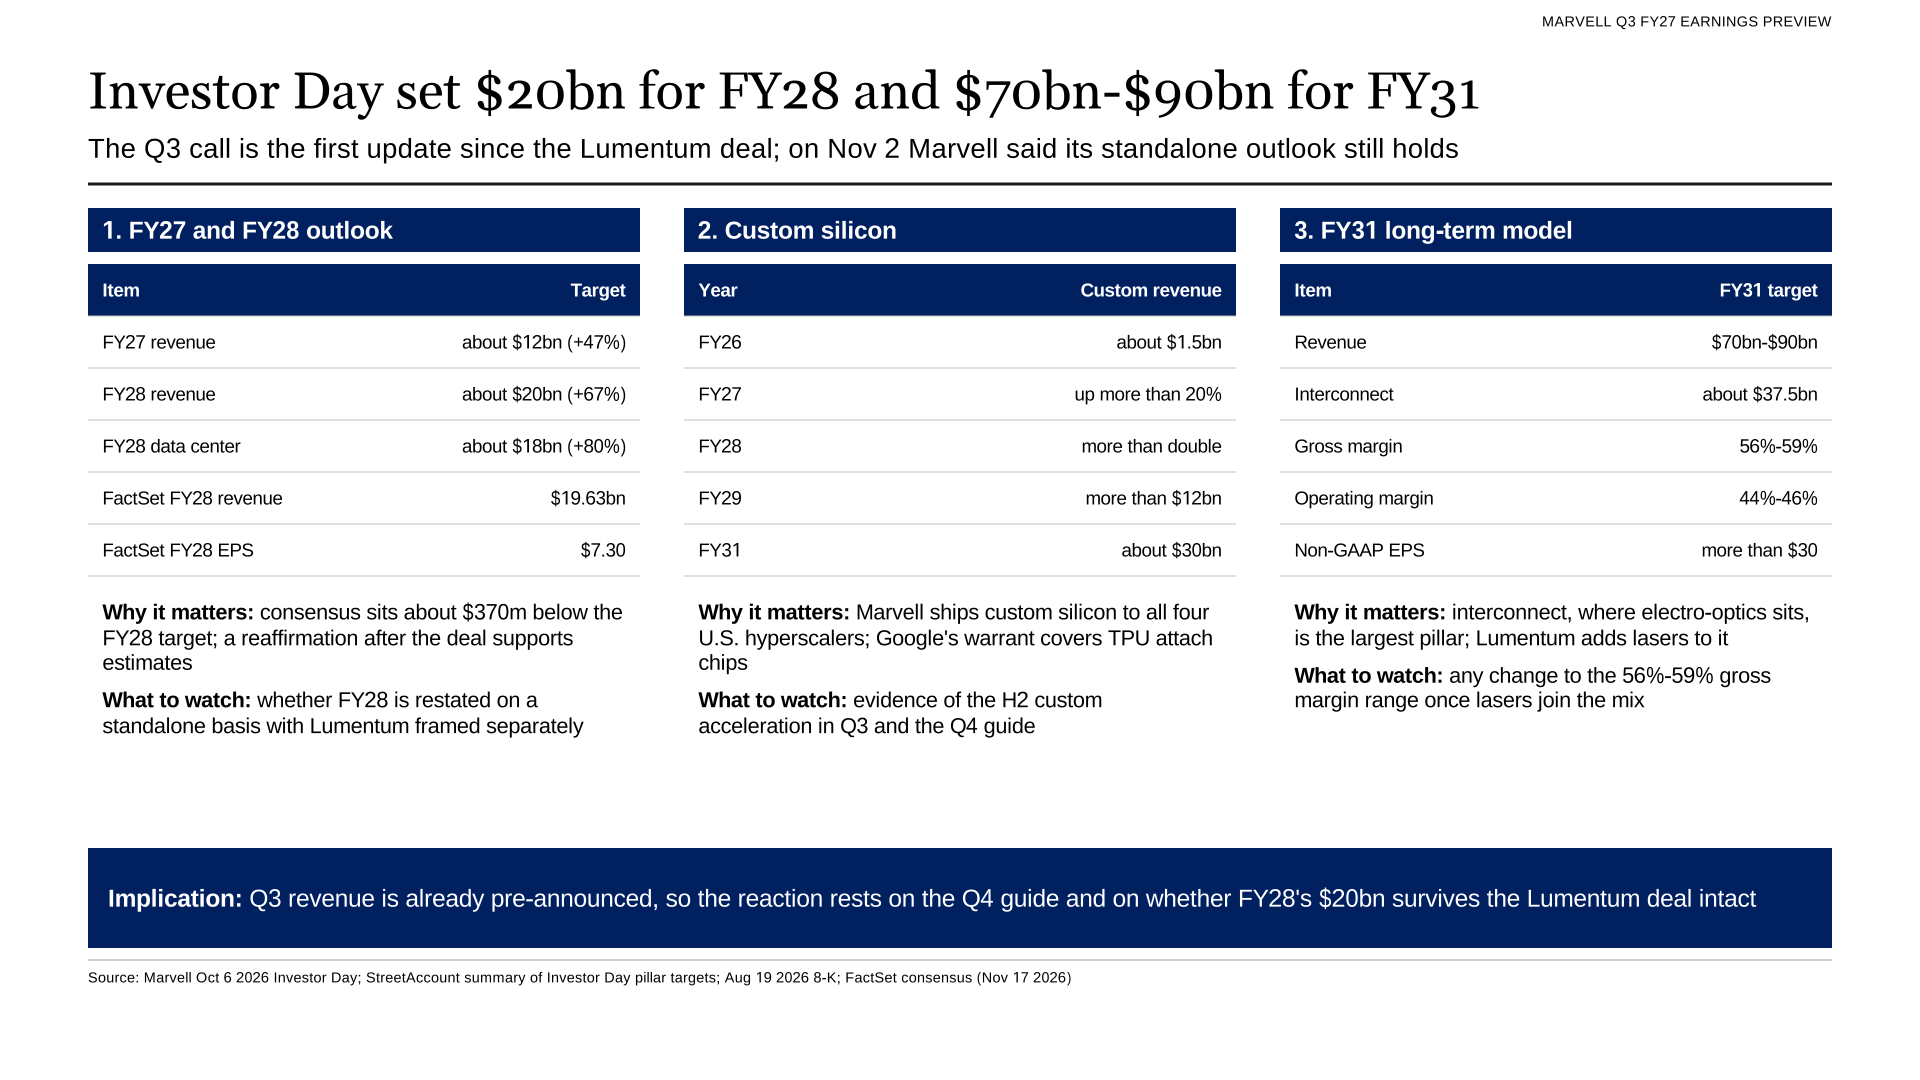
Investor Day targets for fiscal 2028, the custom business and fiscal 2031.
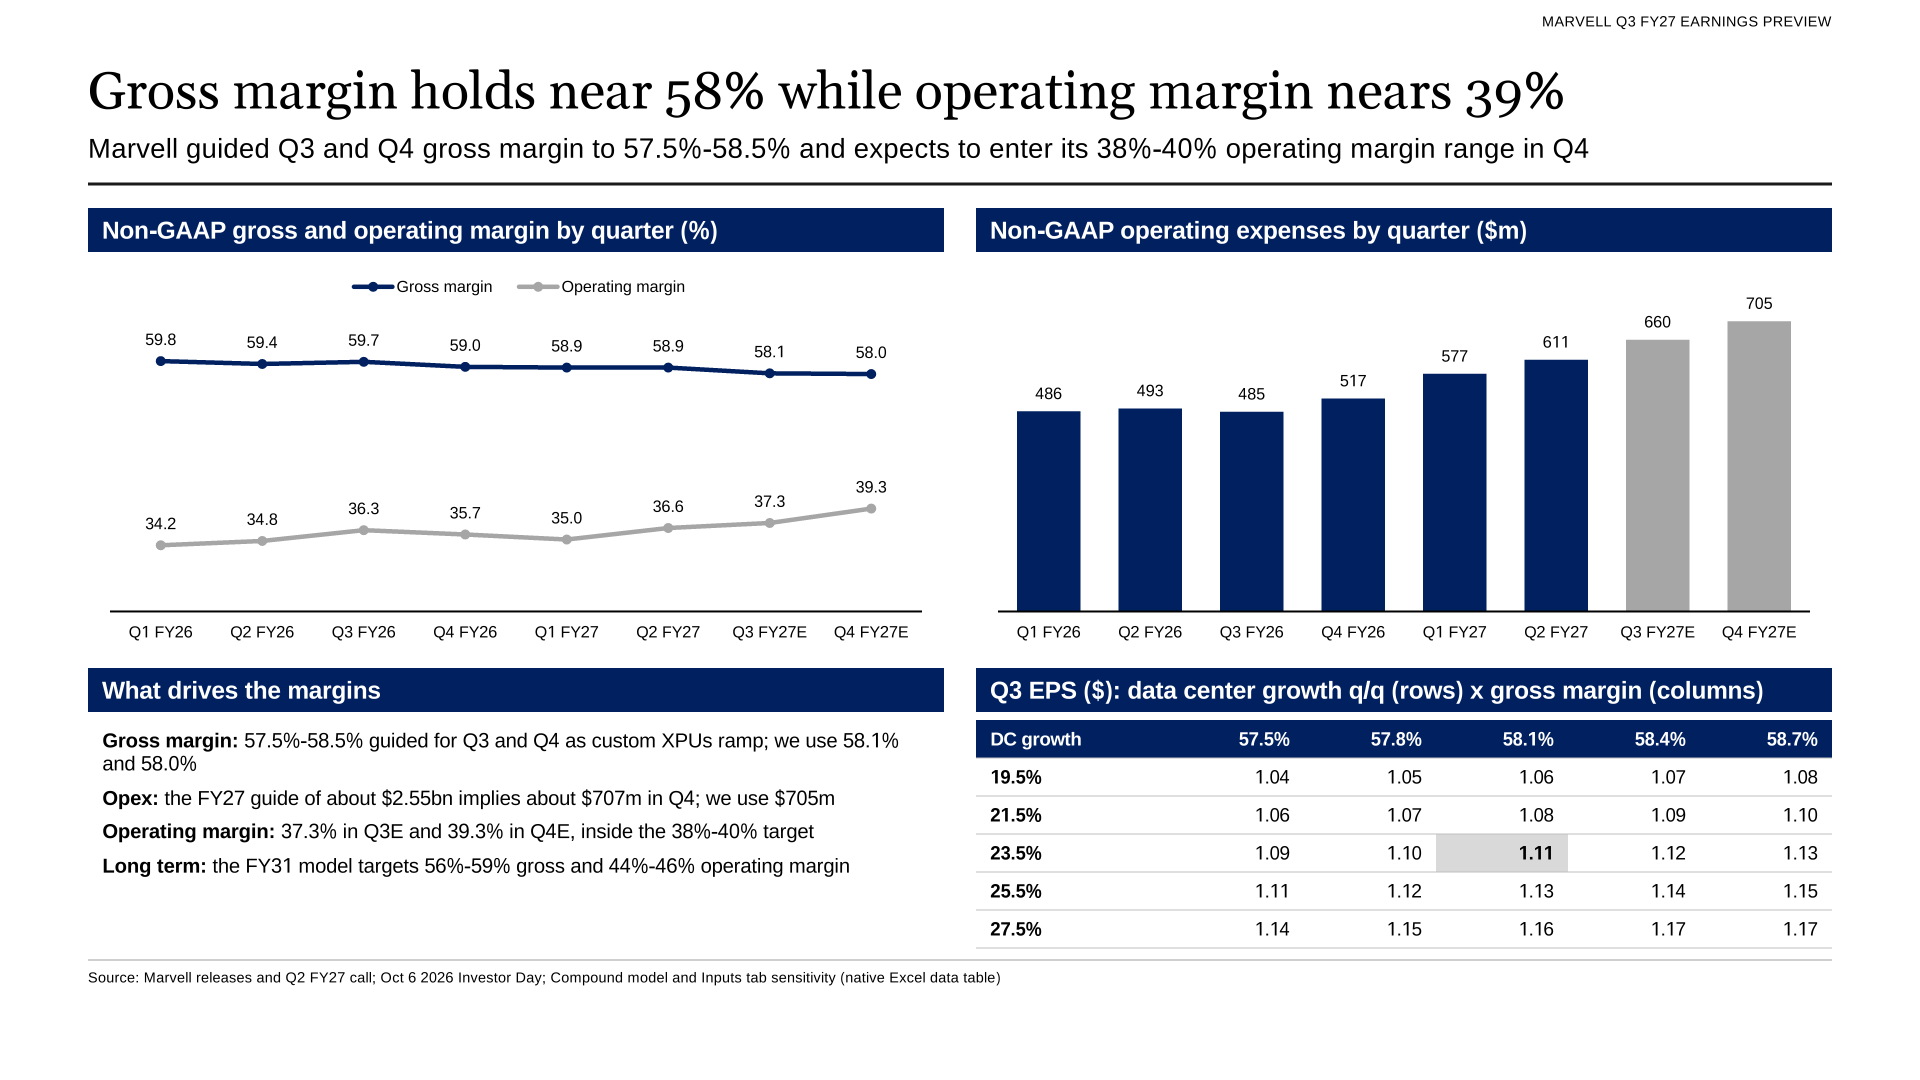
Gross margin holds near 58% while operating margin reaches 39.3% in our Q4 estimate.
Customer concentration
Two customers accounted for 60% of Marvell's Q2 revenue, according to its 10-Q: a distributor at 44% and a direct customer at 16%. A year earlier the pair accounted for 50%. The ten largest customers were 82% of fiscal 2026 revenue, according to the 10-Q.
On Aug. 18 Marvell issued Google a warrant for up to 58,970,907 shares at $206.58 each, according to an Aug. 19 8-K. Most of the shares vest in 240 tranches, one for each $500 million of Google custom product revenue between the third quarter of fiscal 2027 and the end of fiscal 2033, or $120 billion in total. The programs attach to Google's TPU ecosystem and include inference accelerators, storage controllers and network interface controllers.
Nvidia bought $2.0 billion of Marvell convertible preferred stock on March 31, convertible into about 21.8 million shares, according to the 10-Q. Marvell books customer warrants as a reduction to revenue as they vest.
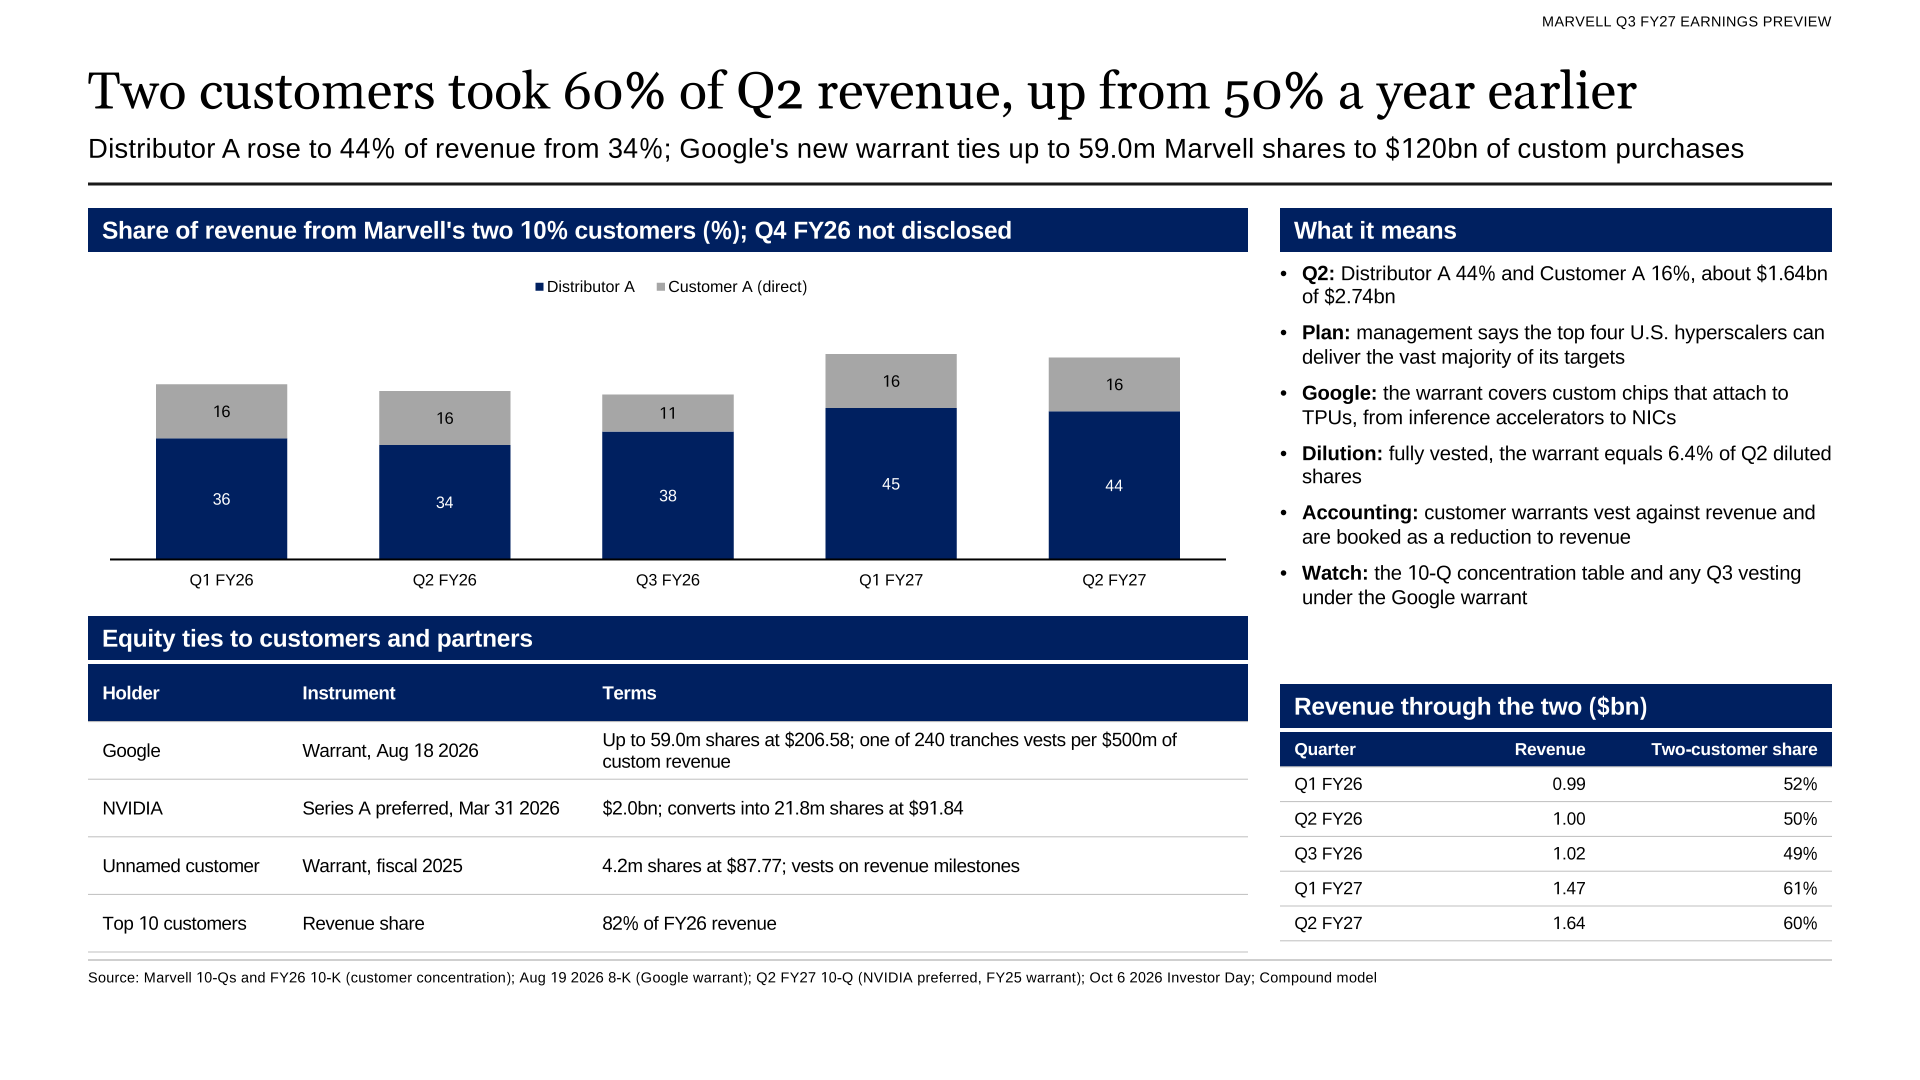
Two customers took 60% of Q2 revenue.
Q4 guidance
FactSet consensus for fourth-quarter revenue is $3.737 billion. Marvell's next-quarter guide rose from 2.7% above the revenue it had just reported in fiscal Q2 2026 to 15.0% in fiscal Q2 2027. We apply 18.3% to our Q3 estimate, which gives a guidance midpoint of about $3.75 billion, in line with consensus.
Murphy said at Investor Day that fiscal 2027 revenue should be about $12 billion, up about 47%. With Q3 at the $3.15 billion midpoint, that implies Q4 revenue near $3.74 billion. Our Q4 guide puts fiscal 2027 at $12.08 billion.
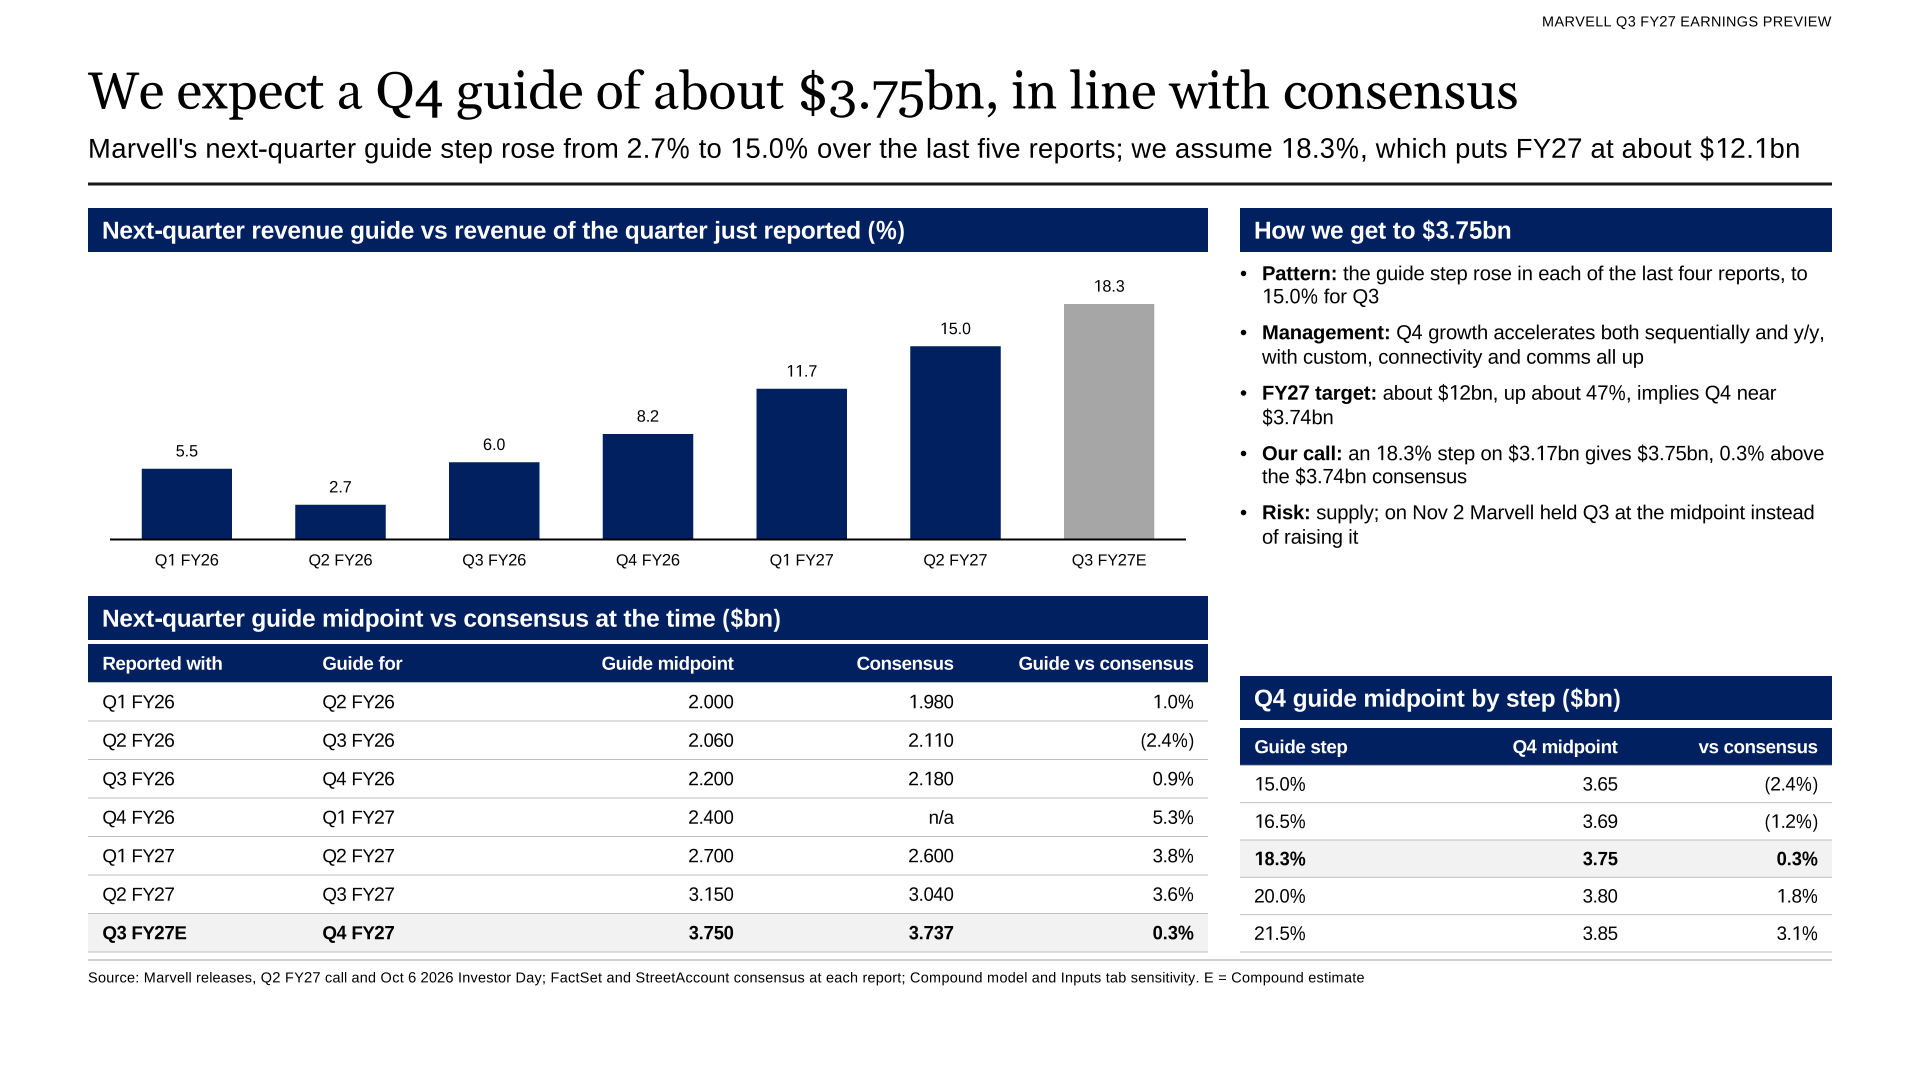
Each 1.5-point change in the guide step moves the Q4 midpoint by about $50 million.
The Lumentum deal and the share price
On Nov. 2 Marvell agreed to buy Lumentum for 4.5 Marvell shares per Lumentum share, an implied enterprise value of about $115 billion and a 23.9% premium to Lumentum's Oct. 28 close, according to the companies' release. Lumentum holders would own about 33% of the combined company. The companies expect more than $1 billion of annual run-rate cost synergies and a close in the first half of calendar 2028.
BofA downgraded Marvell to neutral and cut its target to $225 from $400 on Nov. 2, and TD Cowen moved to hold with a $175 target on Nov. 3, StreetAccount reported. Marvell fell 16.4% on Nov. 5; StreetAccount tied that week's declines in data center and networking stocks to the midterm election results.
Marvell said on Nov. 2 that its standalone outlook from Investor Day still holds, StreetAccount reported. FactSet consensus for fiscal 2028 revenue is $19.63 billion, below the $20 billion target.
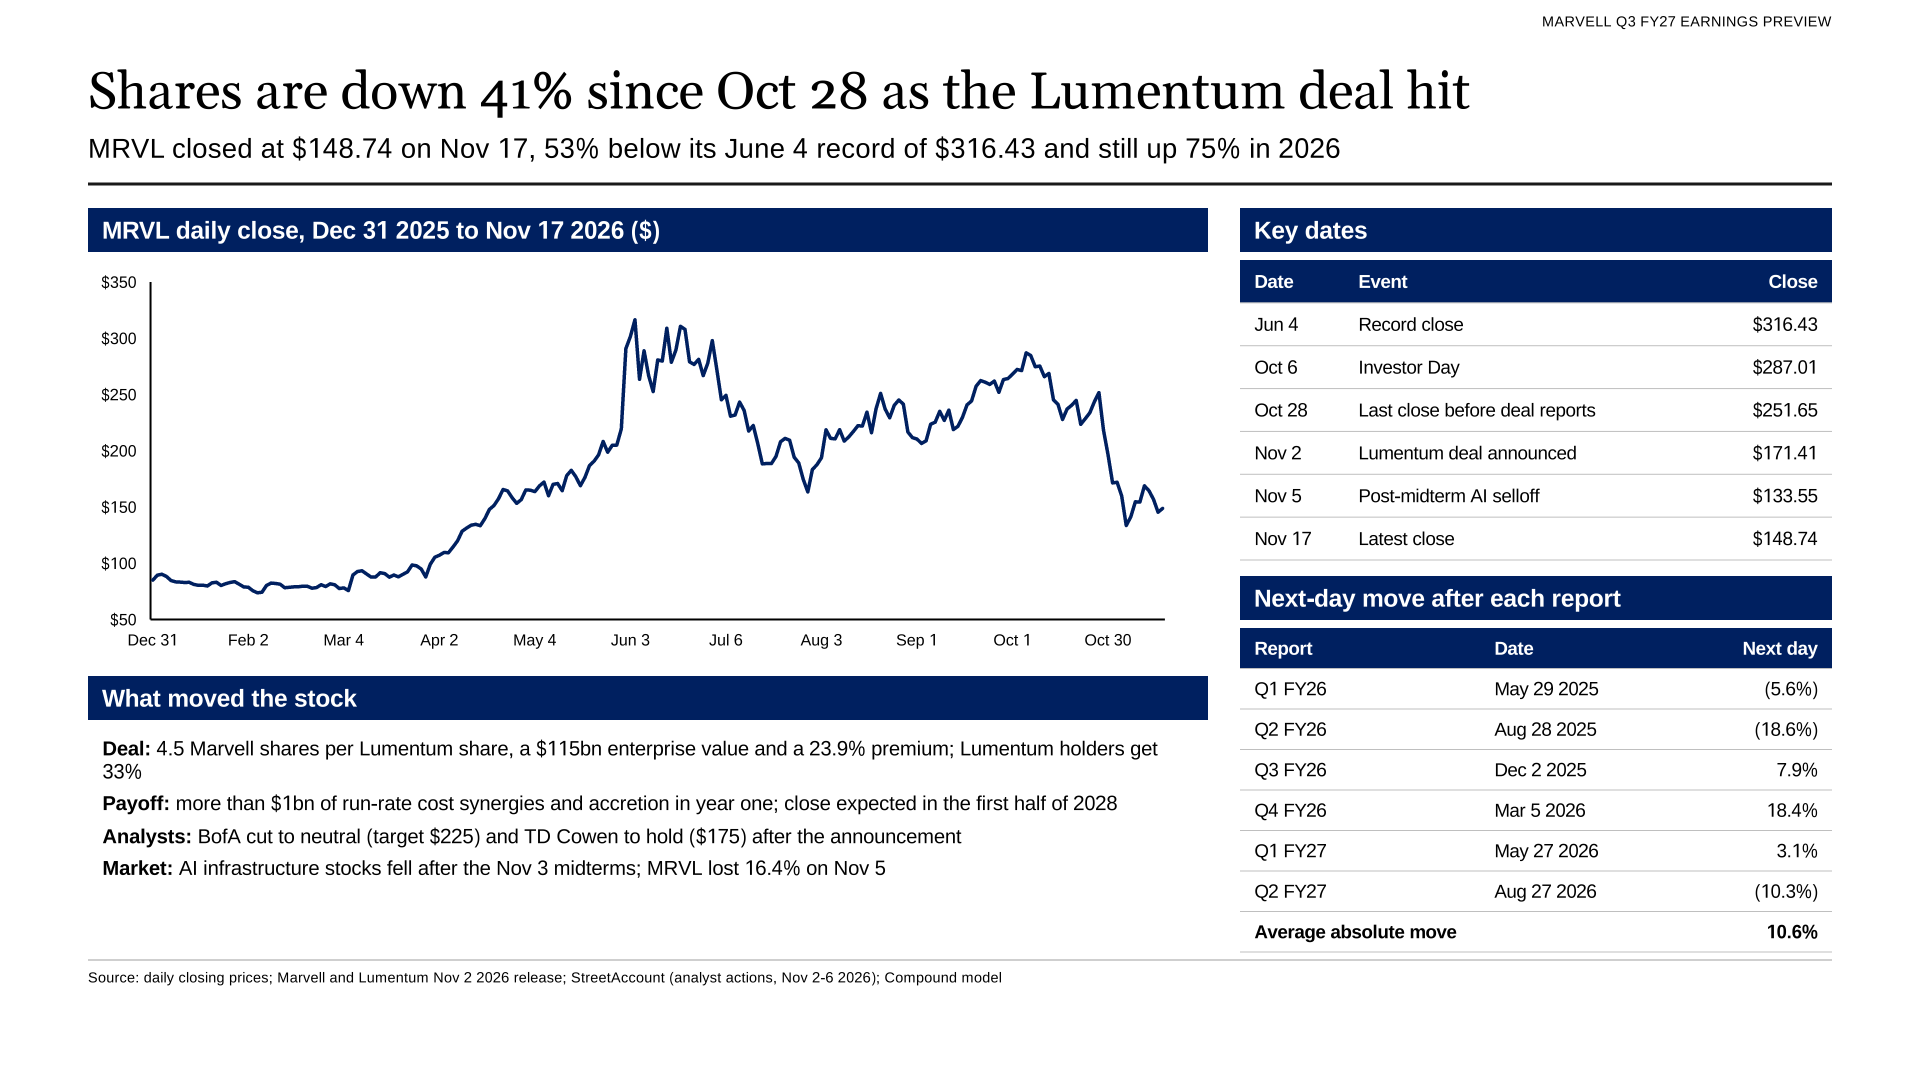
Marvell shares since Dec. 31, with the deal dates and the next-day move after each report.
Cash flow
We forecast Q3 free cash flow of $379 million against a FactSet consensus of $632 million. Receivables grow with revenue: at 72 days of sales, a 16% revenue increase adds about $290 million. Durn said in August that Marvell plans about $1 billion of capacity prepayments to suppliers in fiscal 2027, and its Q2 10-Q tied the first-half rise in prepaid expenses to capacity fees.
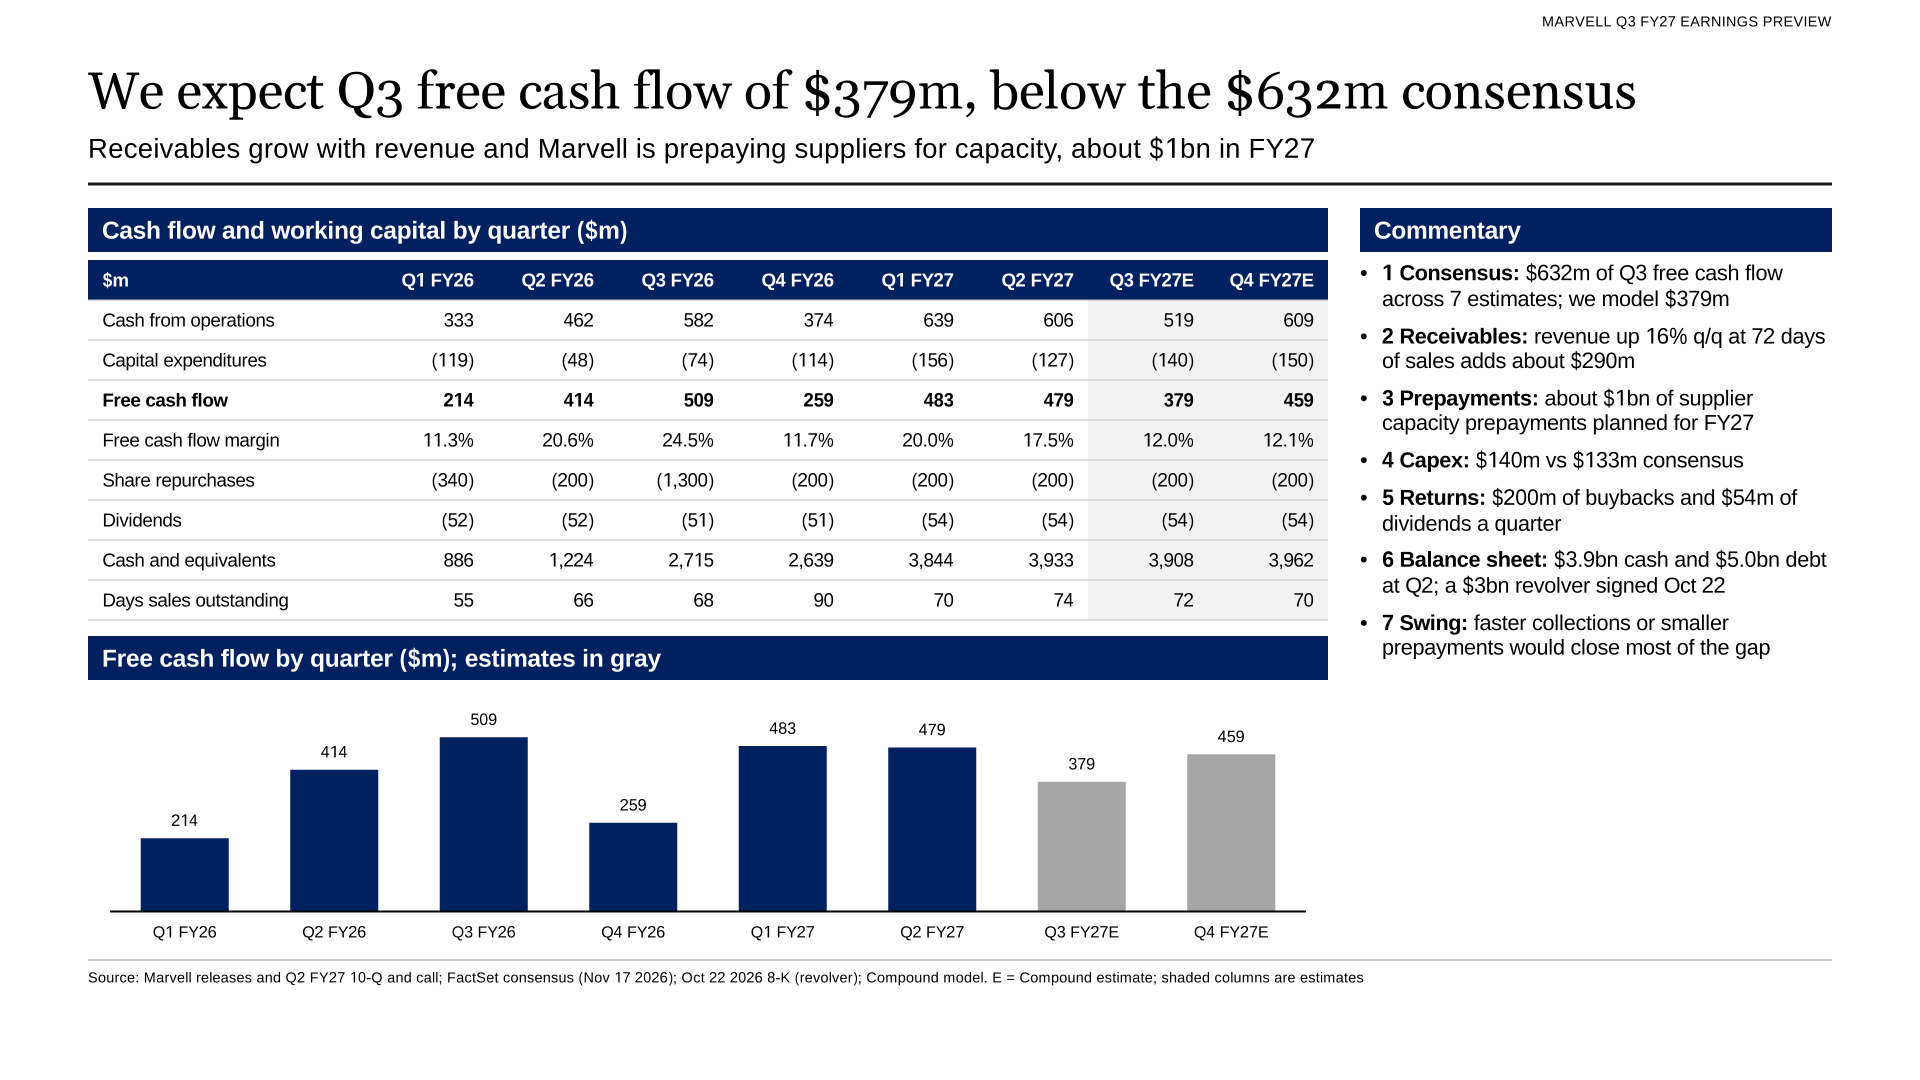
Working capital and supplier prepayments are why our free cash flow sits below consensus.
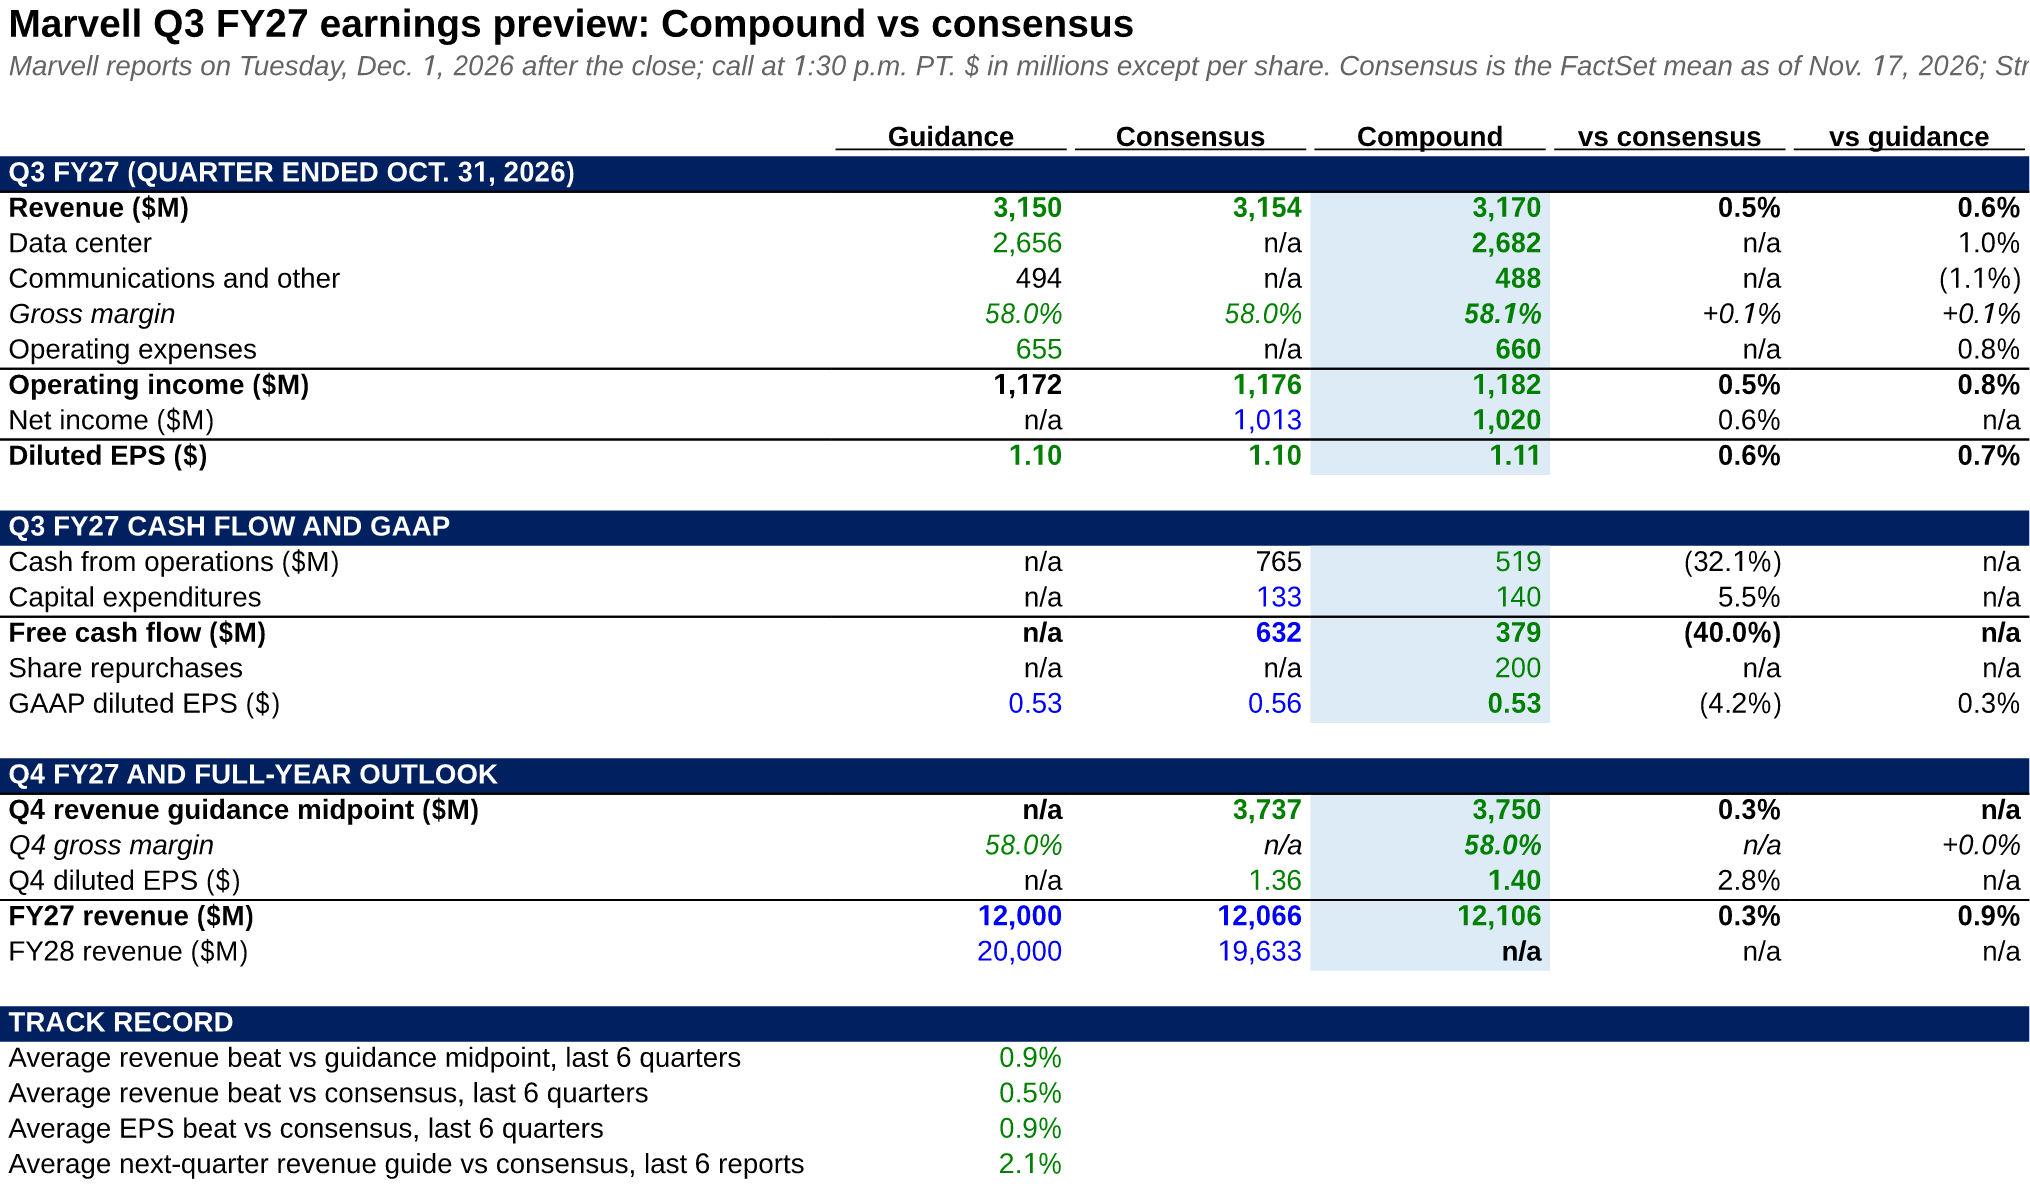
The Preview tab of the Excel model, which links every estimate to its drivers.
What to watch on Tuesday
- The Q4 revenue guide against the $3.737 billion consensus and our $3.75 billion.
- Q4 gross margin guidance; management expects the same 57.5% to 58.5% range as Q3.
- Whether Marvell reaffirms the $20 billion fiscal 2028 target after the Lumentum agreement.
- Evidence of the second-half custom ramp, including any vesting under the Google warrant.
- The customer concentration table in the Q3 10-Q.
- Any update on Lumentum approvals and synergy timing.
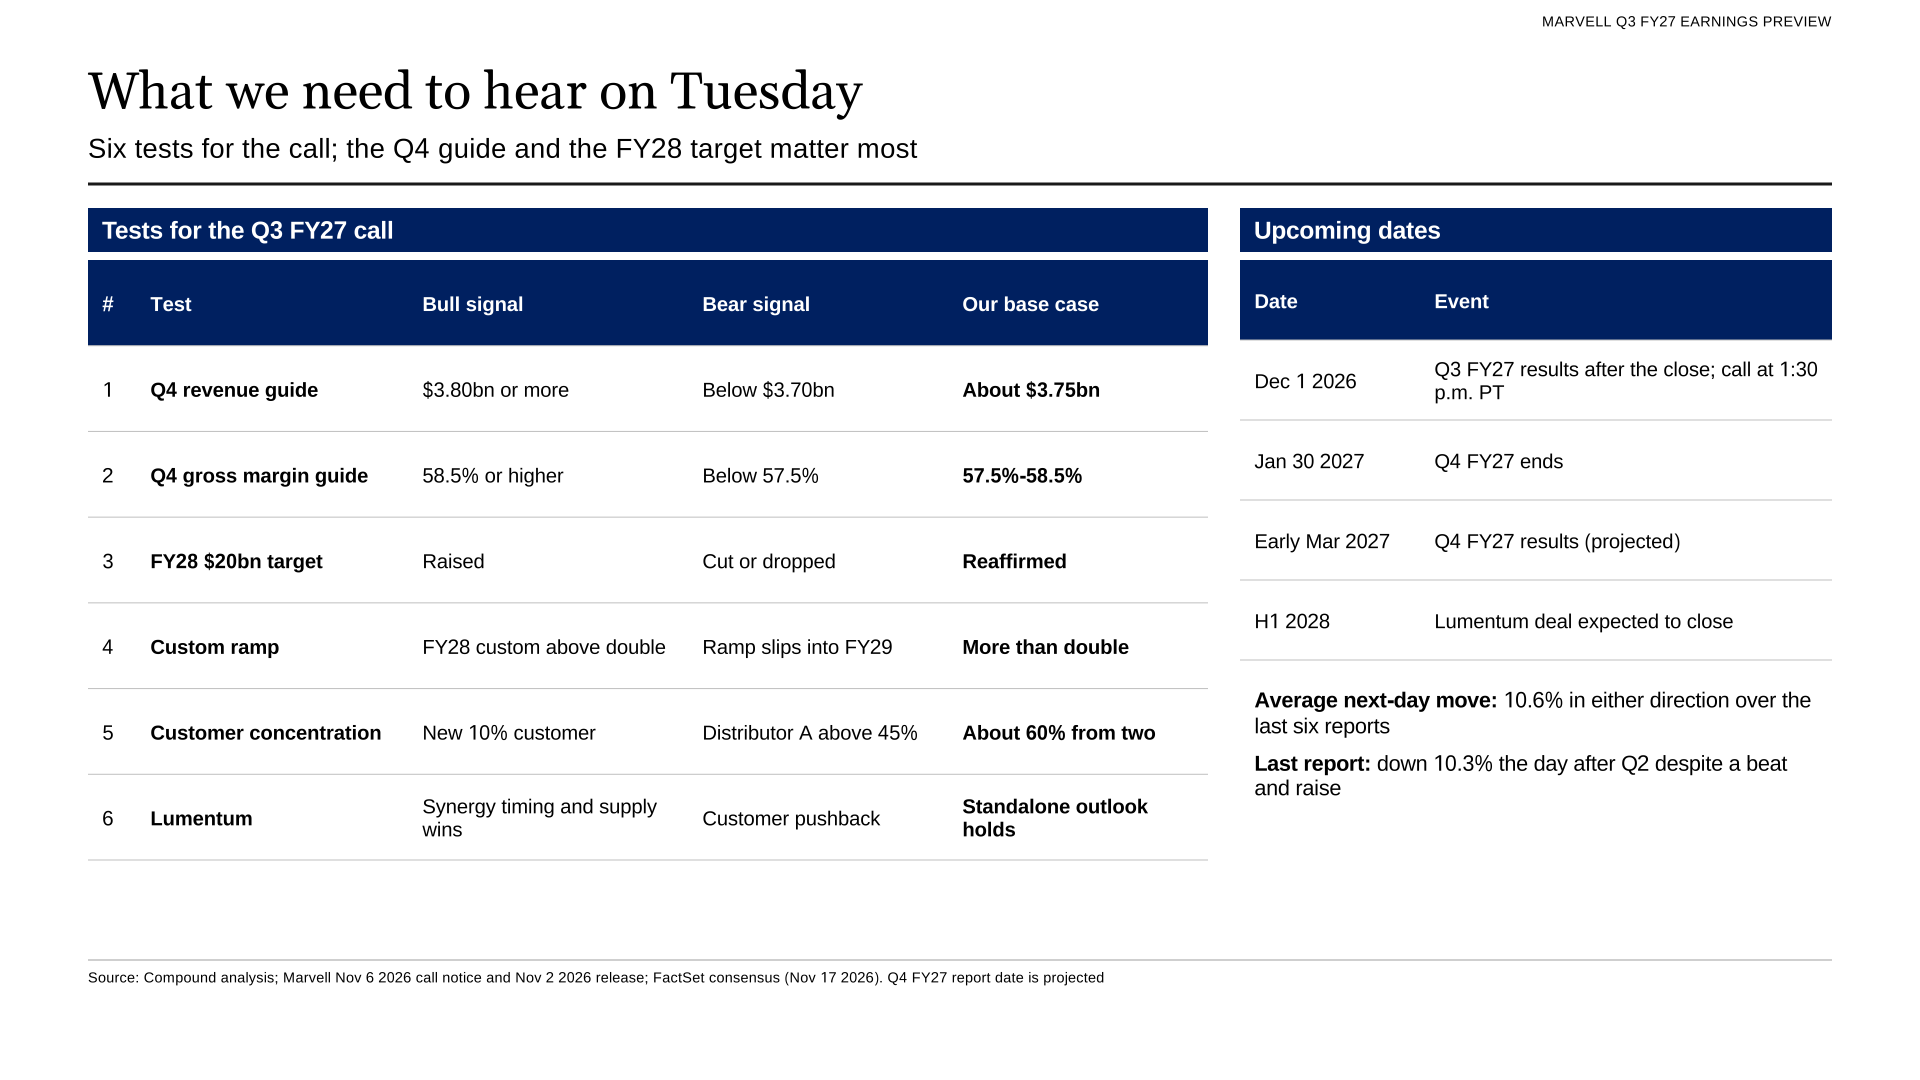
Six tests for the call, with what would support the bull and bear cases.
Marvell shares moved 10.6% on average, in either direction, the day after each of the last six reports, and fell 10.3% the day after the Q2 report on Aug. 27. The fourth quarter ends Jan. 30, 2027. We will score this forecast against the reported numbers after the Dec. 1 release.
 Marvell Q3 FY27 earnings preview deck (PowerPoint)The 11-page preview: executive summary, forecast against consensus, revenue build, margins, Q4 guidance, customer concentration, the share price and the Lumentum deal, cash flow, Investor Day targets and the checklist for the call, with editable charts and tables.Download · Free
 Marvell Q3 FY27 earnings model (Excel)Quarterly model from Q1 FY26: end-market build, non-GAAP and GAAP income statements, cash flow, balance sheet and working capital, guidance and consensus track record, Compound's Q3 and Q4 estimates, native Excel sensitivity tables, and a custom silicon, customer concentration and Lumentum tab, with formulas and sources.Download · Free
More from Compound News
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Read article →
Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Read article →
CrowdStrike Q3 Earnings Preview: $0.33 EPS vs $0.31 Consensus
CrowdStrike reports Tuesday after the close. Our model puts net new ARR 9% above guidance, revenue 2.0% above consensus at $1.56 billion and EPS at $0.33 against $0.31.
Read article →