Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Salesforce reports fiscal third-quarter results on Wednesday, Dec. 2, after the market close, with a webcast at 2 p.m. PT, the company said on Nov. 10. The quarter ended Oct. 31.
Compound's model forecasts revenue of $11.50 billion, at the top of Salesforce's $11.42 billion to $11.50 billion guidance and 0.3% above the FactSet consensus of $11.46 billion. We forecast non-GAAP EPS of $3.51 against a consensus of $3.45 and guidance of $3.42 to $3.44.
The shares closed at $194.52 on Nov. 17, down 9.5% on the day and 26.6% since the end of 2025. Benzinga reported that software stocks fell ahead of Anthropic's IPO, which is expected to price on Wednesday, Nov. 18; Yahoo Finance said Salesforce had no news of its own. Salesforce's stake in Anthropic was carried at about $5.1 billion on July 31, according to its second-quarter 10-Q.
We built an 11-page earnings preview deck on the model, in the format of our Nike Investor Day memo. The slides below come from it, and the deck and the Excel model are free to download at the end.
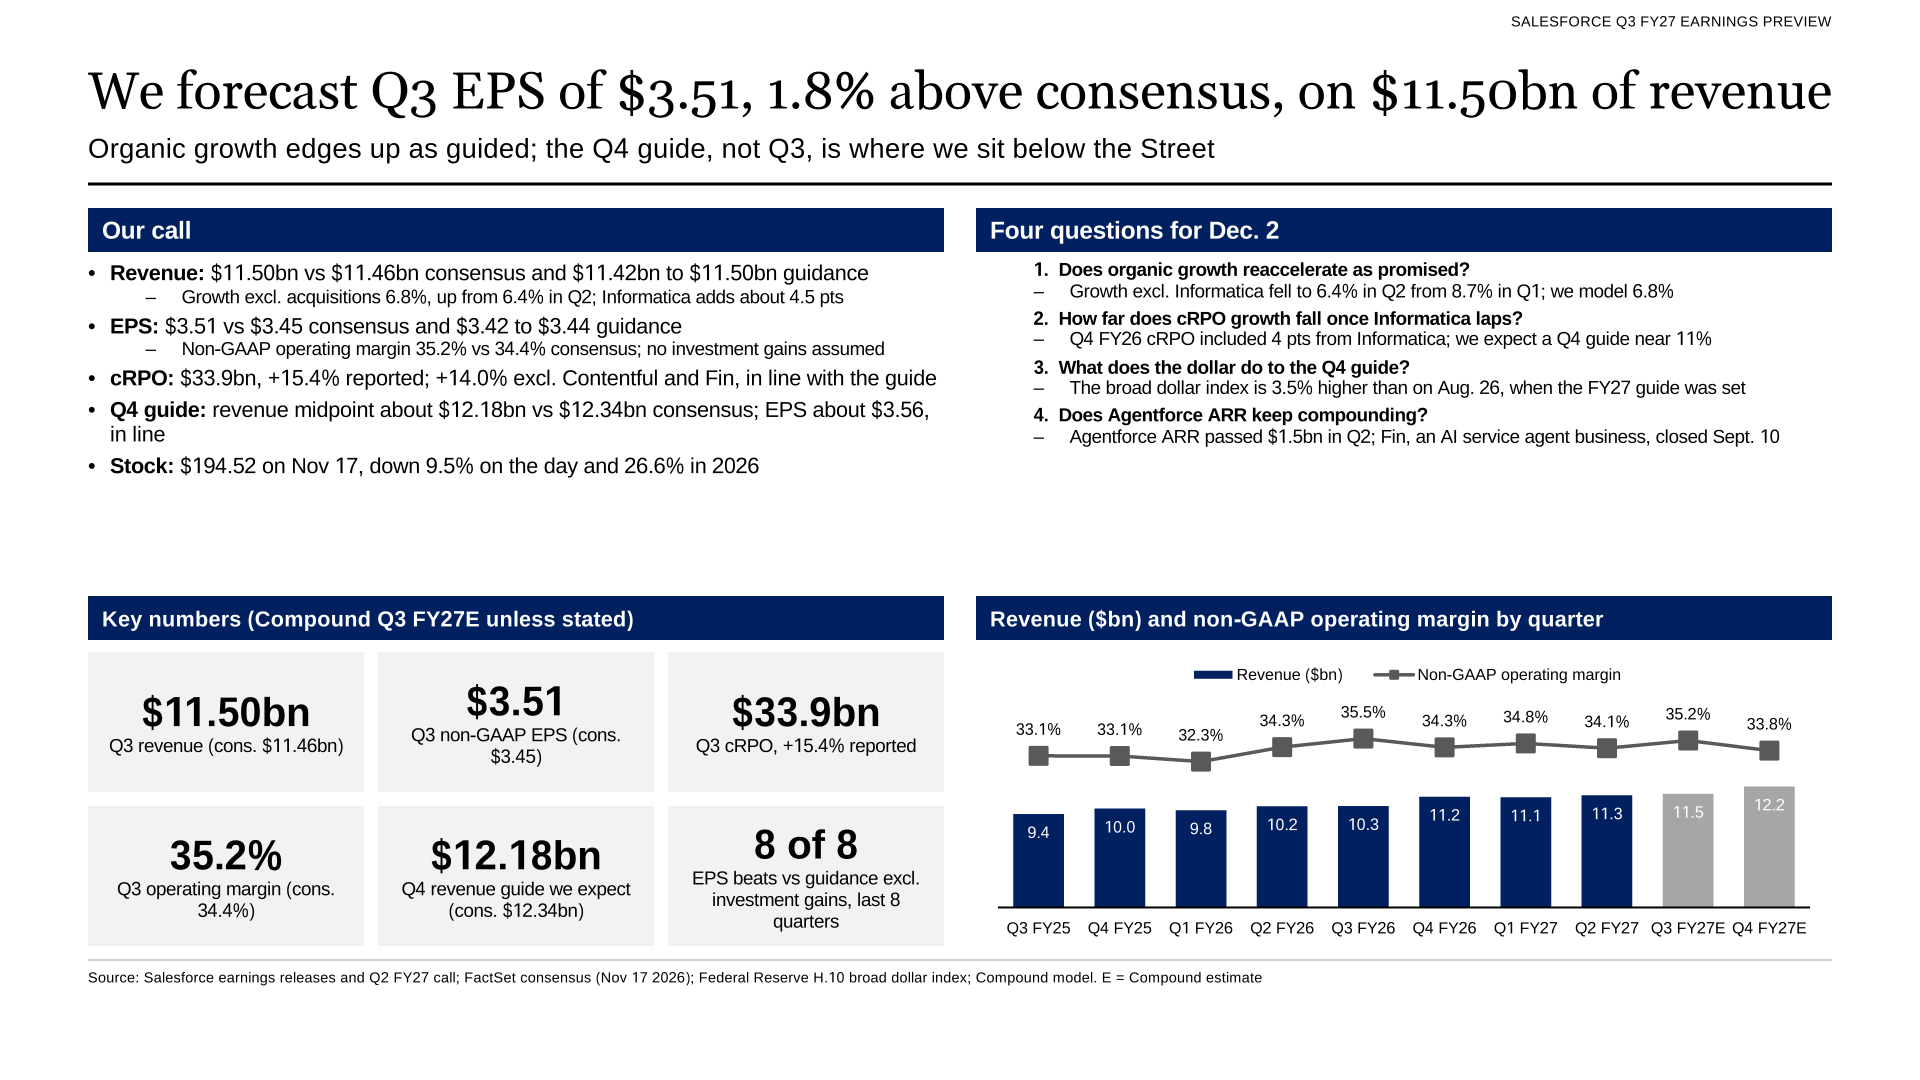
Executive summary: our call against consensus and four questions for Dec. 2.
Forecast vs consensus
| Q3 FY27 | Guidance | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Revenue | $11.42B to $11.50B | $11.46B | $11.50B | +0.3% |
| Subscription and support | n/a | n/a | $10.98B | n/a |
| Growth excl. acquisitions | n/a | n/a | 6.8% | n/a |
| cRPO growth excl. Contentful and Fin | About 14% | n/a | 14.0% | n/a |
| cRPO, as reported | n/a | n/a | $33.9B | n/a |
| Non-GAAP operating margin | n/a | 34.4% | 35.2% | +0.8 pt |
| Non-GAAP EPS | $3.42 to $3.44 | $3.45 | $3.51 | +1.8% |
| GAAP EPS | $1.81 to $1.83 | n/a | $1.89 | n/a |
| Q4 revenue guide midpoint | n/a | $12.34B | $12.18B | -1.3% |
Consensus is the FactSet mean as of Nov. 17. Salesforce's reported non-GAAP EPS includes gains and losses on strategic investments; guidance and our estimate assume none. Acquisitions are Informatica, Contentful and Fin.
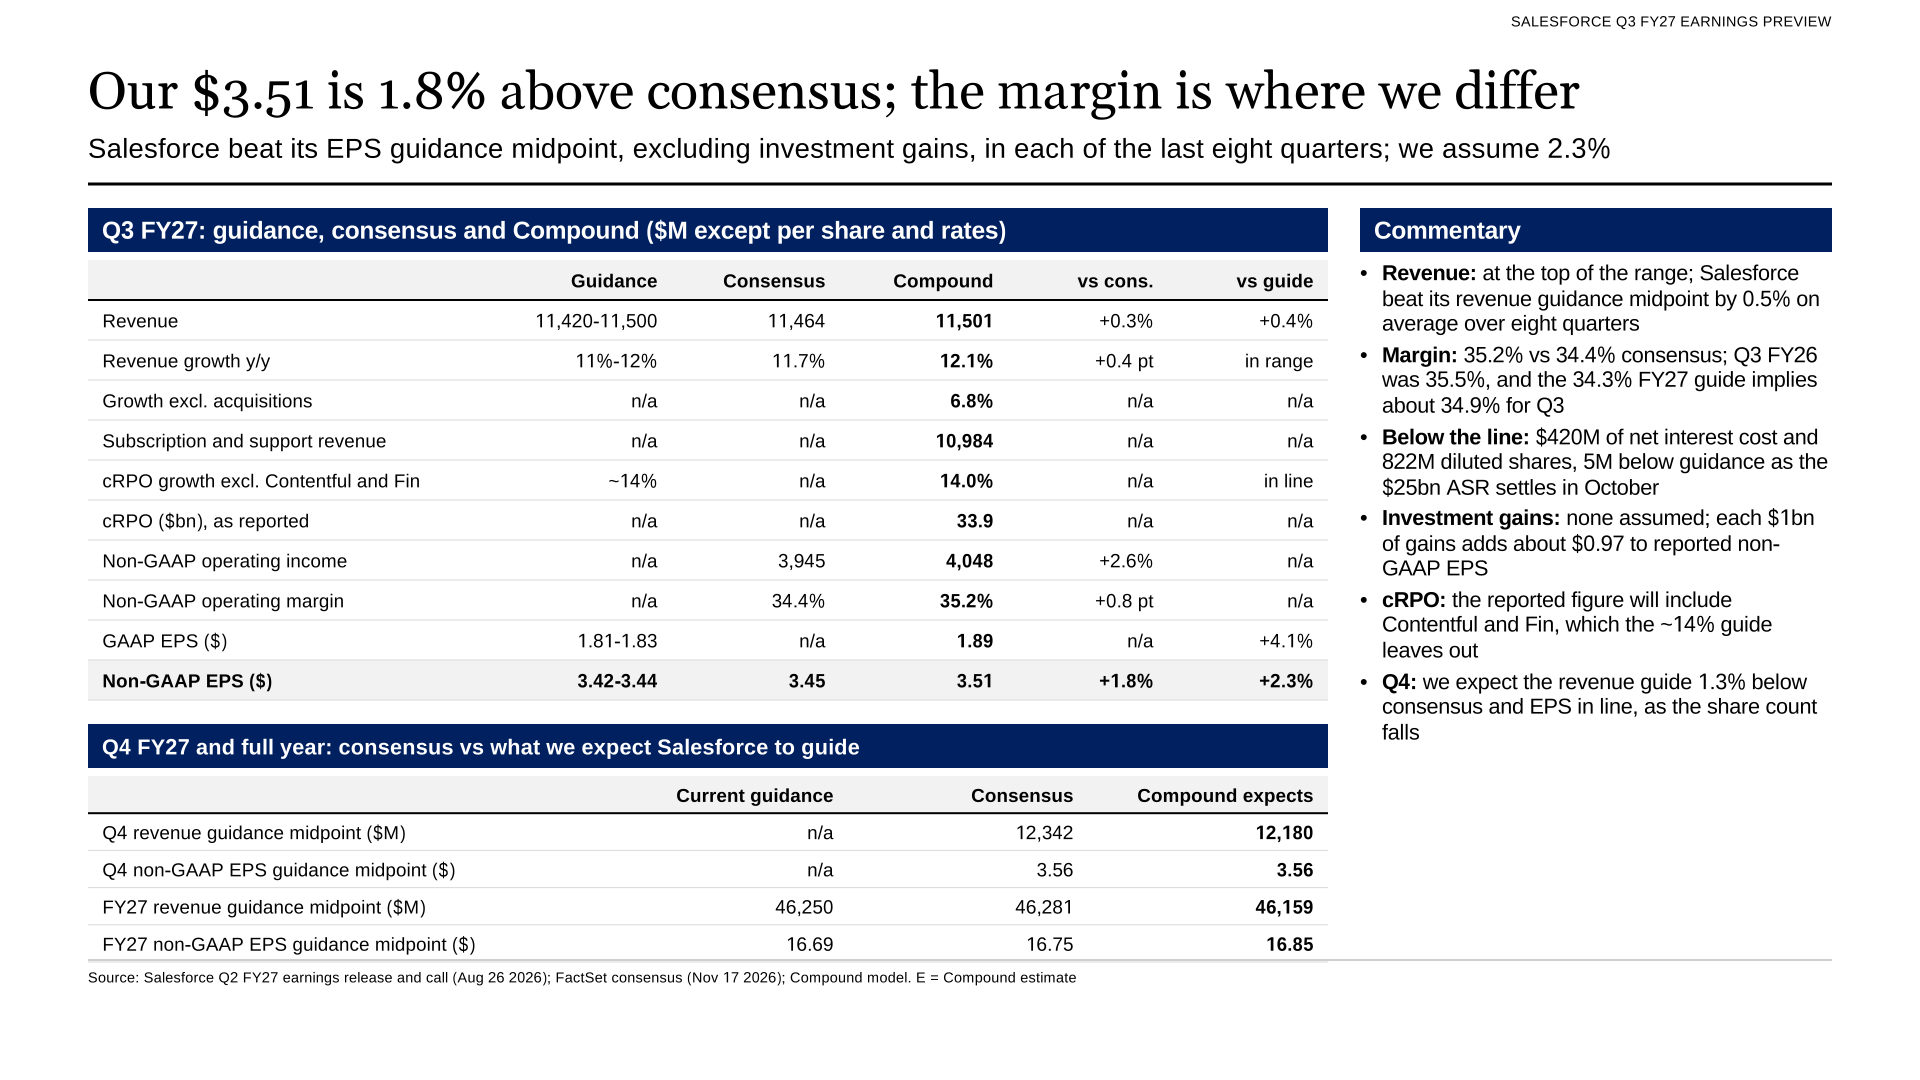
Guidance, consensus and our estimates for Q3, Q4 and fiscal 2027.
How we built the forecast
Salesforce changed how it reports subscription revenue in the first quarter of fiscal 2027, into Agentforce Apps and a Data 360, Headless Platform and Other group that includes Informatica. In the second quarter, Agentforce Apps grew 7.6% to $7.19 billion and the second group grew 20.3% to $3.62 billion, most of it from Informatica.
Informatica, bought in November 2025, contributed $456 million of second-quarter revenue. Excluding it, revenue grew 6.4%, down from 8.7% in the first quarter, a slowdown DA Davidson's Gil Luria pointed to after the report, StreetAccount reported. Salesforce has promised organic reacceleration in the second half, and President and COO Miguel Milano said on the August call that "Q3 is math."
We grow Agentforce Apps 1.6% from the second quarter and take the Data 360 group excluding Informatica 1.0% lower, close to last year's seasonal pattern on the old cloud split. Informatica adds $466 million and the newly closed Contentful and Fin $80 million. That puts revenue growth excluding acquisitions at 6.8%. Salesforce beat its revenue guidance midpoint by 0.5% on average over the past eight quarters; we are 0.4% above it.
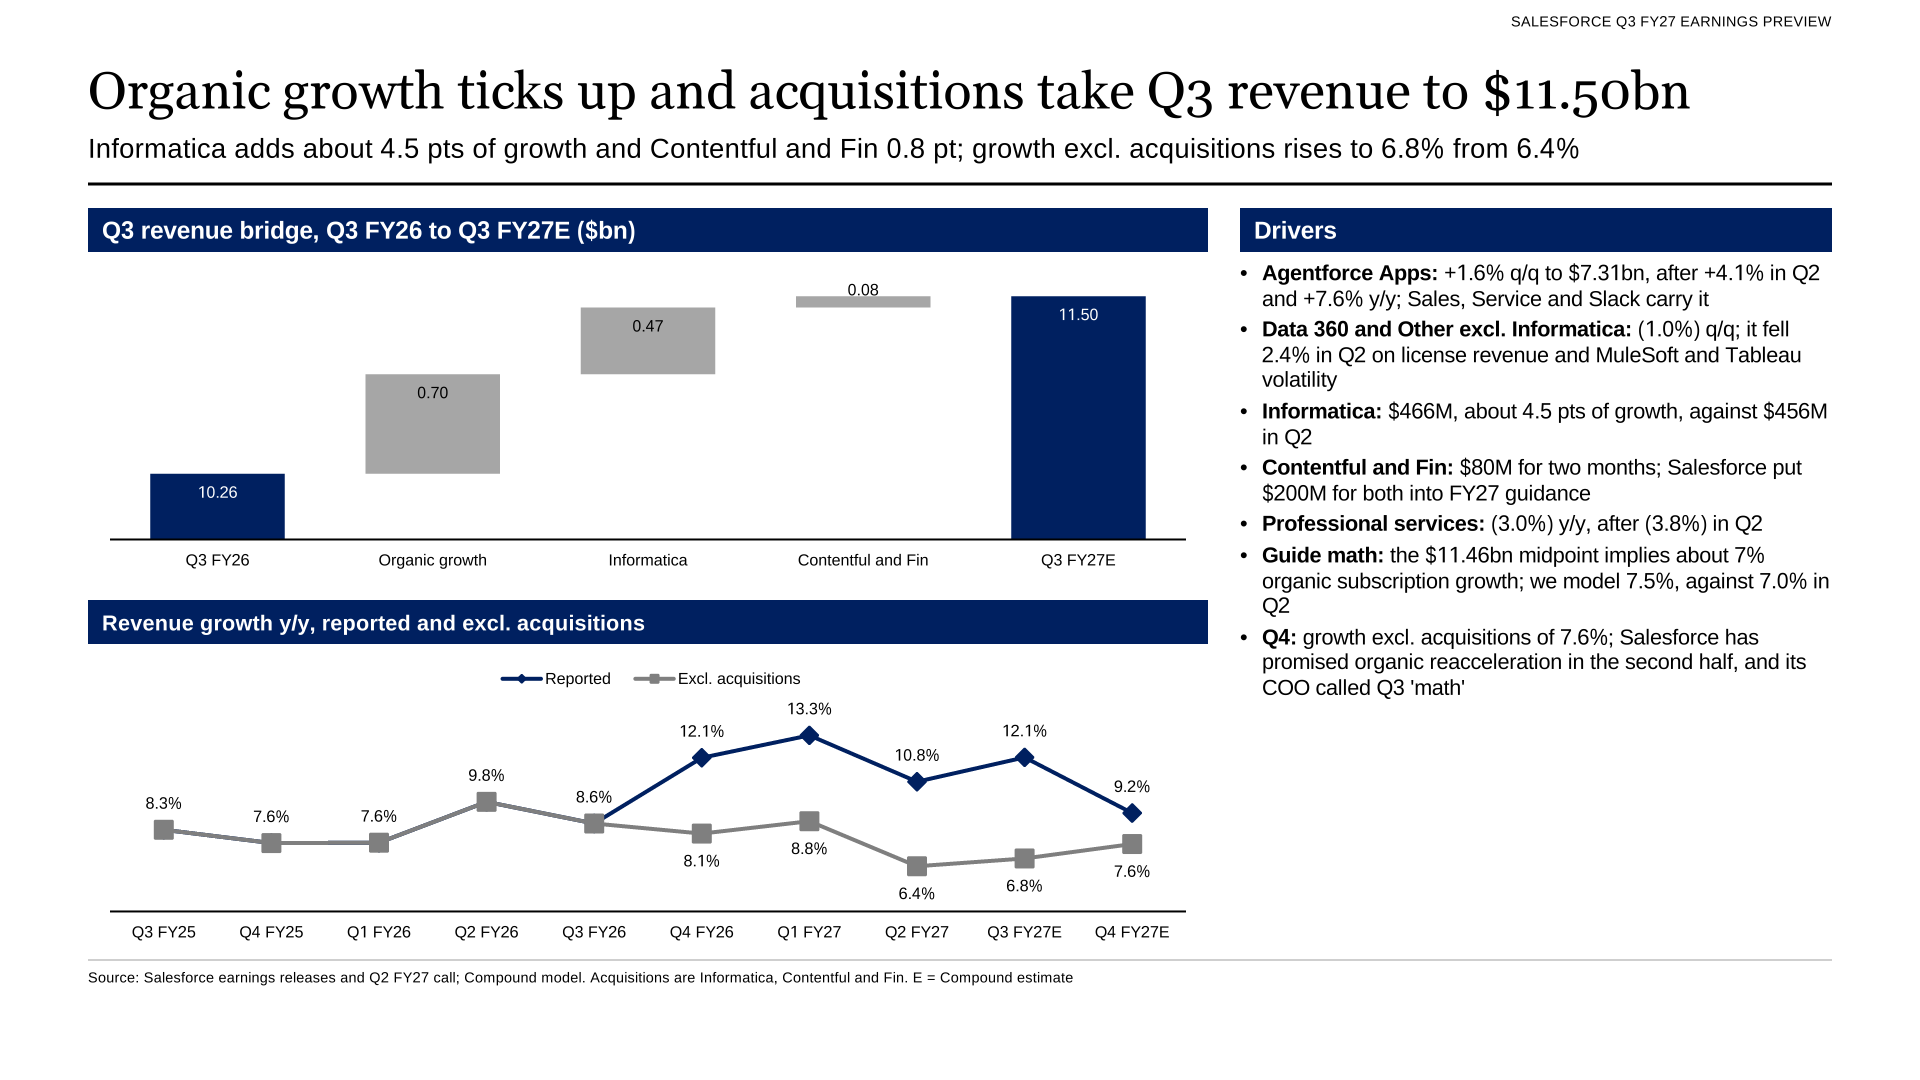
Revenue bridge, and growth with and without acquisitions.
On margin we sit 0.8 points above consensus at 35.2%. Salesforce earned 35.5% in the third quarter a year ago, and its full-year guide of 34.3% implies about 34.9% for this quarter by our math. Excluding investment gains, EPS beat the guidance midpoint in each of the past eight quarters, by 3.4% to 8.0%. We assume 2.3%.
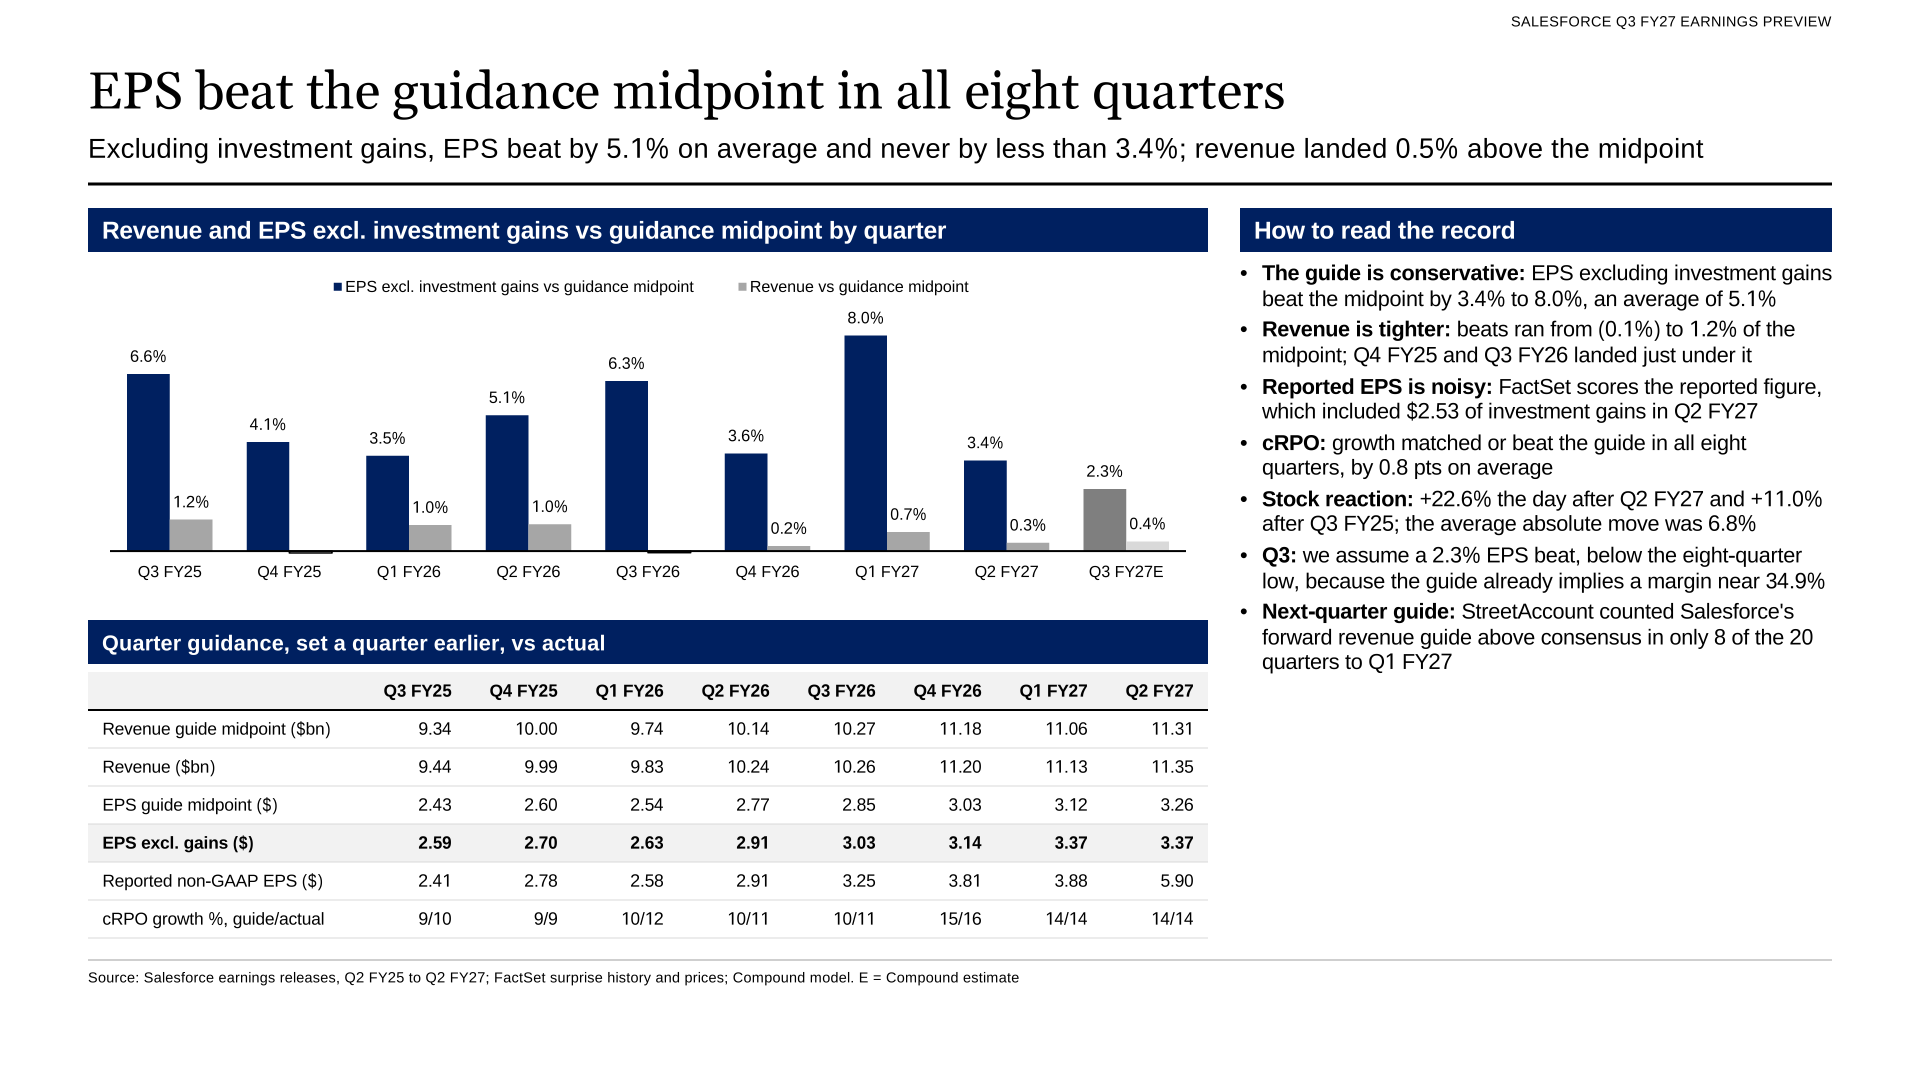
EPS excluding investment gains beat the guidance midpoint in each of the last eight quarters.
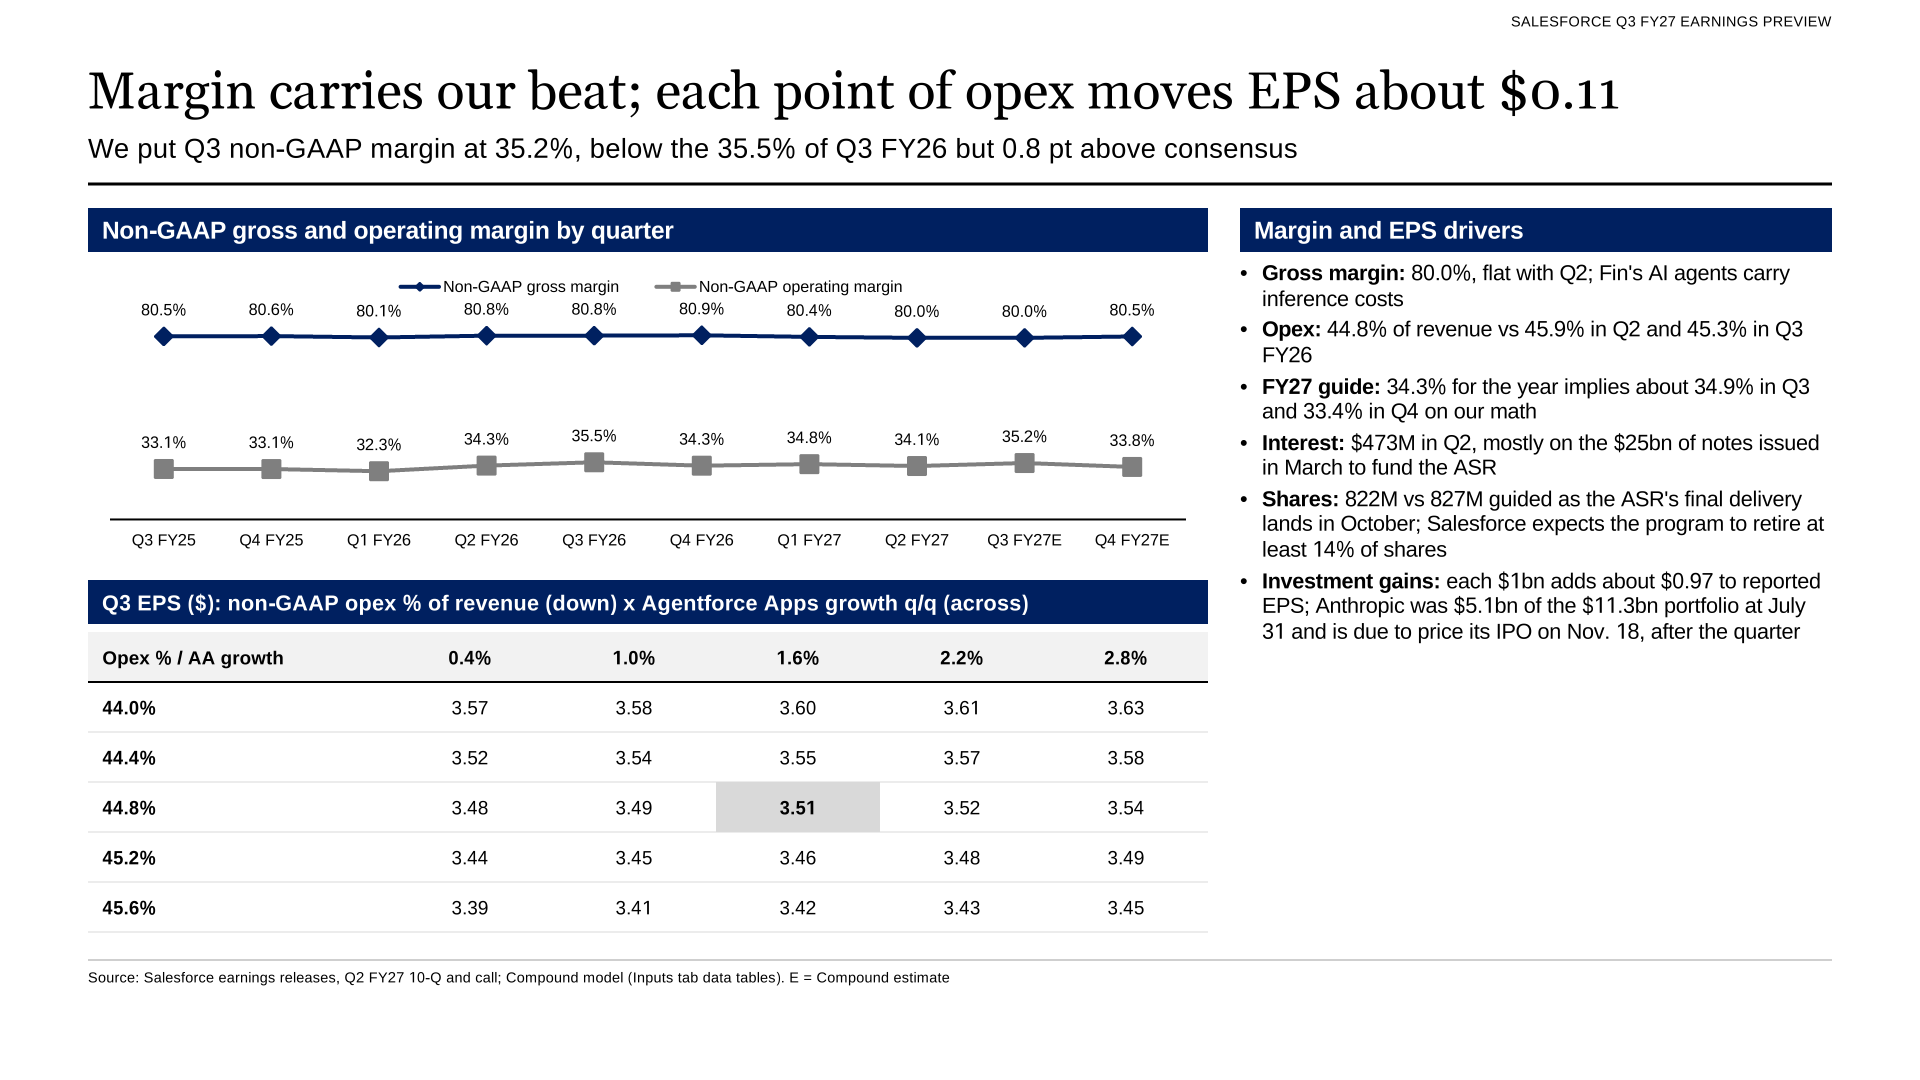
Margins by quarter and the Q3 EPS sensitivity from the model's data table.
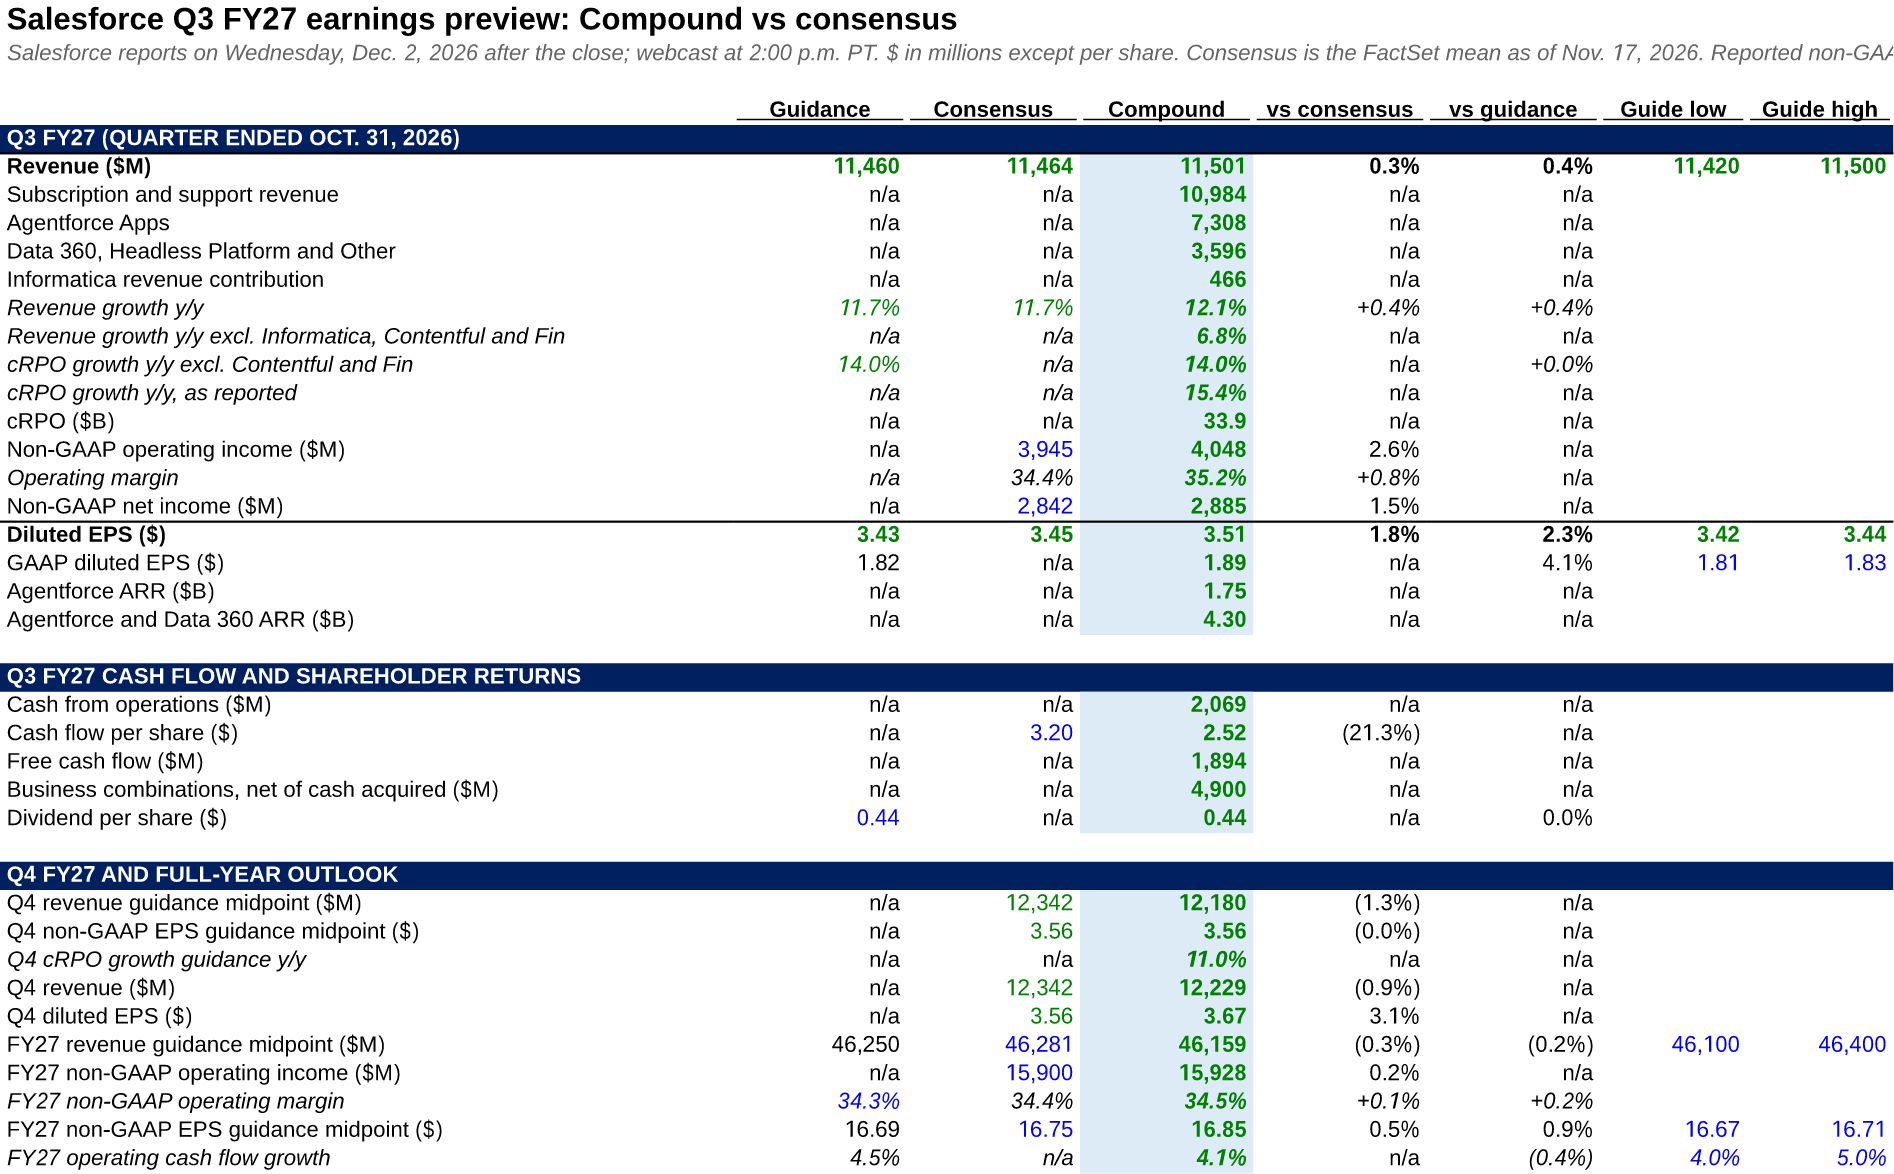
The Preview tab of the Excel model, which links every estimate to its drivers.
cRPO and the Informatica lap
Current remaining performance obligation, the contracted revenue due over the next 12 months, was $33.5 billion at the end of the second quarter, up 14%. Salesforce guided third-quarter cRPO growth of about 14%, excluding Contentful and Fin. The reported number will include them; we add $0.4 billion and get $33.9 billion, up 15.4%.
The fourth quarter is where the headline slows. Informatica added 4 points to cRPO growth in the fourth quarter of fiscal 2026, Salesforce said. A year on, it sits in both periods. We expect Salesforce to guide fourth-quarter cRPO growth of about 11%.
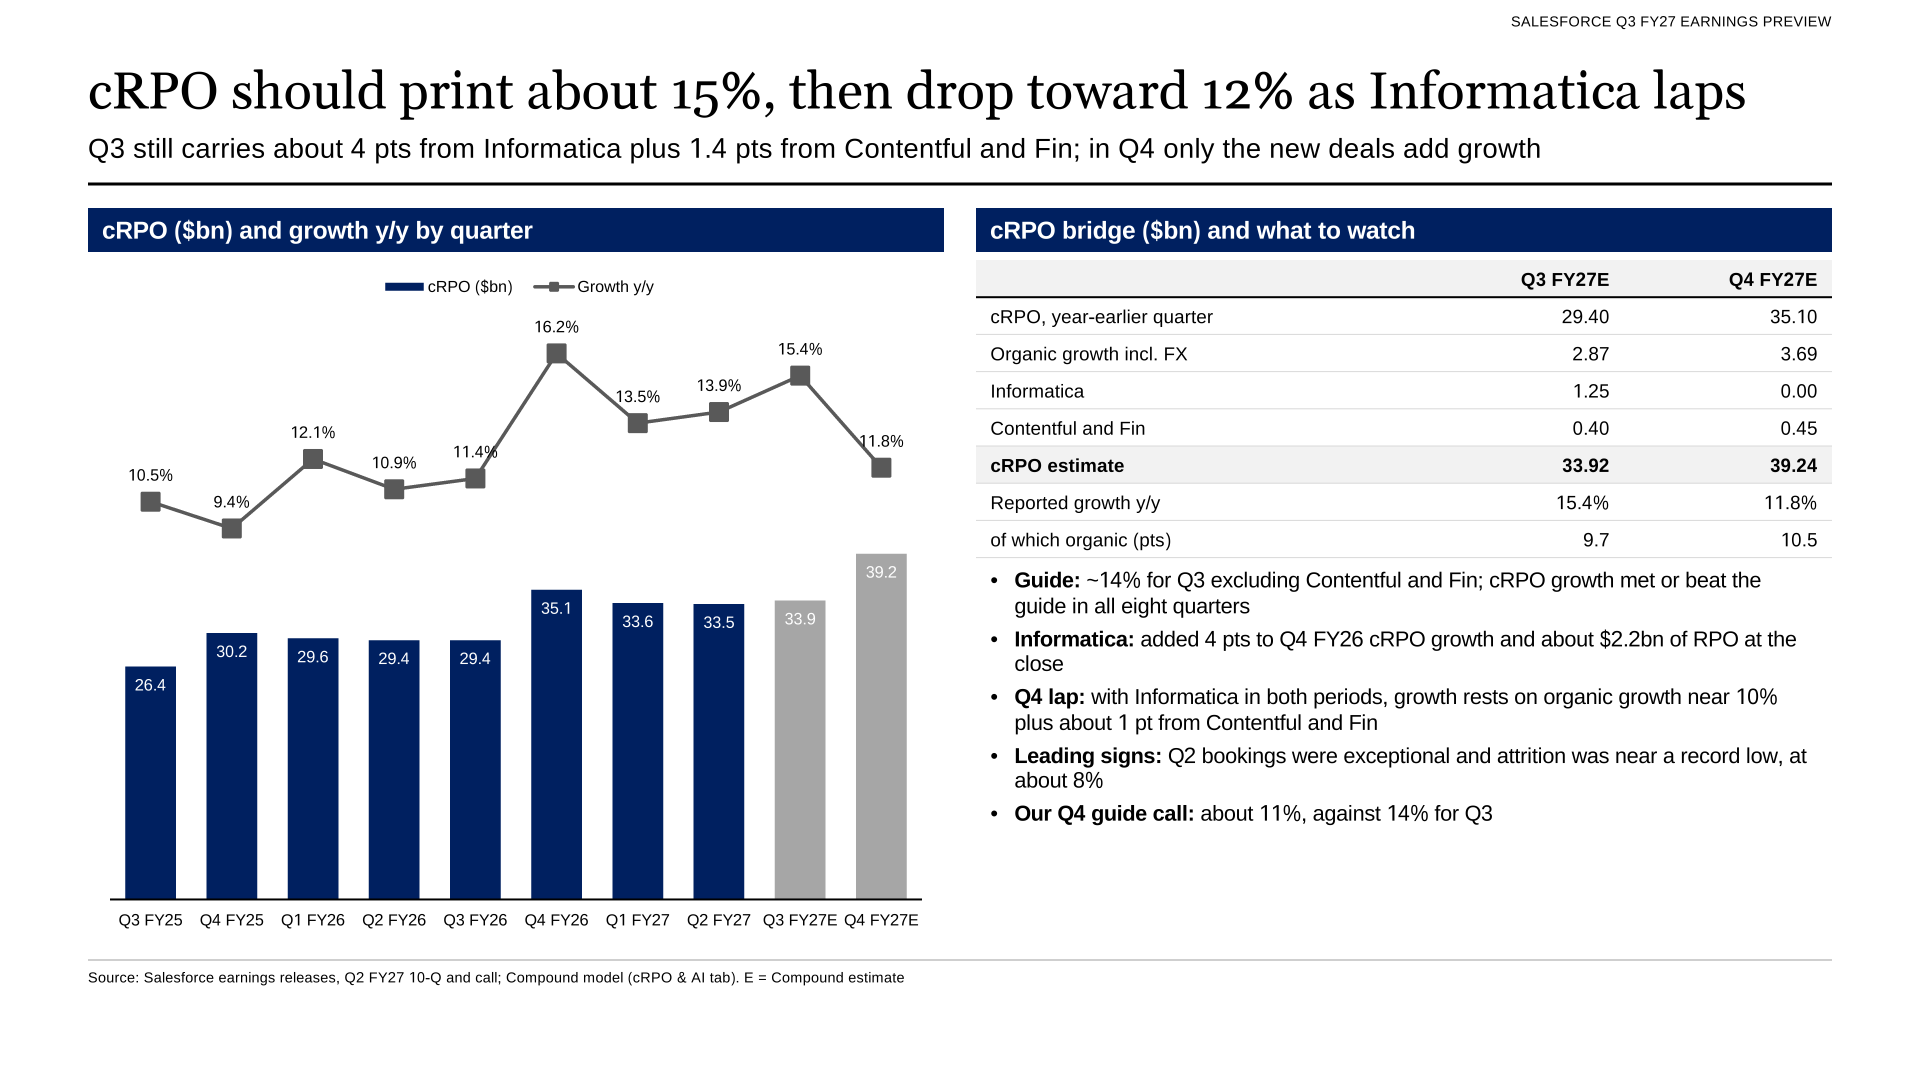
cRPO by quarter and the bridge for Q3 and Q4.
Q4 guidance and the dollar
FactSet consensus has fourth-quarter revenue of $12.34 billion. Salesforce's full-year guide of $46.1 billion to $46.4 billion implies about $12.31 billion at the midpoint. We estimate $12.23 billion and expect a guidance midpoint near $12.18 billion. The Federal Reserve's broad dollar index was 118.4 on Aug. 26, when Salesforce set that guide, and 122.7 on Nov. 13. StreetAccount counted Salesforce's next-quarter revenue guide above consensus in 8 of the 20 quarters to the first quarter of fiscal 2027.
Fourth-quarter EPS should hold up better. Salesforce expected the final settlement of its $25 billion accelerated share repurchase in October; we assume it delivered about 27 million more shares, which takes our fourth-quarter EPS to $3.67 against a consensus of $3.56. We expect EPS guidance near $3.56 and the full-year EPS range raised to about $16.85, from $16.67 to $16.71.
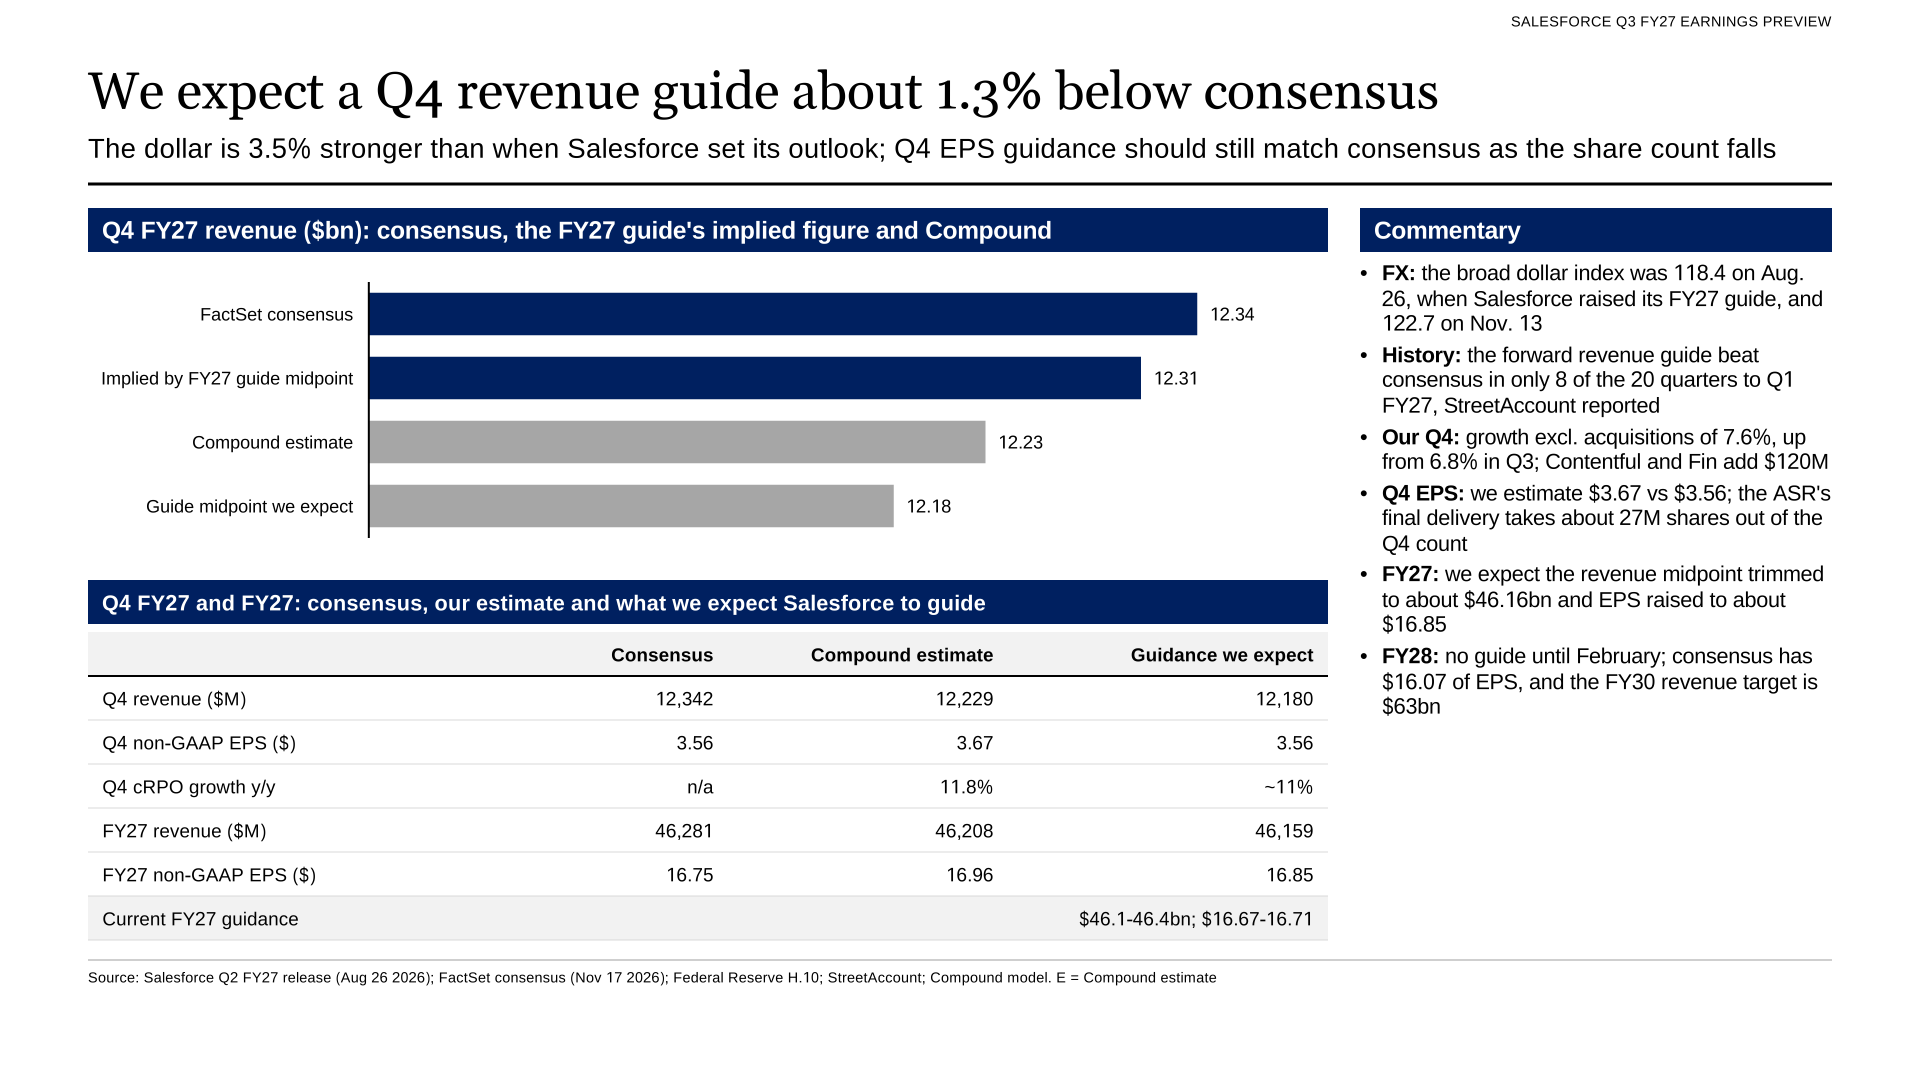
Q4 revenue: consensus, the guide's implied figure, our estimate and the guide we expect.
Agentforce and AI revenue
Agentforce ARR exceeded $1.5 billion in the second quarter, up more than 240%, on a definition that now includes Slackbot and Headless 360. Agentforce and Data 360 ARR reached nearly $3.9 billion, including Informatica Cloud ARR, which was $1.1 billion in the first quarter. We forecast $1.75 billion and $4.3 billion for the third quarter, excluding Fin. Dealroom estimates Intercom's ARR at about $400 million, of which the Fin agent is about $110 million (unconfirmed).
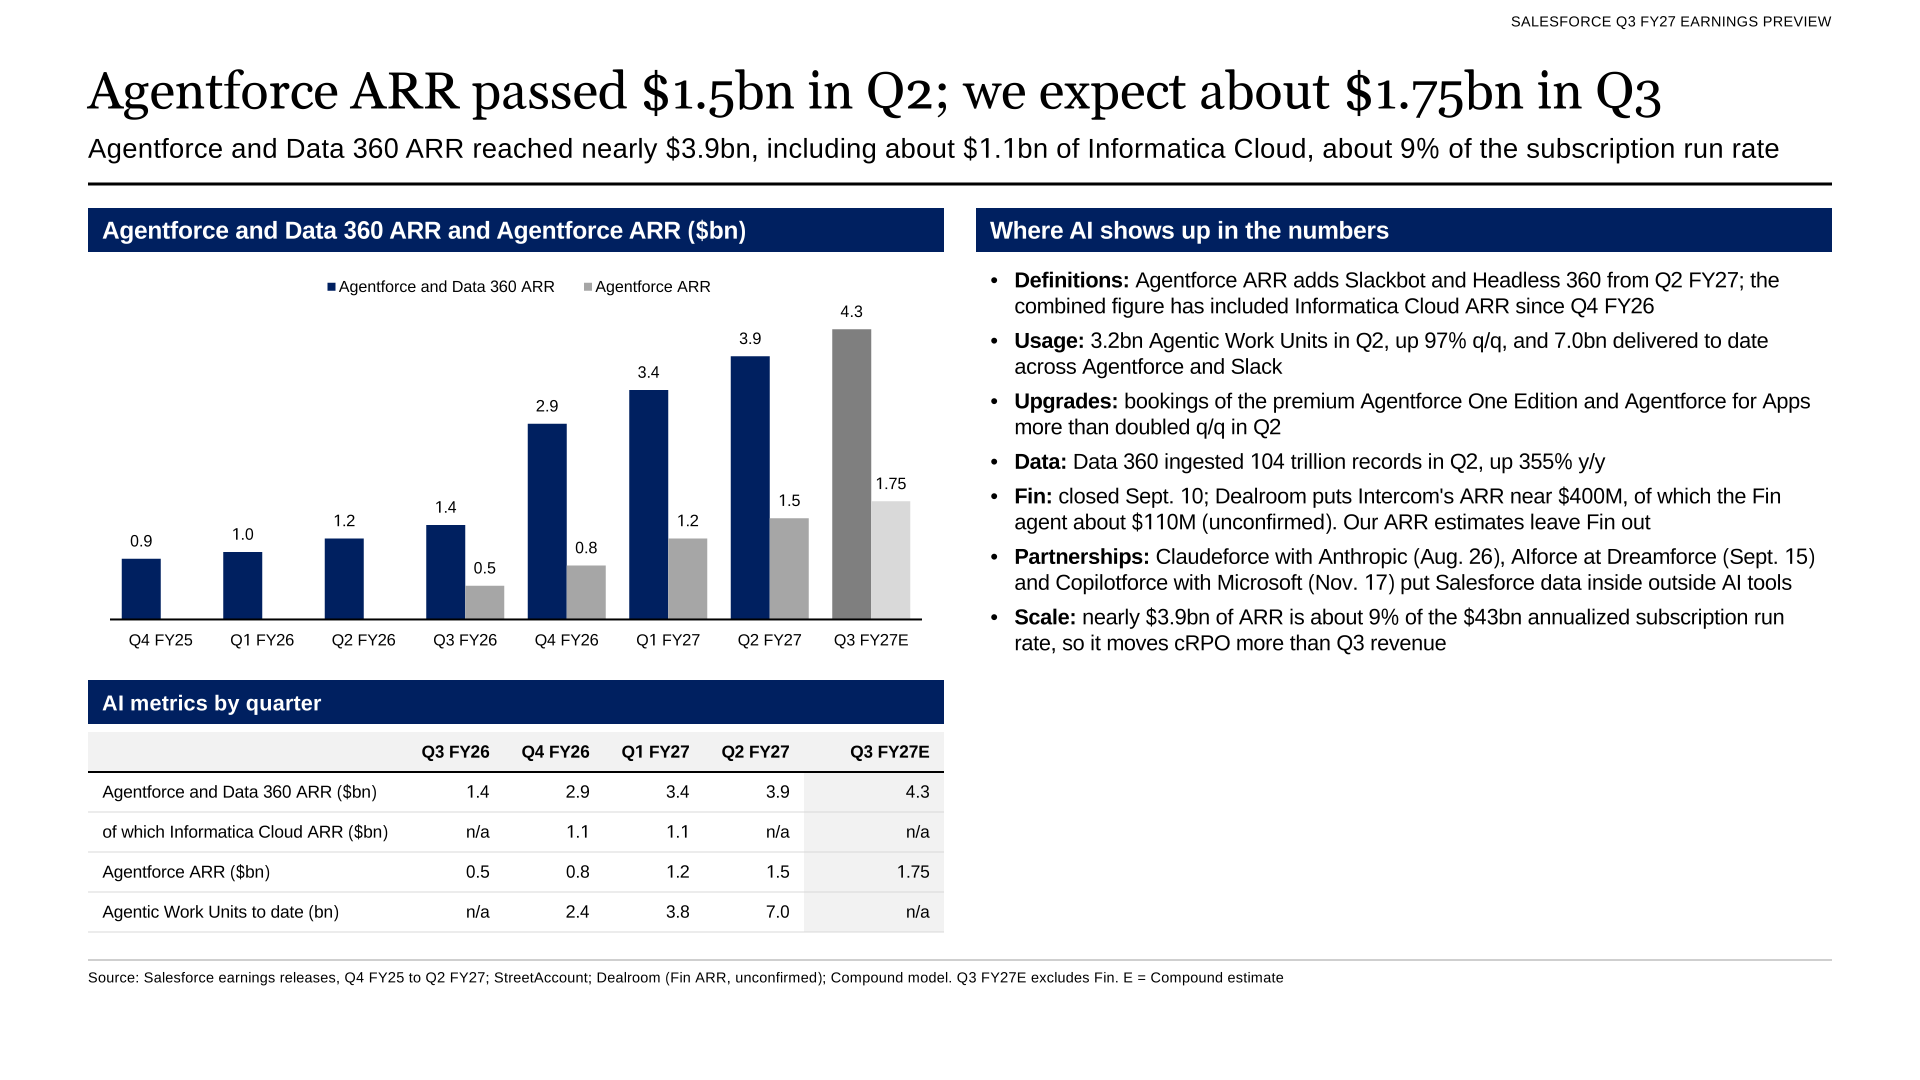
Agentforce and Data 360 ARR by quarter, with usage and partnership notes.
Cash, buybacks and deals
Fin and Contentful, which cost about $3.6 billion and $1.5 billion in cash, closed on Sept. 10 and Sept. 1. Salesforce agreed on Oct. 20 to buy Braze for about $5.66 billion in enterprise value and on Nov. 2 to buy Cresta, for $2.7 billion according to The Information (unconfirmed). Both deals close in fiscal 2028. Net debt was $27.9 billion at July 31, after the $25 billion bond sale that funded the share repurchase.
We forecast third-quarter free cash flow of $1.89 billion, against $2.18 billion a year earlier. The notes pay interest semiannually, and by our reading of the March issue date the first coupon falls in this quarter.
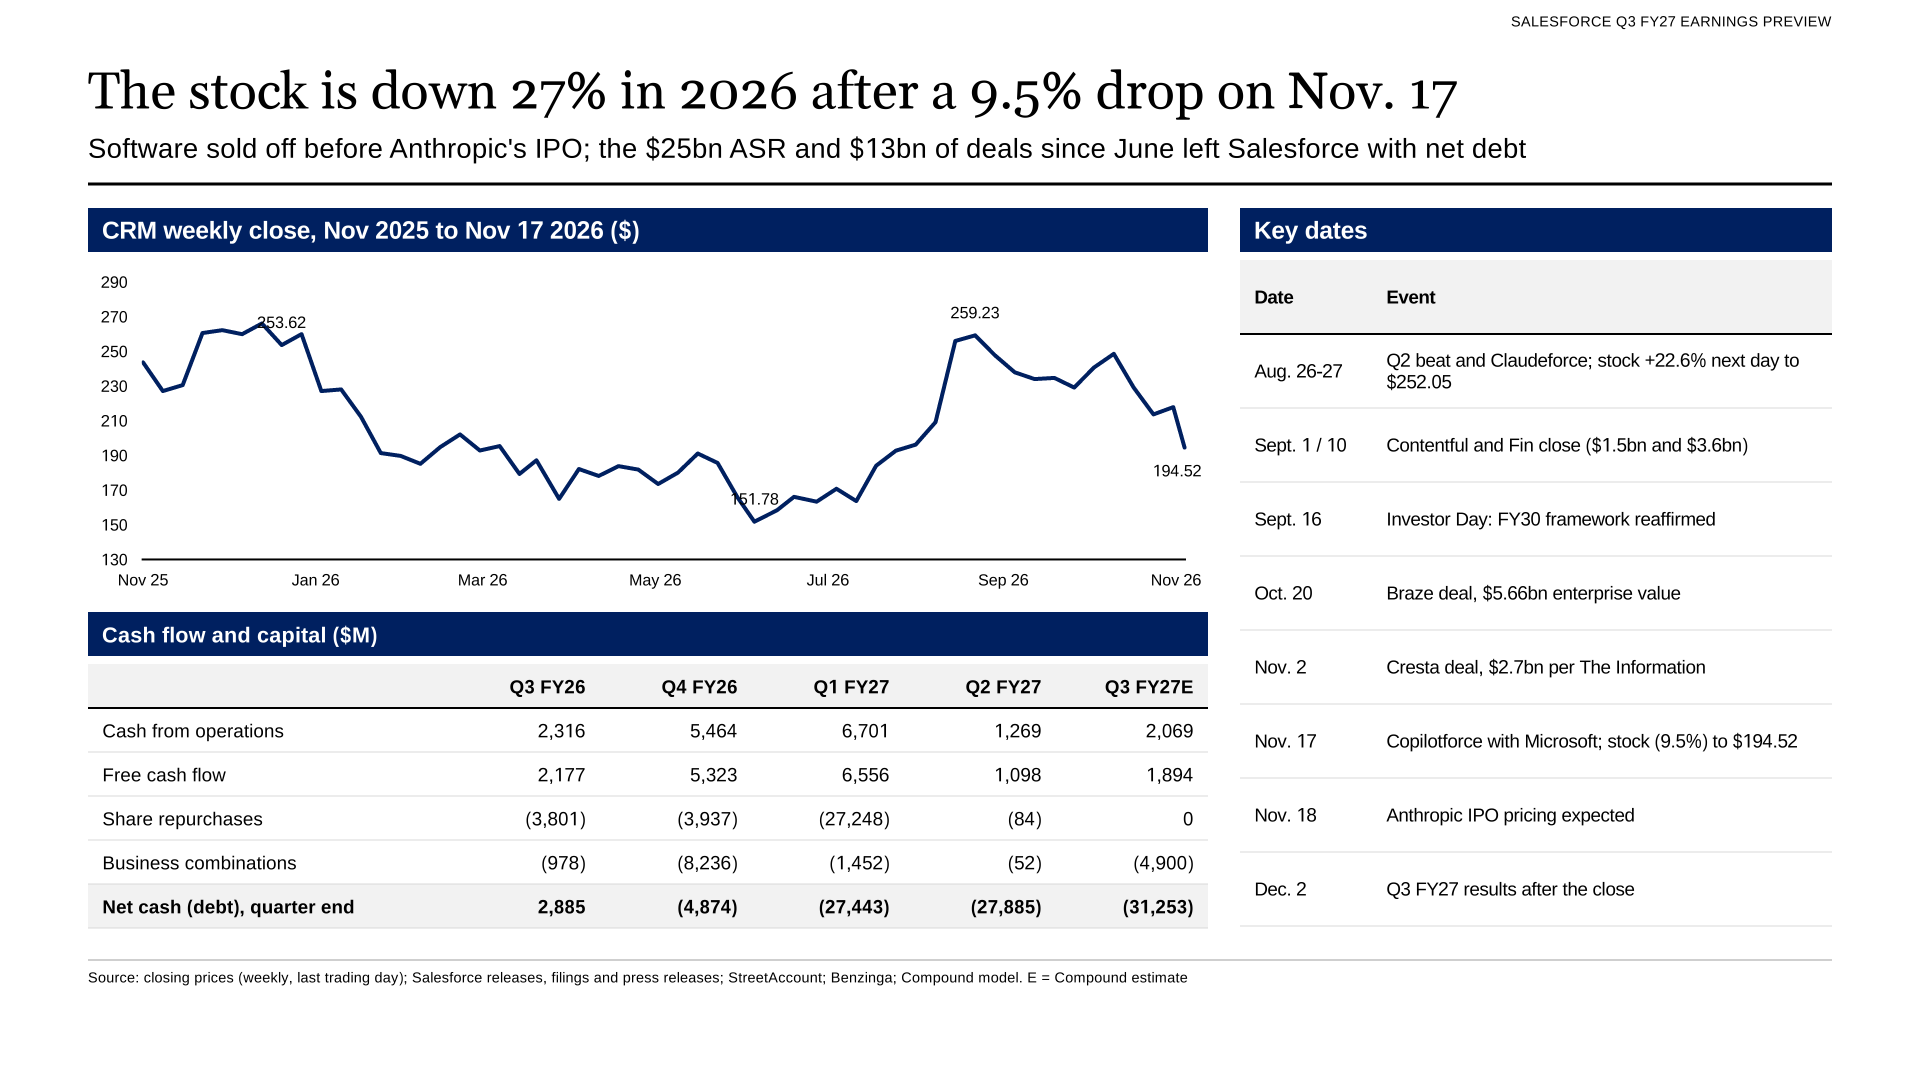
Share price since November 2025, cash flow and the key dates.
What to watch on Dec. 2
- Revenue against the $11.46 billion consensus and the $11.50 billion top of guidance.
- Growth excluding Informatica, Contentful and Fin against the second quarter's 6.4%.
- cRPO growth against the roughly 14% guide, and how much Contentful and Fin add.
- The fourth-quarter revenue guide against the $12.34 billion consensus, and the cRPO guide once Informatica laps.
- Any third-quarter gains on the strategic portfolio, which flow into reported non-GAAP EPS, and comments on the Anthropic stake after its listing.
- Agentforce ARR against the second quarter's $1.5 billion.
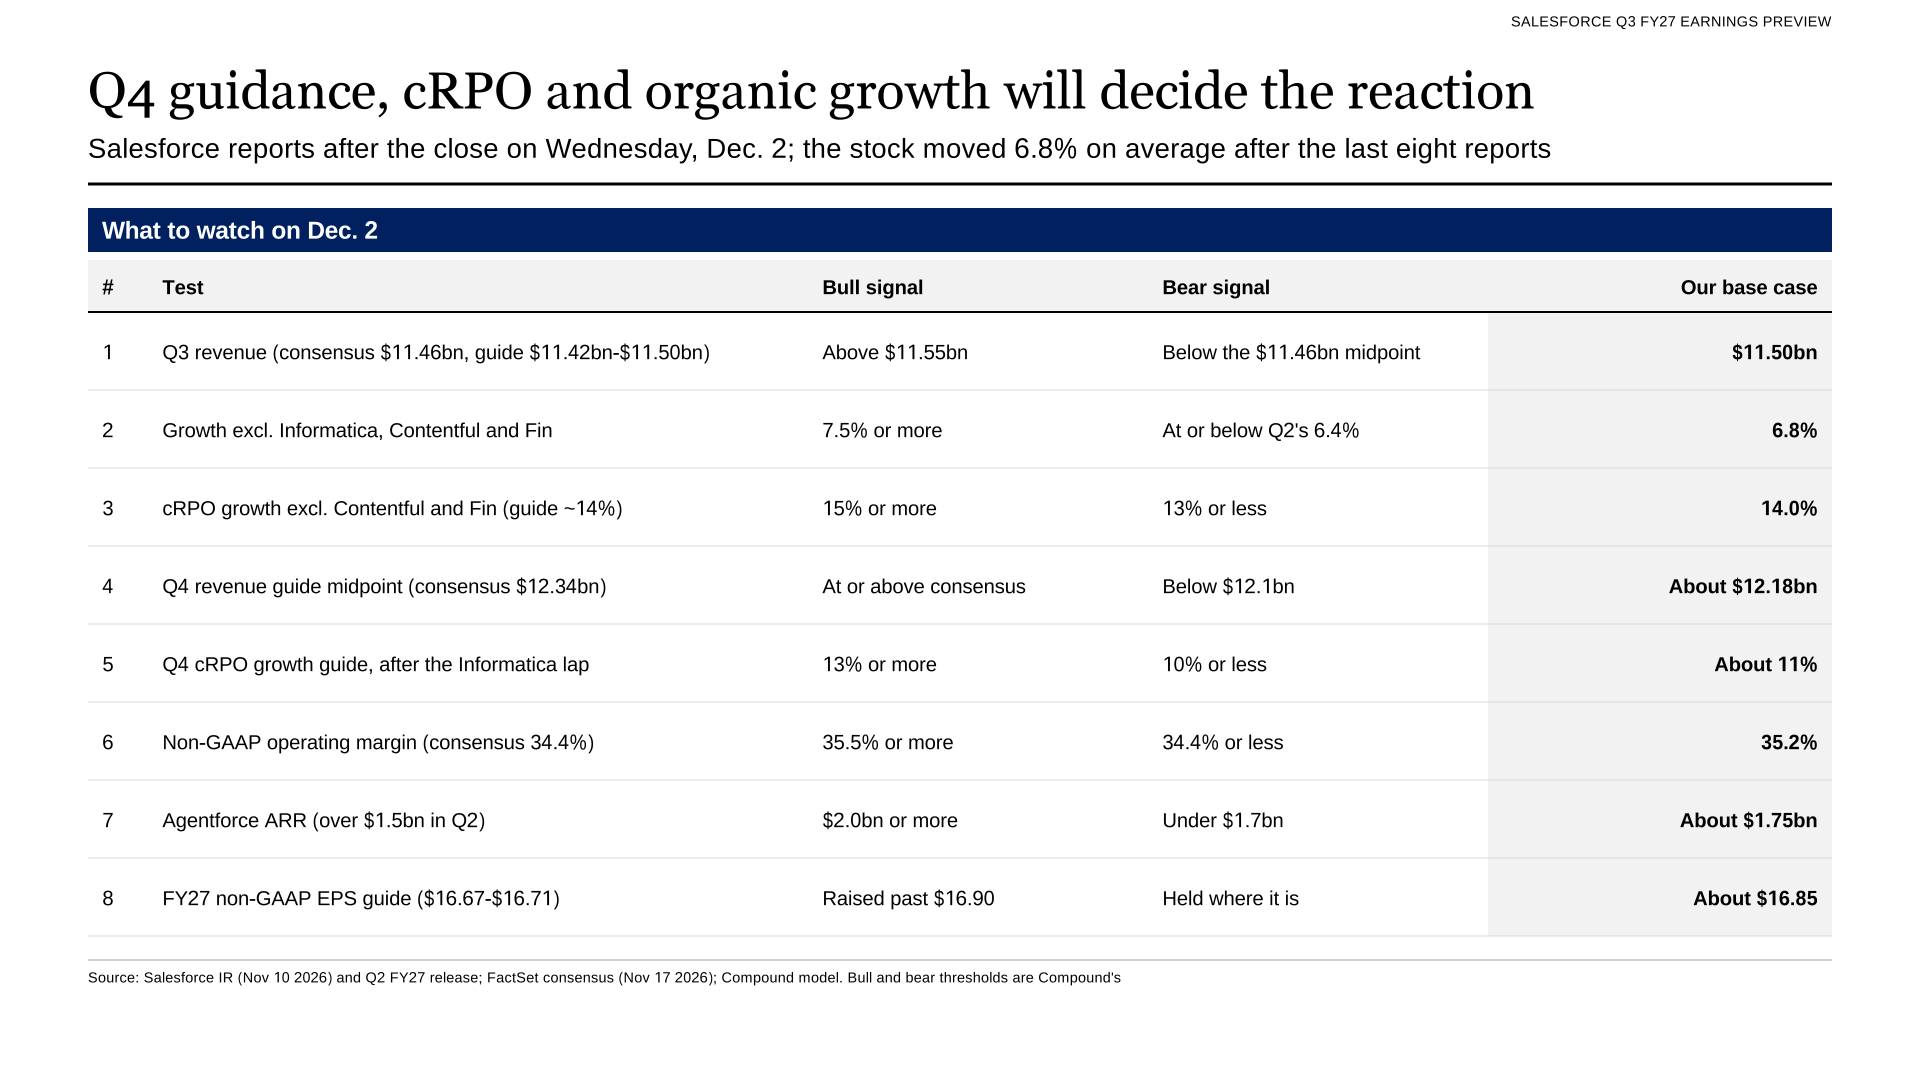
Eight tests for the call, with bull and bear signals and our base case.
We will score this forecast against the reported numbers after the release.
 Salesforce Q3 FY27 earnings preview deck (PowerPoint)The 11-page preview: executive summary, forecast against consensus, track record, revenue build, cRPO and the Informatica lap, AI ARR, margins and EPS sensitivity, Q4 guidance, share price and cash, and the checklist for the call, with editable charts and tables.Download · Free
 Salesforce Q3 FY27 earnings preview deck (PDF)The same 11 pages as a PDF.Download · Free
 Salesforce Q3 FY27 earnings model (Excel)Quarterly model from Q3 FY25: revenue build, cRPO and AI metrics, non-GAAP and GAAP income statements, cash flow, balance sheet and working capital, guidance and consensus track record, Compound's Q3 and Q4 estimates, native Excel sensitivity tables, and a tab on revenue mix, Informatica, the cRPO bridge and acquisitions, with formulas and sources.Download · Free
More from Compound News
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Read article →
Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Read article →
CrowdStrike Q3 Earnings Preview: $0.33 EPS vs $0.31 Consensus
CrowdStrike reports Tuesday after the close. Our model puts net new ARR 9% above guidance, revenue 2.0% above consensus at $1.56 billion and EPS at $0.33 against $0.31.
Read article →