Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Snowflake reports fiscal third-quarter results on Wednesday, Dec. 2, after the market close, with the call at 2 p.m. PT, according to the company's Nov. 2 announcement. The quarter ended Oct. 31.
Compound's model forecasts Q3 product revenue of $1.646 billion, 3.5% above the $1.5905 billion midpoint of Snowflake's guidance and 42% above a year earlier. FactSet consensus for total revenue is $1.654 billion; we forecast $1.702 billion. We forecast non-GAAP EPS of $0.69 against a consensus of $0.60.
The stock closed at $272.94 on Nov. 17, down 23.4% from $356.47 on Sept. 3, the day after the second-quarter report, according to FactSet prices. It rose 16.6% that day.
We built an 11-page earnings preview deck on the model, in the format of our Nike Investor Day memo. The slides below come from it, and the deck and the Excel model are free to download at the end.
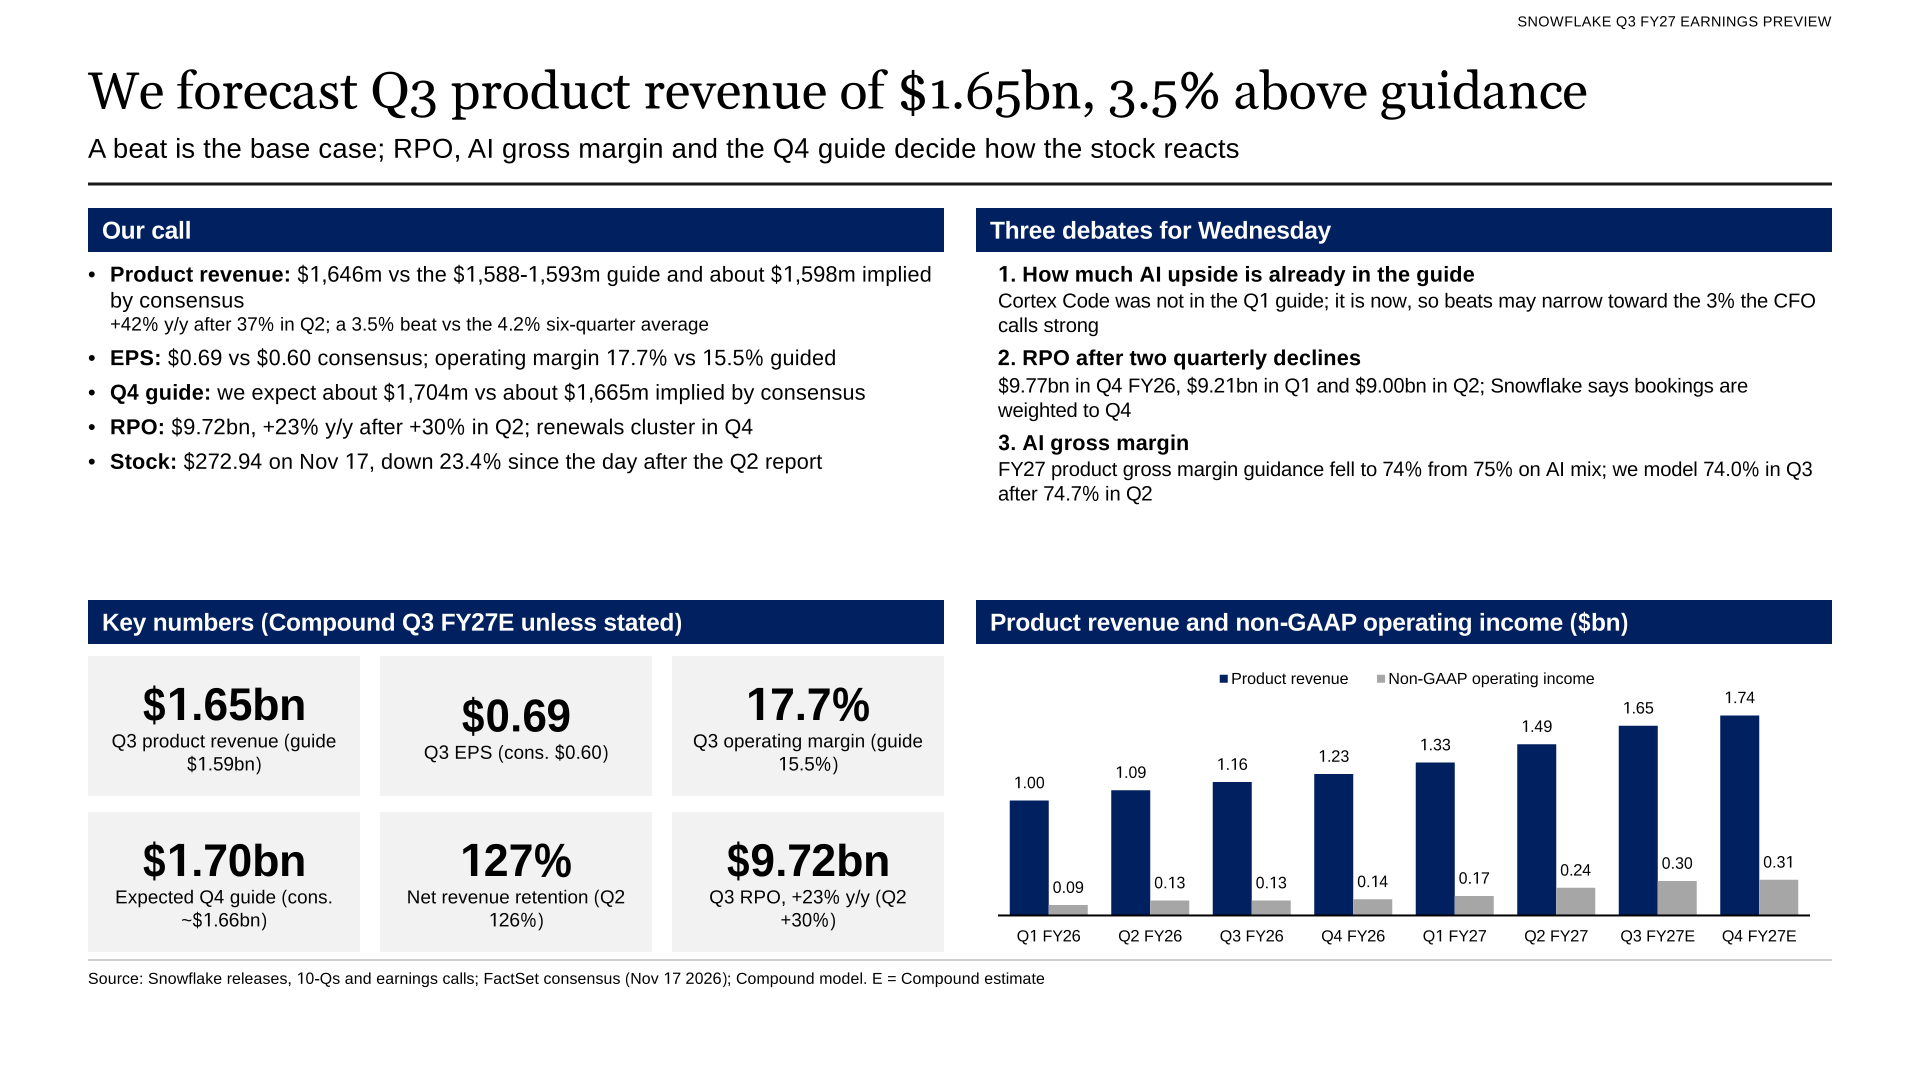
Executive summary: our call against consensus and the three debates for Wednesday.
Forecast vs consensus
| Q3 FY27 | Guidance | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Product revenue | $1.59B | $1.60B (implied) | $1.65B | +3.0% |
| Total revenue | n/a | $1.65B | $1.70B | +2.9% |
| Product revenue growth | 37% to 38% | 38.0% | 42.1% | +4.1 pts |
| Non-GAAP product gross margin | 74.0% (full year) | n/a | 74.0% | n/a |
| Non-GAAP operating margin | 15.5% | 15.6% | 17.7% | +2.1 pts |
| Non-GAAP operating income | n/a | $259M | $302M | +16.7% |
| EPS | n/a | $0.60 | $0.69 | +14.7% |
| Remaining performance obligations | n/a | n/a | $9.72B | n/a |
Consensus is the FactSet mean as of Nov. 17. FactSet does not carry a product revenue consensus; the implied figure deducts our $56 million estimate for professional services from consensus revenue. Guidance is from Snowflake's Sept. 2 release.
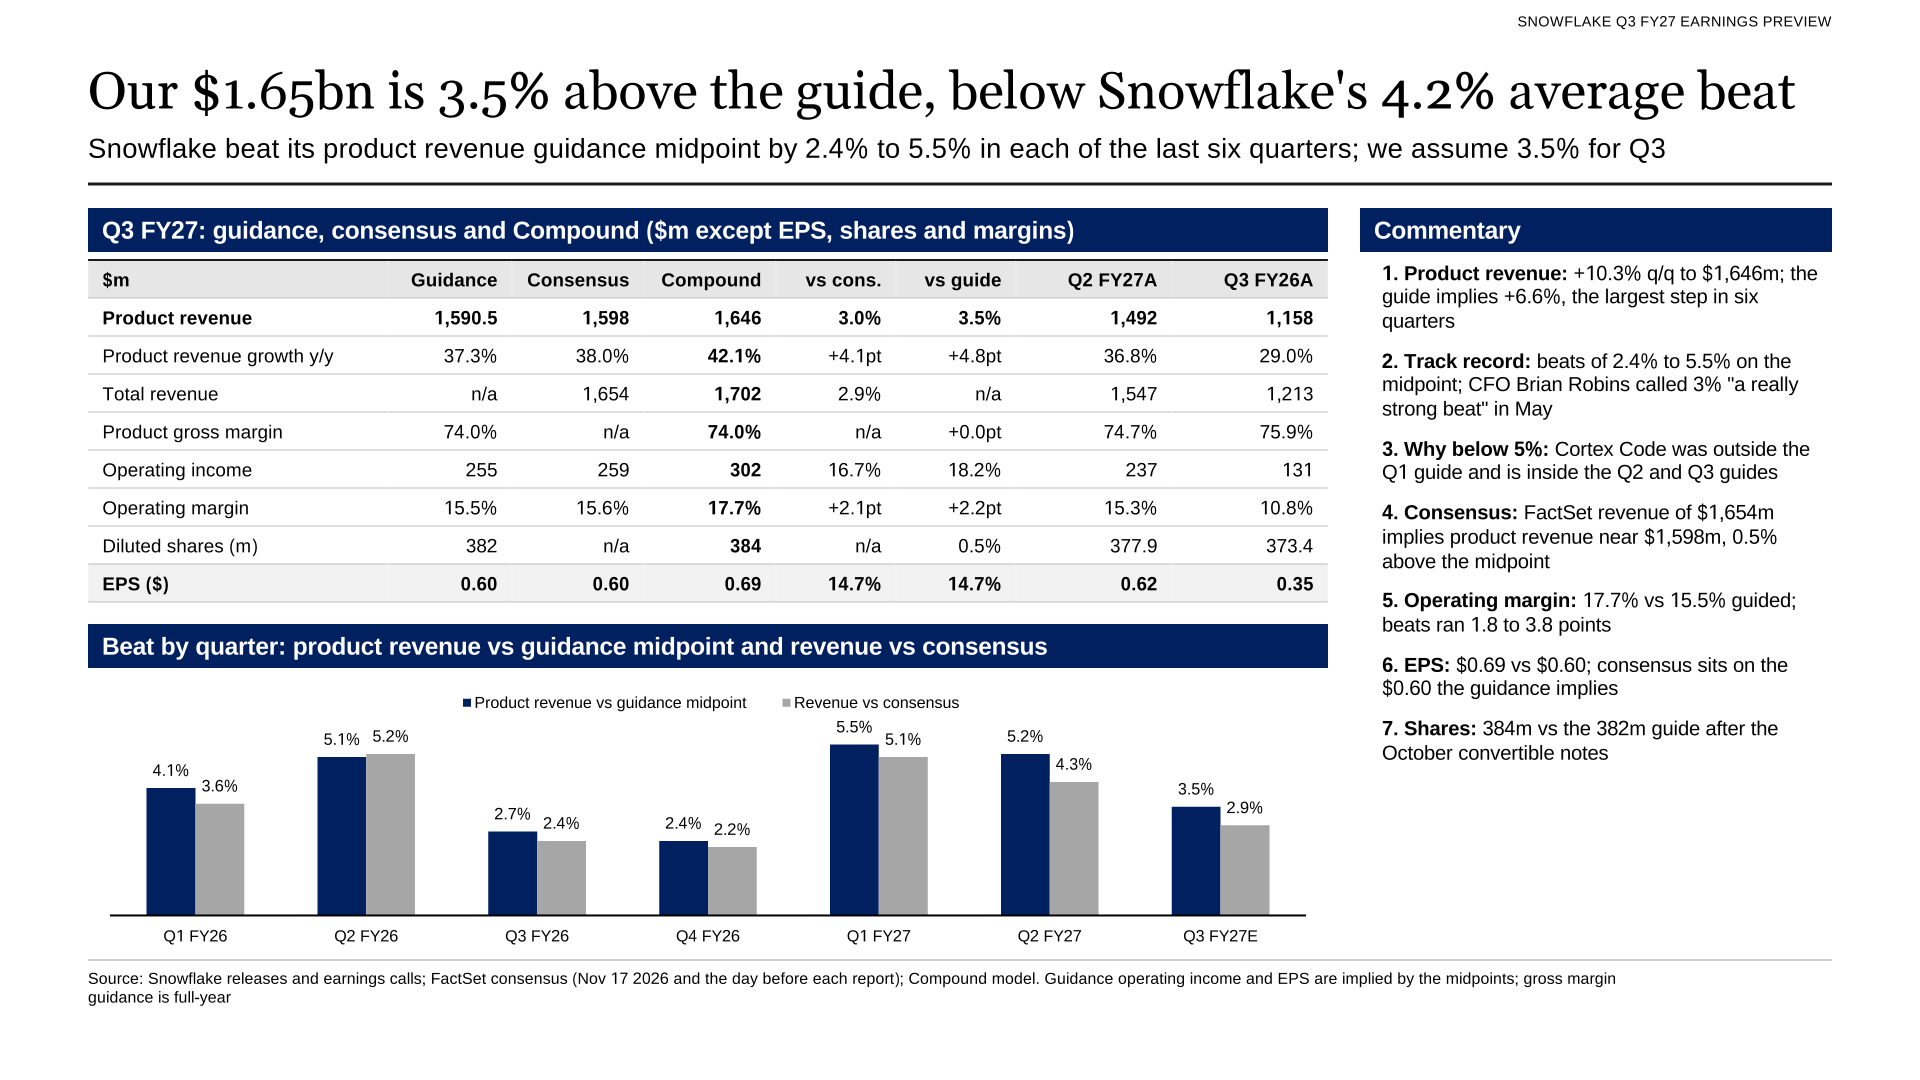
Snowflake beat its product revenue guidance midpoint by 2.4% to 5.5% in each of the last six quarters; we assume 3.5%.
How we built the forecast
The model starts from the guidance midpoint and adds a 3.5% beat. Snowflake beat the midpoint by 4.1%, 5.1%, 2.7%, 2.4%, 5.5% and 5.2% in the six quarters through Q2, an average of 4.2%, according to its releases. CFO Brian Robins said on the May call that the company views a 3% beat as "a really strong beat."
We sit below the last two quarters because of how Snowflake guides. It forecasts only from consumption it has already observed. Cortex Code, its AI coding agent, had no usage history when the first-quarter guide was set, and Robins said in May that it was the largest driver of the raise that followed. It is now in the guide, so less AI upside is left to surprise.
The third-quarter guide already asks for more. Its midpoint is 6.6% above second-quarter product revenue, the largest step in six quarters. Our forecast implies 10.3% sequential growth, after 11.8% in Q2.
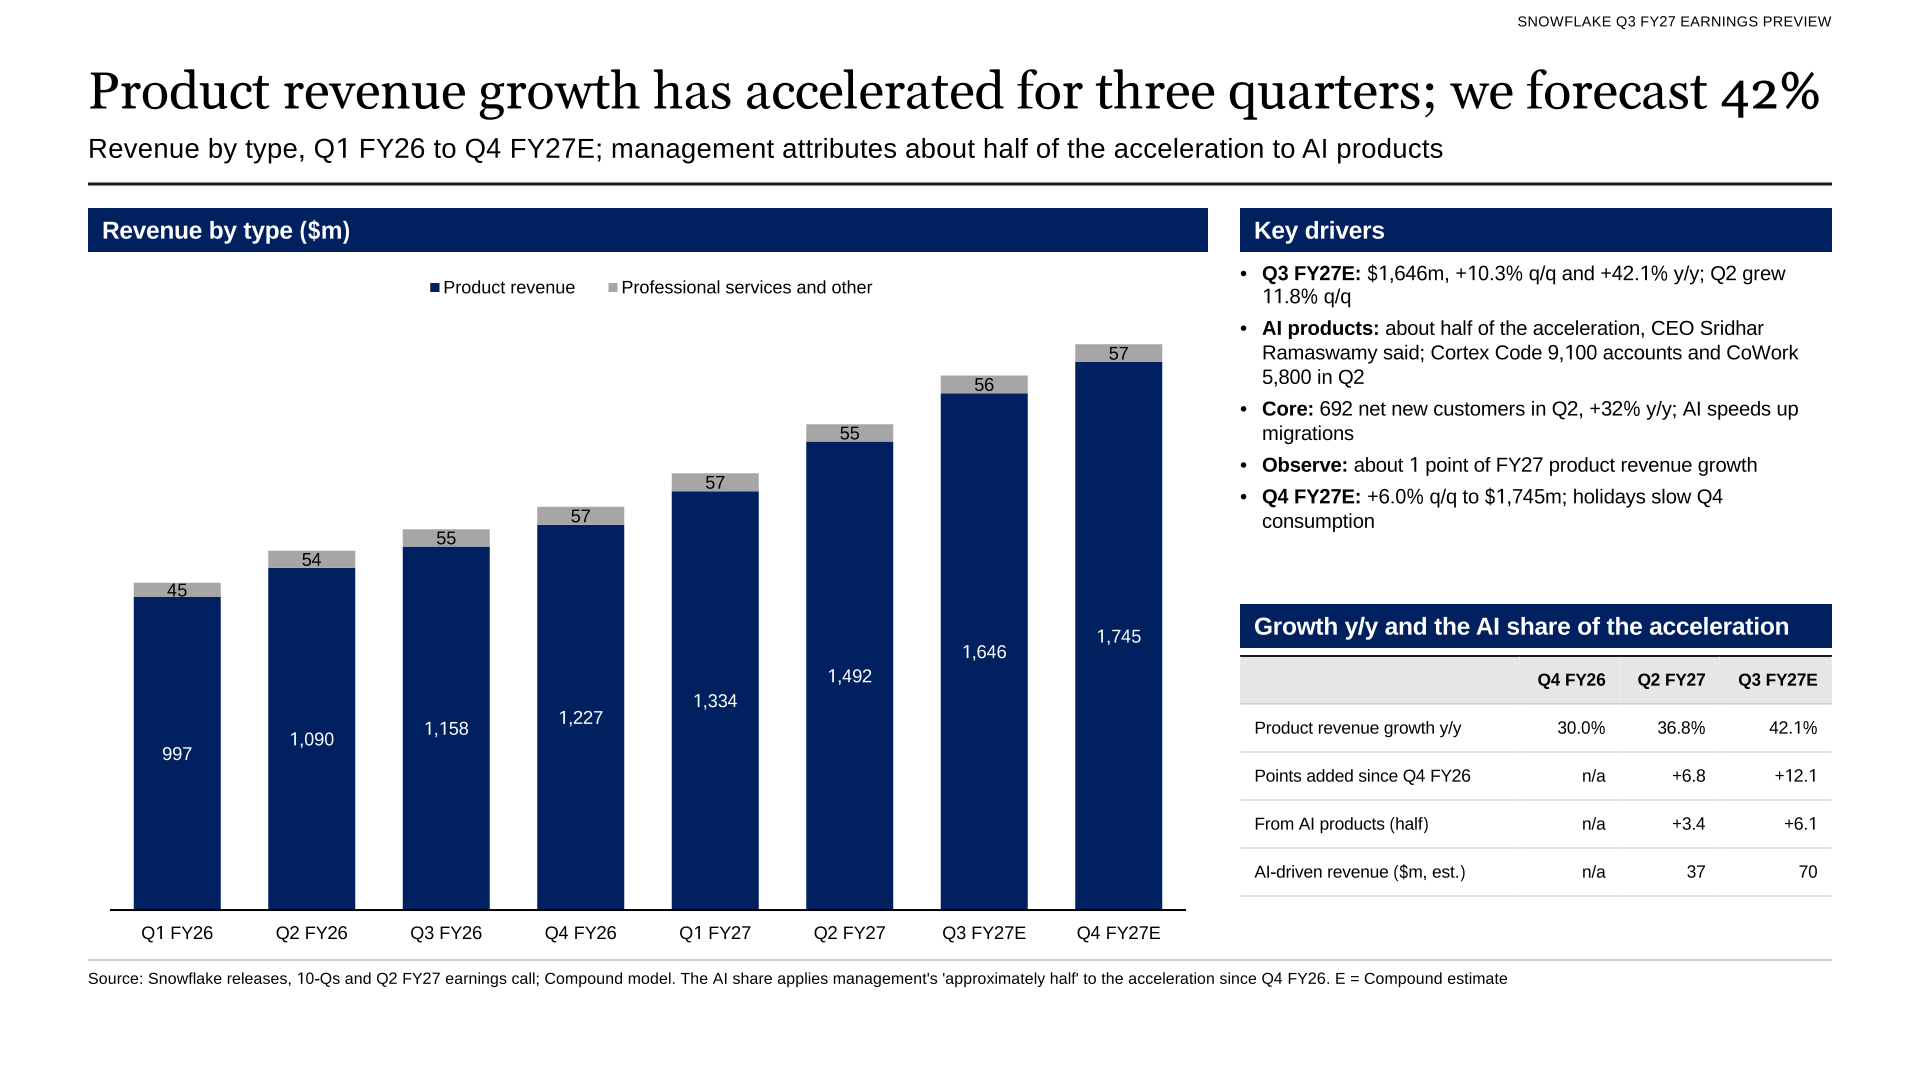
Product revenue by quarter; management attributes about half of the acceleration to AI products.
AI workloads and consumption
Product revenue growth rose from 30% in the fourth quarter of fiscal 2026 to 37% in Q2. CEO Sridhar Ramaswamy said on the Sept. 2 call that AI products "contributed approximately half of the acceleration." On that split, AI added about 3.4 points of growth, or about $37 million of Q2 product revenue. Cortex Code reached 9,100 accounts and CoWork 5,800 in Q2, Snowflake said.
Cloud consumption picked up in the September quarter. AWS sales rose 39.3%, according to Amazon, and Google Cloud revenue rose 103%, according to Alphabet. Microsoft guided Azure growth of 49% to 50% for the December quarter. Datadog, which also prices on usage, fell 14.4% on Nov. 4 after a light fourth-quarter revenue guide, StreetAccount reported; Snowflake fell 5.1% before the open that day.
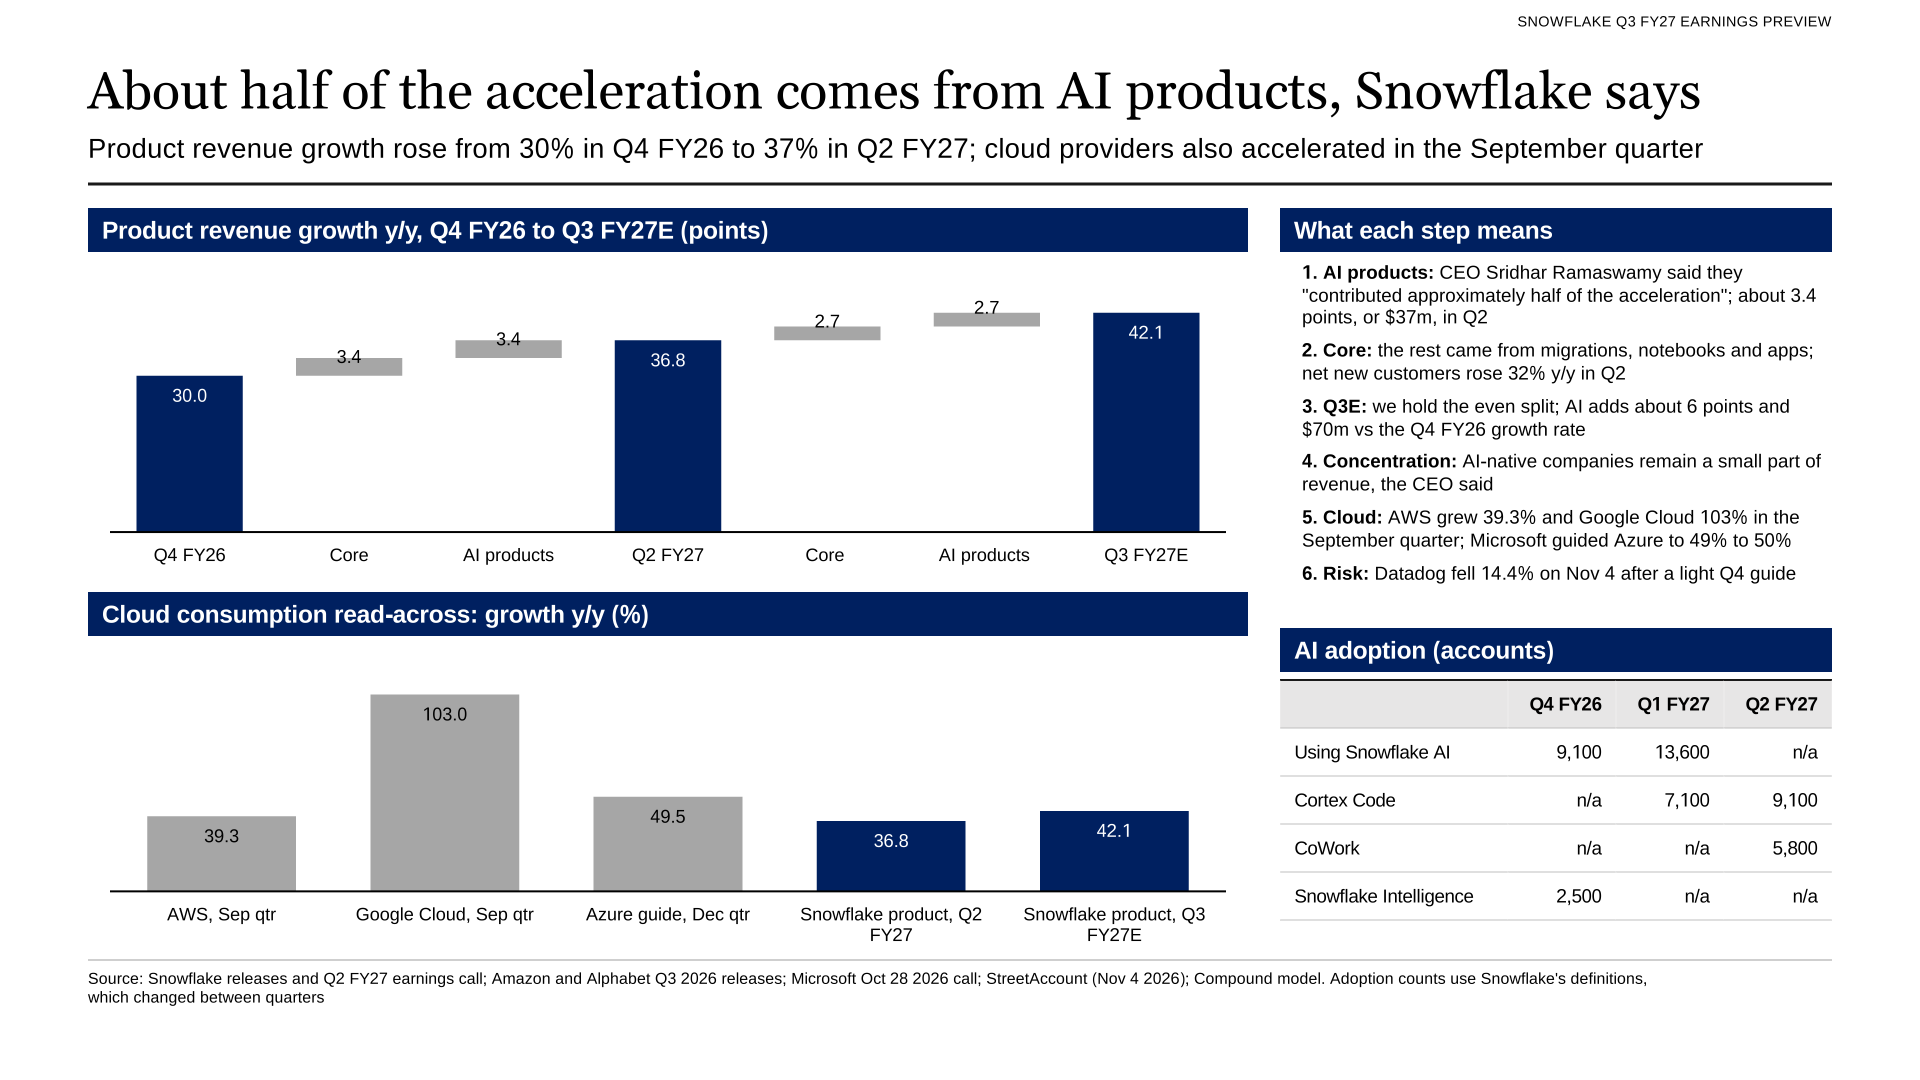
About half of the acceleration came from AI products, by Snowflake's account.
AI carries lower margins. Snowflake cut its fiscal 2027 non-GAAP product gross margin guidance to 74% from 75% in September, citing "a higher revenue mix from fast-growing AI workloads, which carry a lower contribution margin today." Product gross margin was 74.7% in Q2. We model 74.0% in Q3, which leaves non-GAAP operating margin at 17.7% against 15.5% guided. Snowflake beat its operating margin guidance by 1.8 to 3.8 points in each of the last six quarters.
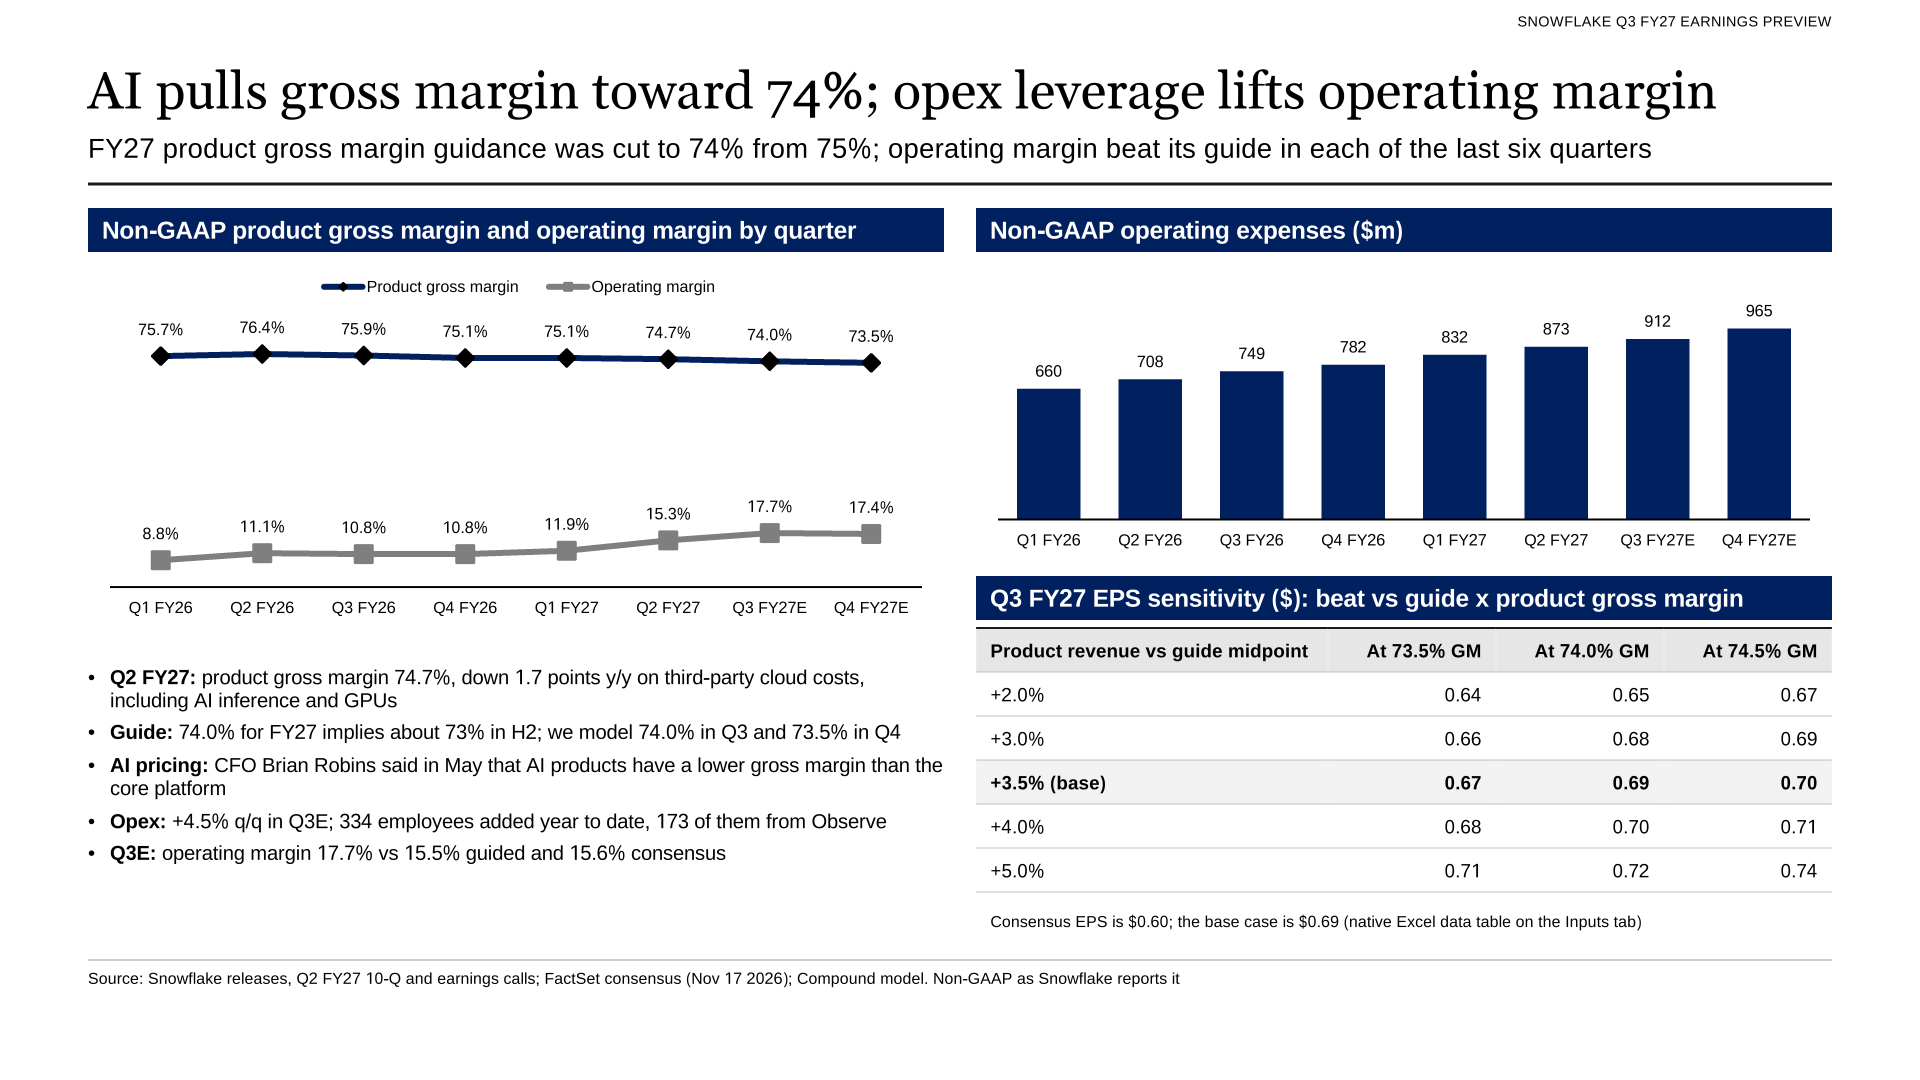
The EPS sensitivity comes from a native Excel data table in the model.
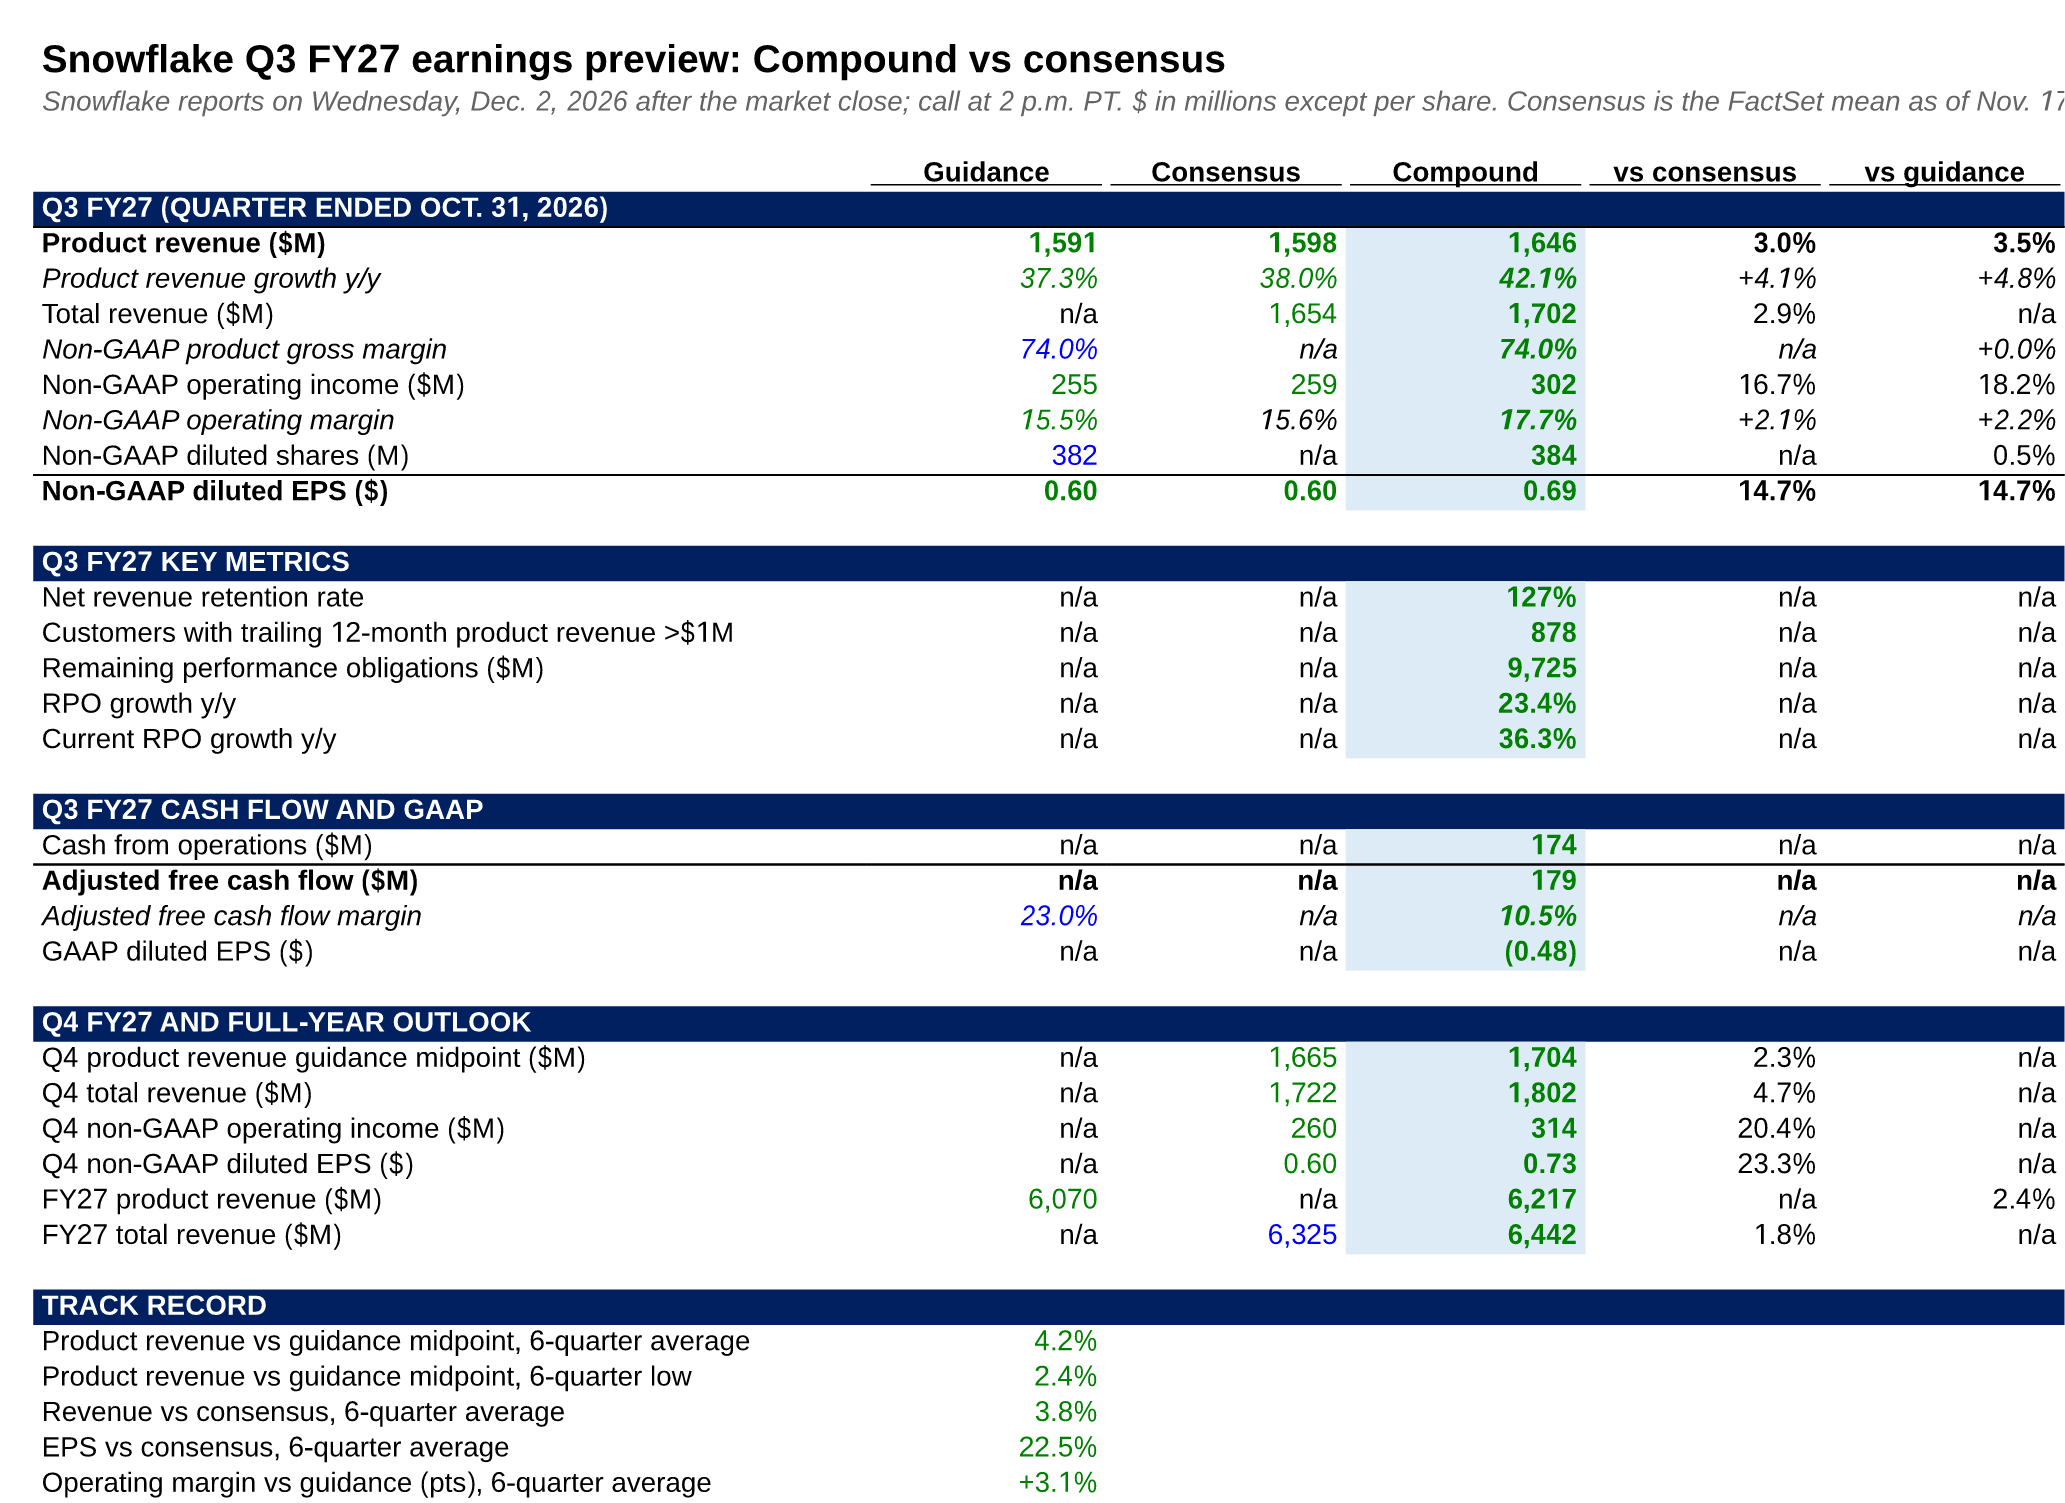
The Preview tab of the Excel model, which links every estimate to its drivers.
Remaining performance obligations
RPO fell to $9.21 billion at the end of Q1 and $9.00 billion at the end of Q2, from $9.77 billion at the end of fiscal 2026, according to Snowflake's 10-Q filings. Growth slowed to 30% in Q2 from 42% in Q4. Robins said customers favor fourth-quarter renewals and that Snowflake expects "bookings to be increasingly weighted towards the fourth quarter."
The part due within 12 months held up better. Snowflake expects about 54% of the $9.0 billion to be recognized in the next 12 months, which Robins said was about 42% more than the comparable estimate a year earlier. We forecast RPO of $9.72 billion in Q3, up 23% from a year earlier, and current RPO of $5.15 billion, up 36%. Net revenue retention was 126% in Q2; we forecast 127%.
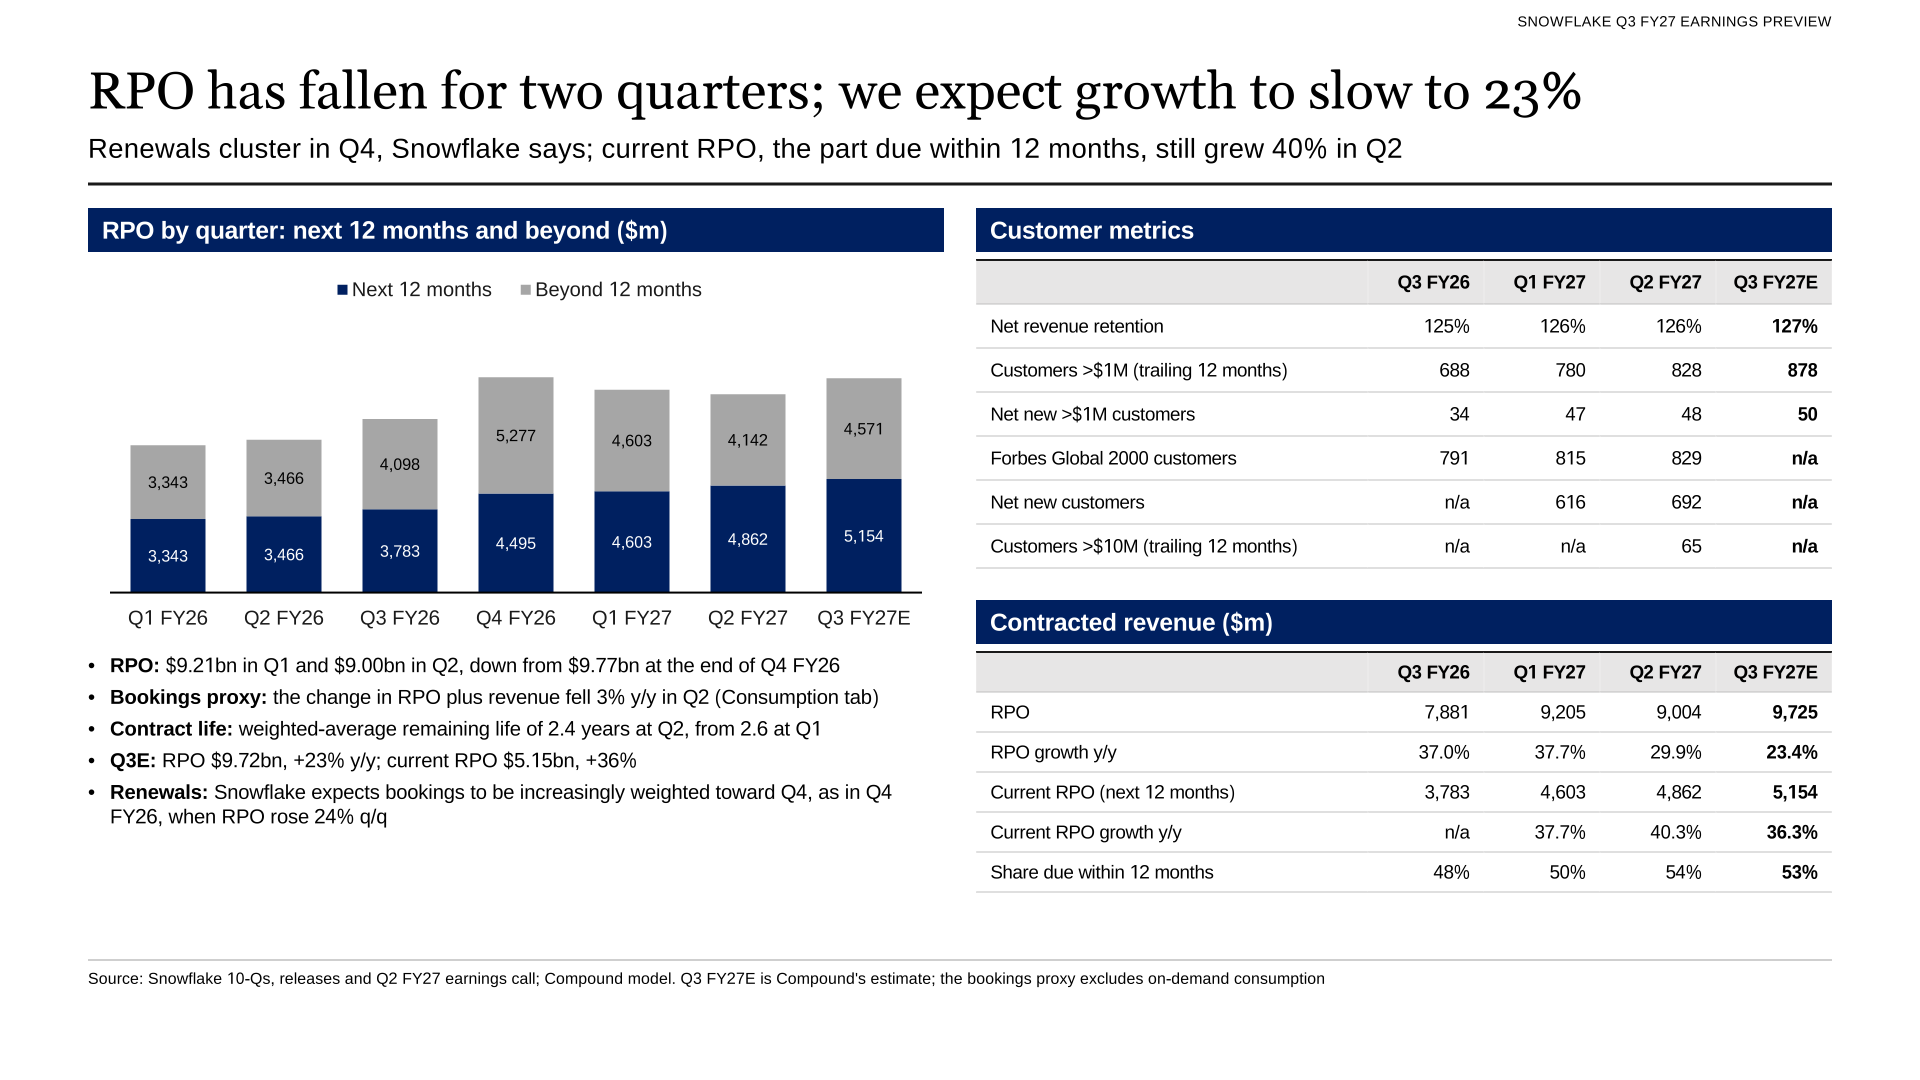
RPO by quarter, split by the share Snowflake expects to recognize within 12 months.
Q4 guidance
FactSet consensus for fourth-quarter revenue is $1.722 billion, which implies about $1.665 billion of product revenue. The current full-year guide of $6.07 billion implies about $1.653 billion. Snowflake's fourth-quarter guide a year ago was 3.4% above third-quarter product revenue; its last two guides were 6.2% and 6.6% above the prior quarter. A 3.5% step on our Q3 estimate gives a guidance midpoint of about $1.704 billion, which would lift full-year product revenue guidance to about $6.18 billion.
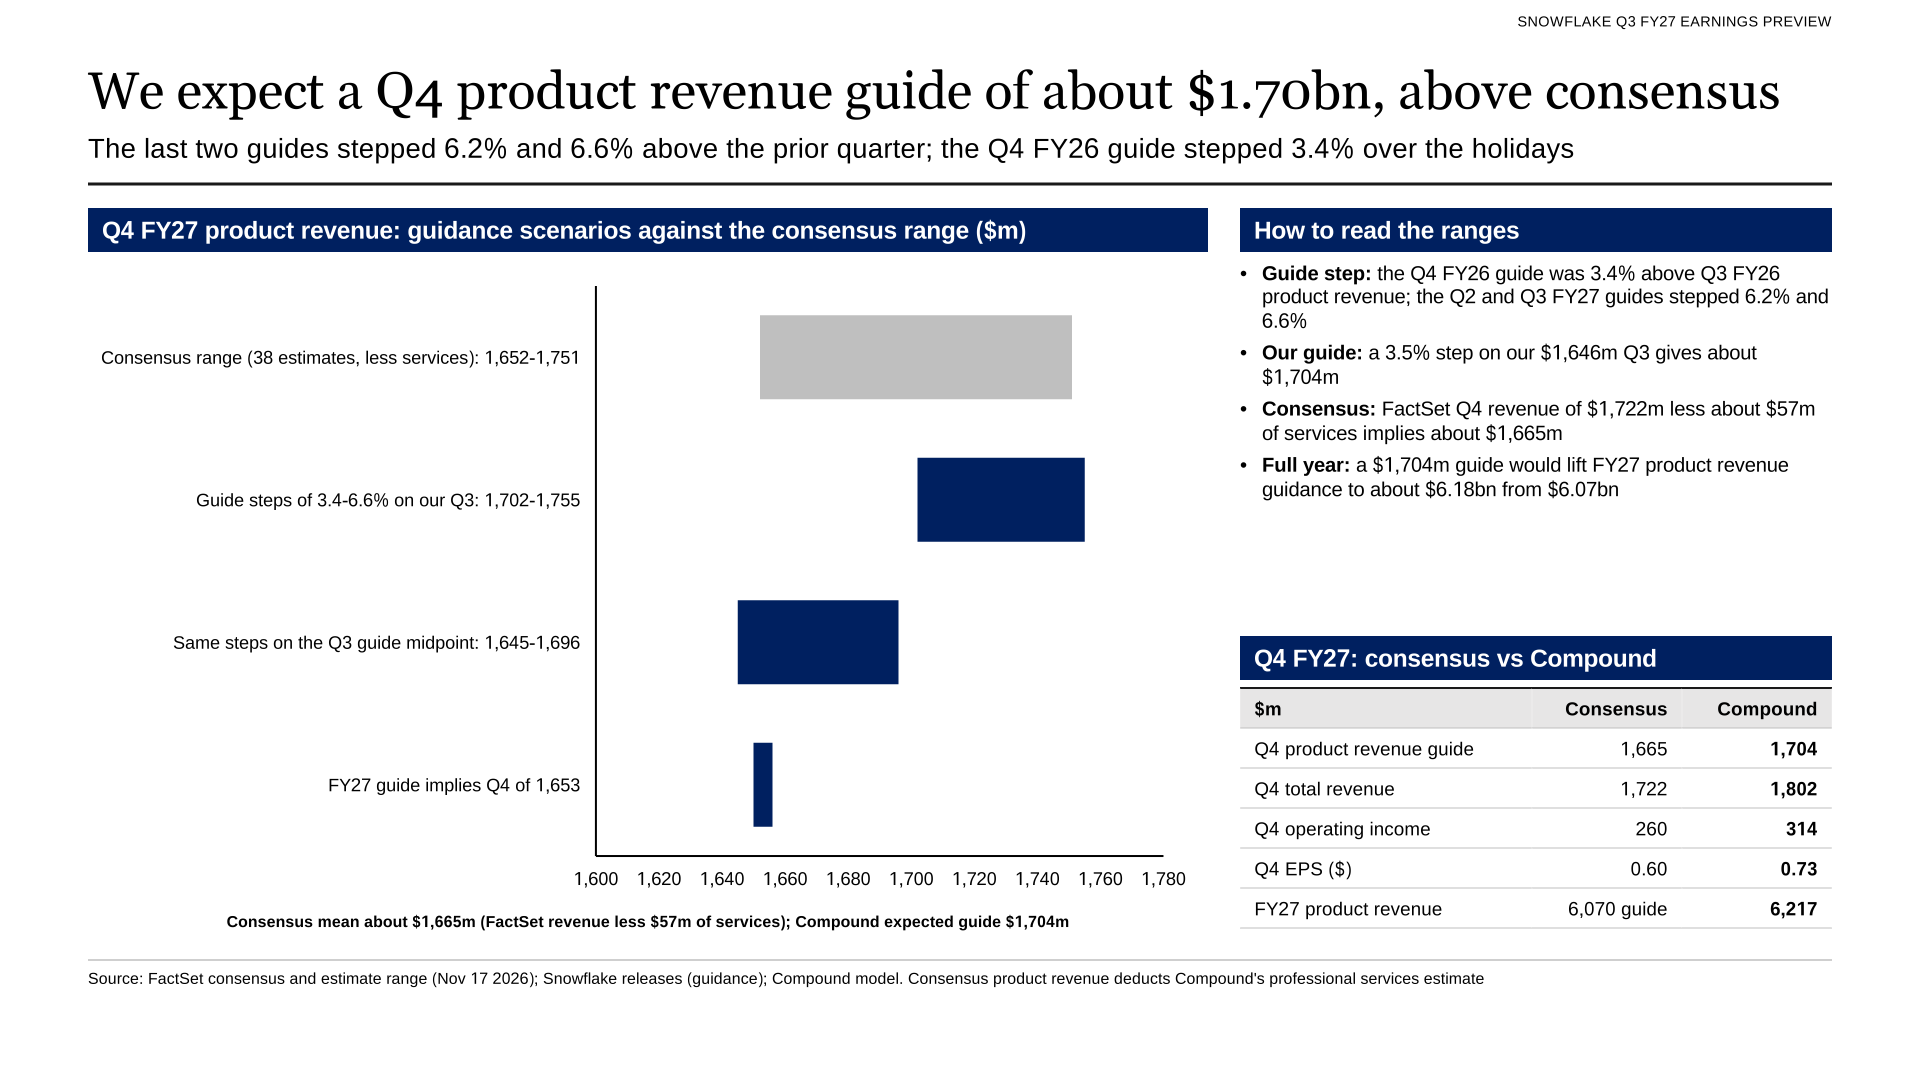
Guidance scenarios against the consensus range for Q4 product revenue.
Cash flow
We forecast third-quarter adjusted free cash flow of $179 million, 10.5% of revenue, against $136 million a year earlier. Snowflake collects most of its annual billings in the fourth quarter, when adjusted free cash flow was $782 million last year. Our quarters add to $1.51 billion for fiscal 2027, 23.4% of revenue, against guidance of 23%.
Snowflake priced $3.75 billion of 0% convertible notes due 2029 and 2031 on Sept. 28, according to an 8-K. From roughly $3.70 billion of net proceeds it paid about $383.5 million for capped calls and $548.3 million to repurchase part of its 2027 notes. At the initial conversion rates the new notes add about 7.6 million shares to the diluted count for a full quarter; we use 384 million for Q3, against the 382 million guided before the offering.
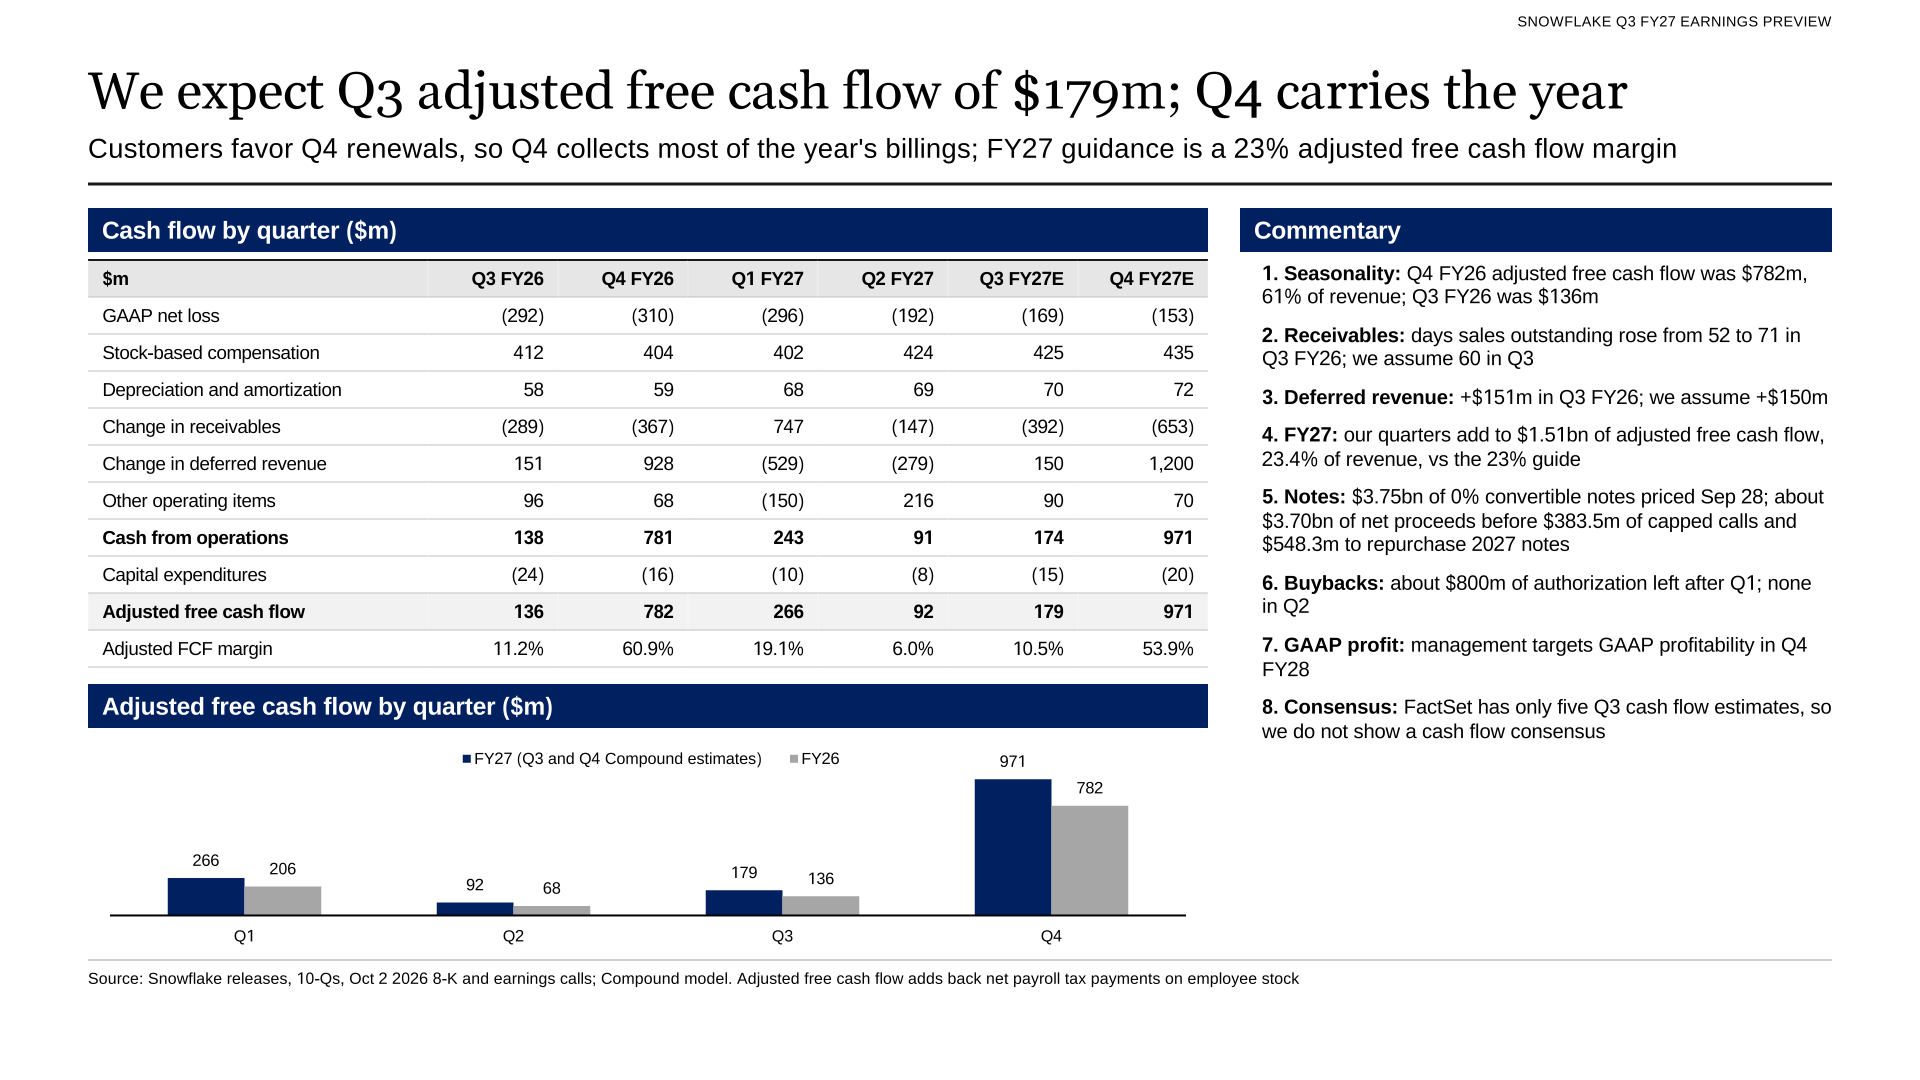
Customers favor Q4 renewals, so Q4 carries the year's cash flow.
The stock
SNOW's highest close since August was $368.89 on Oct. 9; it closed at $272.94 on Nov. 17, 26.0% lower, according to FactSet prices. Its lowest close in that period was $269.54 on Nov. 5. The FactSet mean price target is $440.57.
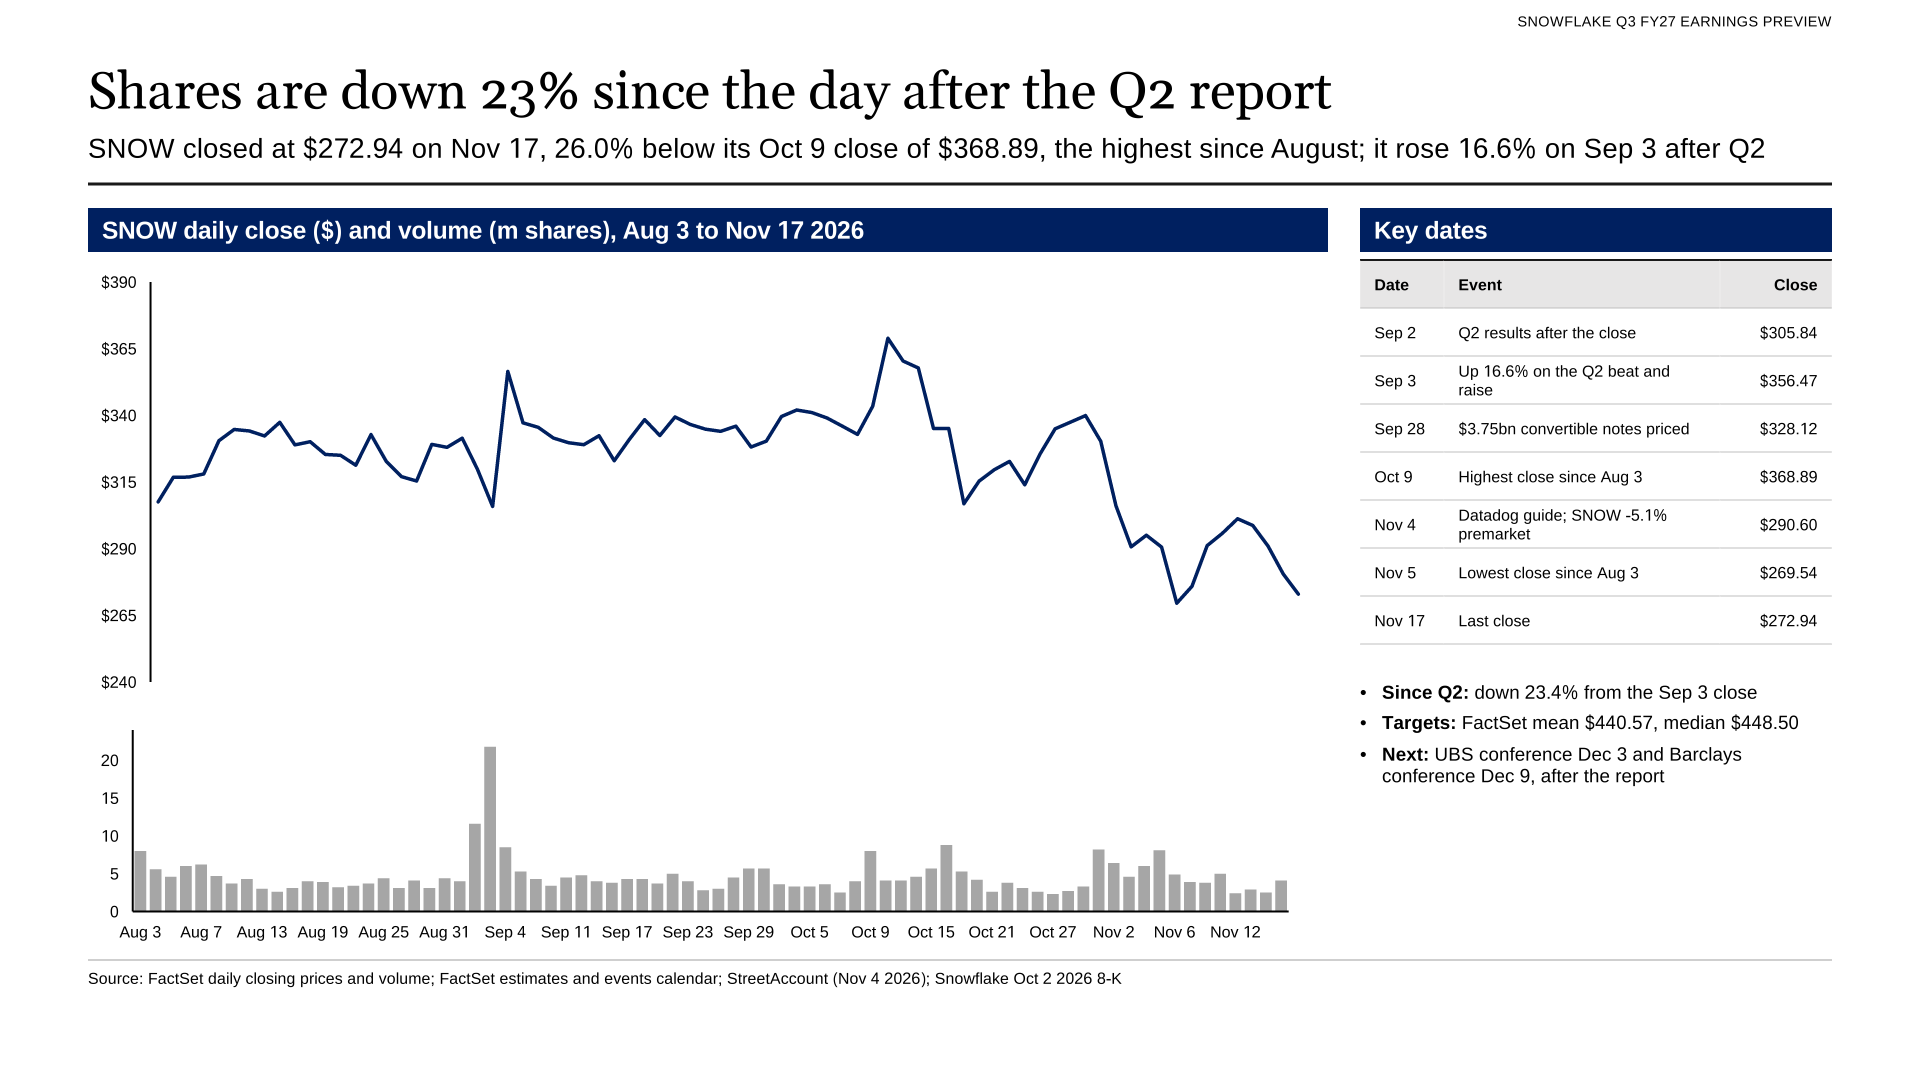
SNOW daily close and volume since August.
What to watch on Wednesday
- Product revenue against our $1.646 billion and the $1.5905 billion guidance midpoint; a beat under 2.4% would be the smallest in seven quarters.
- Fourth-quarter product revenue guidance against about $1.665 billion implied by consensus and our $1.704 billion.
- RPO after two quarterly declines; we forecast $9.72 billion.
- Non-GAAP product gross margin against 74.7% in Q2, as the AI mix rises.
- Non-GAAP operating margin against 15.5% guided and our 17.7%.
- Any AI revenue figure, and new Cortex Code and CoWork account counts.
- Snowflake presents at the UBS Technology and AI Conference on Dec. 3 and the Barclays Global Technology Conference on Dec. 9, according to FactSet's calendar.
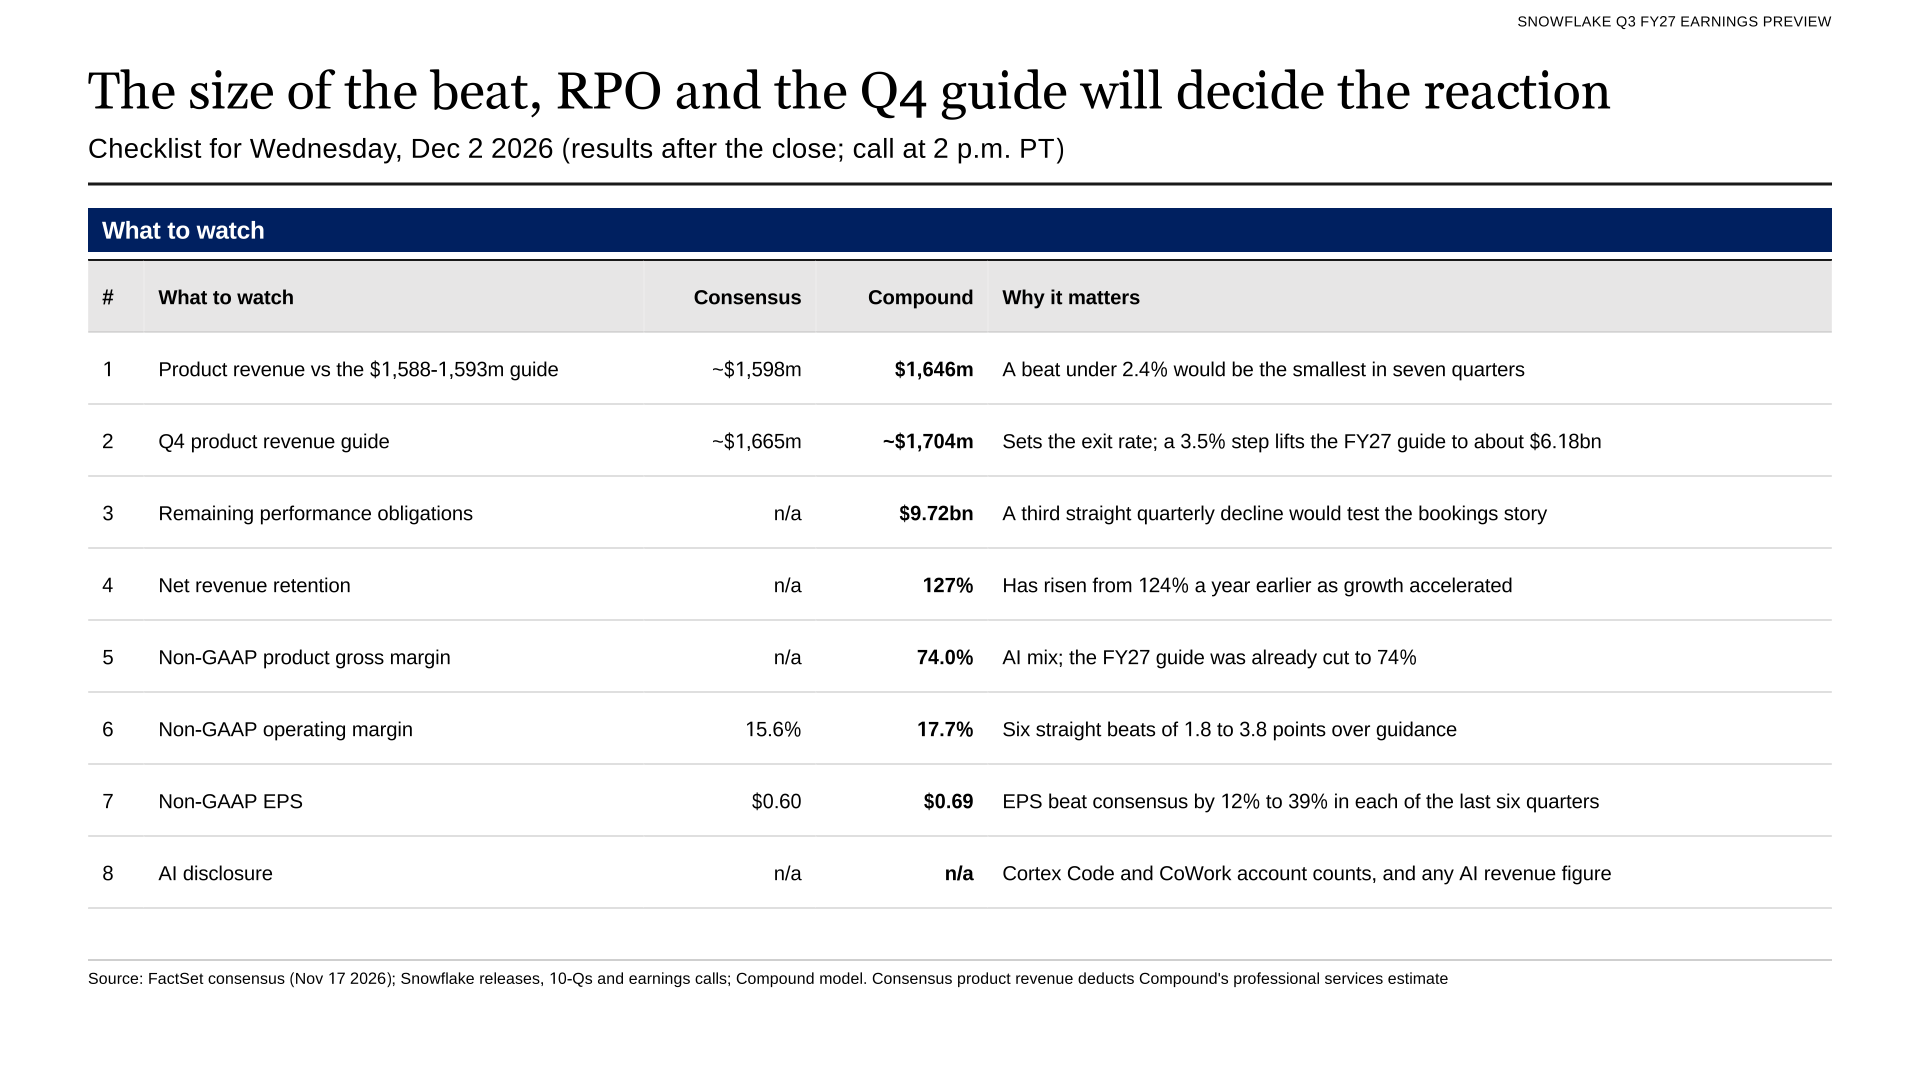
Eight tests for the report, with consensus and our estimate for each.
We will score this forecast against the reported numbers after the release on Dec. 2.
 Snowflake Q3 FY27 earnings preview deck (PowerPoint)The 11-page preview: executive summary, forecast against consensus, revenue build, margins and EPS sensitivity, Q4 guidance scenarios, AI and consumption, RPO and customers, the share price, cash flow and a checklist for the call.Download · Free
 Snowflake Q3 FY27 earnings model (Excel)Quarterly model from Q1 FY26: product revenue and key metrics, non-GAAP and GAAP income statements, cash flow, balance sheet and working capital, guidance and consensus track record, Compound's Q3 and Q4 estimates, native Excel sensitivity tables and a consumption and AI tab.Download · Free
 Snowflake Q3 FY27 earnings preview deck (PDF)The same 11 pages as a PDF.Download · Free
More from Compound News
Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Read article →
Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Read article →
CrowdStrike Q3 Earnings Preview: $0.33 EPS vs $0.31 Consensus
CrowdStrike reports Tuesday after the close. Our model puts net new ARR 9% above guidance, revenue 2.0% above consensus at $1.56 billion and EPS at $0.33 against $0.31.
Read article →