Deere Q4 Earnings Preview: $4.13 EPS vs $4.03 Consensus
Deere reports Wednesday before the open. Our model has fiscal fourth-quarter EPS of $4.13 against a $4.03 consensus, and we expect Deere's first fiscal 2027 net income guide of about $5.0 billion to $5.5 billion, below the $5.91 billion consensus.
Deere reports fiscal fourth-quarter results before the market opens on Wednesday, Nov. 25, with the call at 9:00 a.m. CT, according to the company's Nov. 11 announcement. The quarter ended Nov. 1.
Compound's model forecasts EPS of $4.13, 2.5% above the FactSet consensus of $4.03 and above the $3.95 implied by the midpoint of Deere's full-year guidance. We forecast net income of $1.12 billion against a $1.09 billion consensus, and equipment net sales of $10.38 billion, in line with the $10.40 billion consensus.
The larger number on Wednesday is Deere's first fiscal 2027 outlook. We expect a net income range of about $5.0 billion to $5.5 billion. The FactSet consensus is $5.91 billion.
Deere shares closed at $649.23 on Nov. 17, up 36% from a year earlier and 8.5% below their Sept. 23 closing high of $709.48, according to FactSet.
We built an 11-slide earnings preview deck on the model. The slides below come from it, and the deck and the model are free to download at the end.
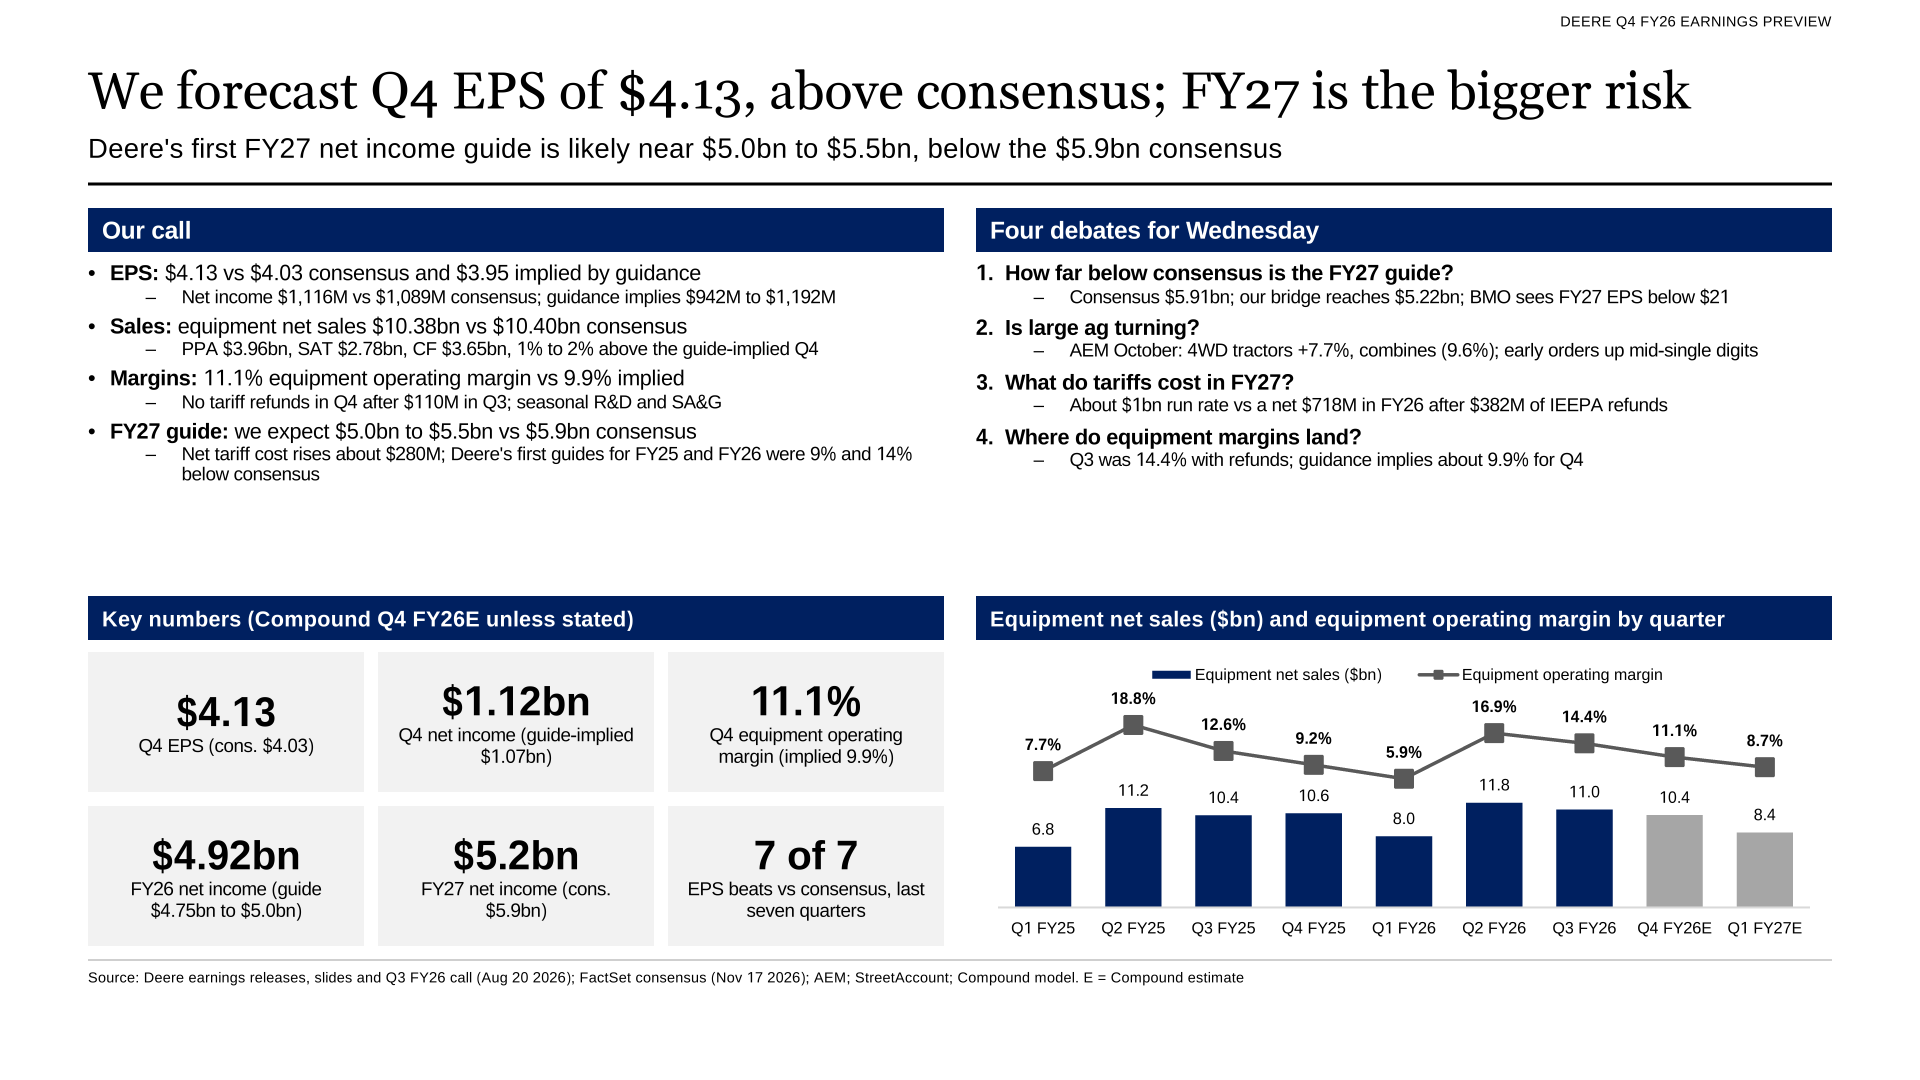
Our Q4 call and the four debates for Wednesday. Slide 2.
Forecast vs consensus
| Q4 FY26 | Guidance-implied | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Equipment net sales | $10.22B | $10.40B | $10.38B | -0.2% |
| Production & Precision Ag | $3.92B | n/a | $3.96B | n/a |
| Small Ag & Turf | $2.72B | n/a | $2.78B | n/a |
| Construction & Forestry | $3.58B | n/a | $3.65B | n/a |
| Equipment operating margin | 9.9% | n/a | 11.1% | n/a |
| Net income | $1.07B ($0.94B to $1.19B) | $1.09B | $1.12B | +2.4% |
| EPS | $3.95 | $4.03 | $4.13 | +2.5% |
| FY26 net income | $4.75B to $5.00B | $4.90B | $4.92B | +0.6% |
| FY27 net income | Due Nov. 25 | $5.91B | $5.0B to $5.5B | -11.6% at midpoint |
Consensus is the FactSet mean as of Nov. 17. Guidance-implied figures take Deere's Aug. 20 full-year outlook less nine-month results. Net income is attributable to Deere & Company.
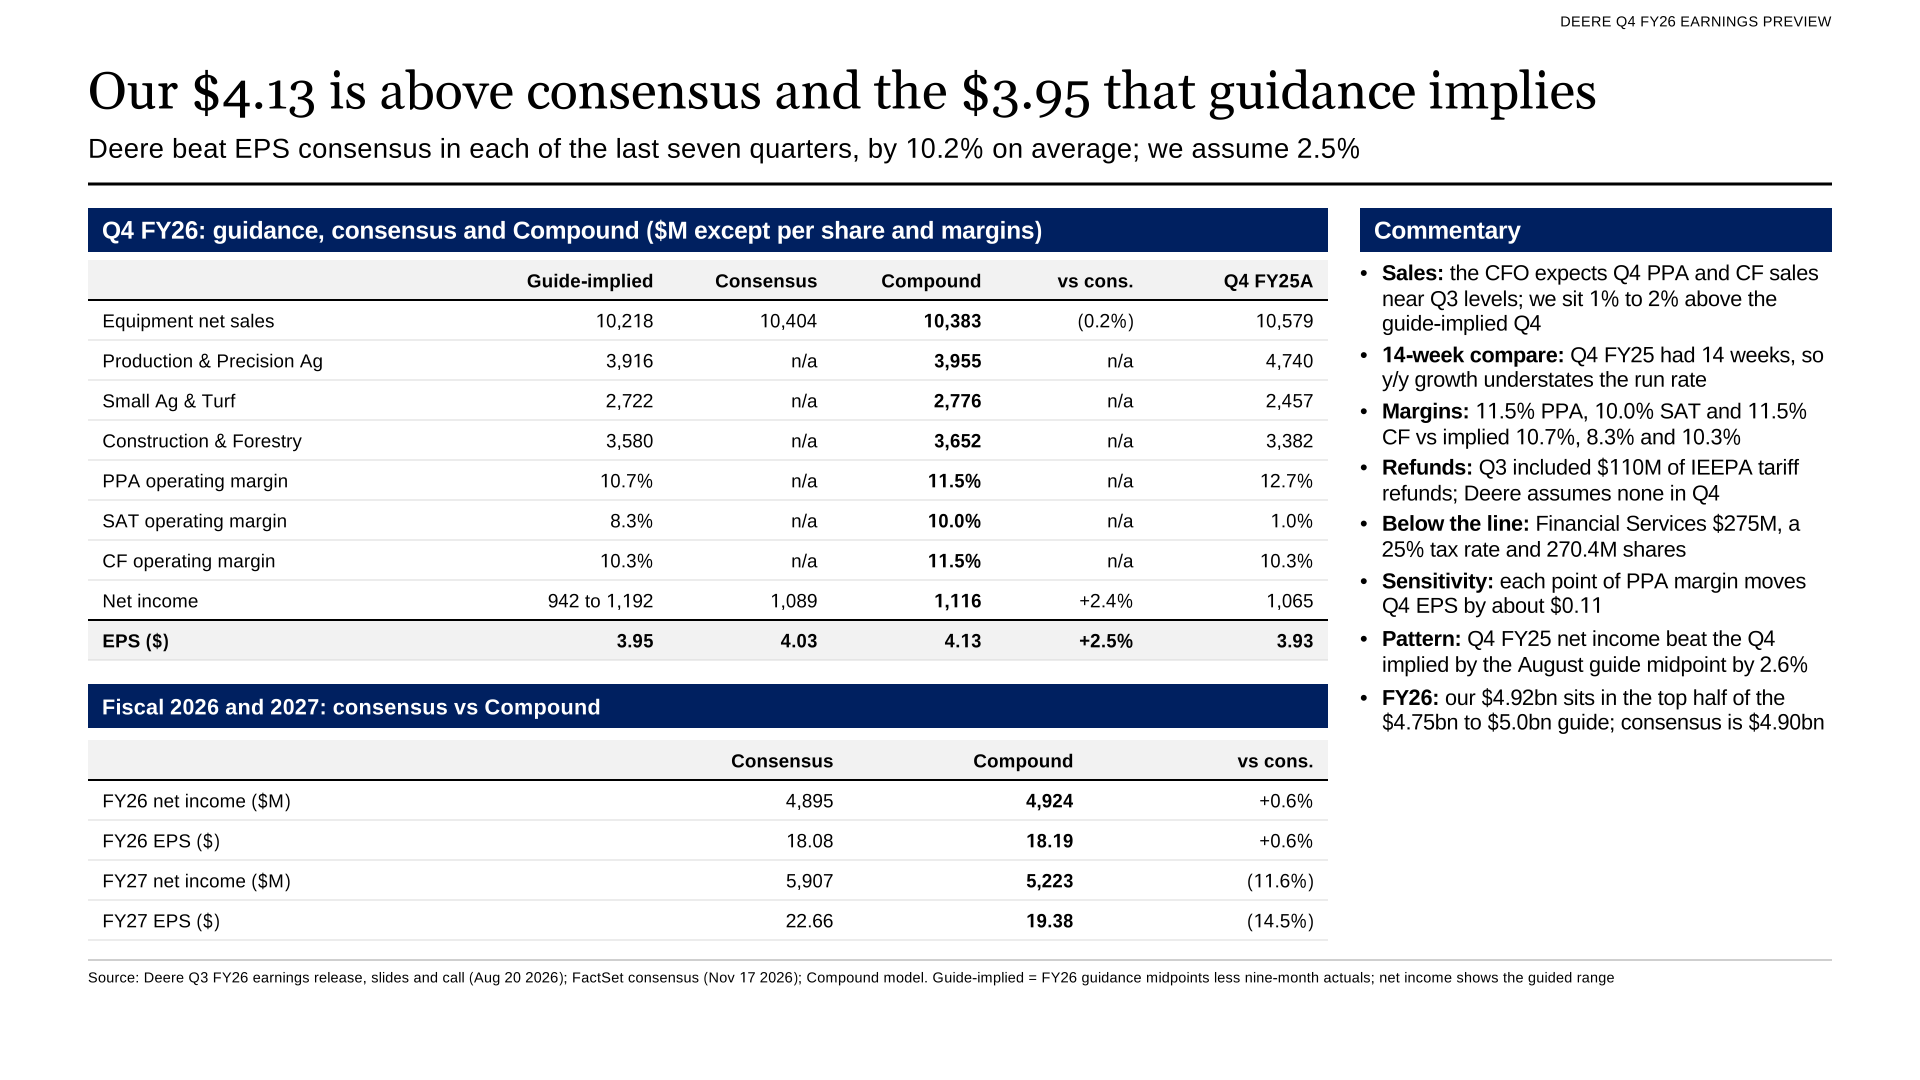
Our $4.13 is above consensus and the $3.95 that guidance implies. Slide 3.
How we built the forecast
Deere guides only the full year, so the fourth quarter is what is left of the outlook after nine months. In its Aug. 20 release, Deere guided fiscal 2026 net sales down about 10% for Production & Precision Ag, up about 15% for Small Ag & Turf and up about 20% for Construction & Forestry. Its slides put the segment operating margins at 11% to 12%, 14.5% to 15.5% and 10.5% to 11.5%. Against nine-month results, that leaves fourth-quarter equipment net sales of $10.22 billion and an equipment operating margin of about 9.9%.
We put sales 1% to 2% above those figures. CFO Brent Norwood told analysts in August that fourth-quarter sales in Production & Precision Ag and Construction & Forestry should be similar to the third quarter's. Construction & Forestry had four to five months of orders on hand, more than the usual two to three, the company said on the call.
We model segment margins of 11.5%, 10.0% and 11.5%, against the implied 10.7%, 8.3% and 10.3%, for an equipment operating margin of 11.1%. Two things pull the quarter below the third quarter's 14.4%: the third quarter included $110 million of tariff refunds that Deere does not expect to repeat, and Production & Precision Ag and Small Ag & Turf book a seasonal high in R&D and selling costs in the fourth quarter. Each point of Production & Precision Ag margin moves our EPS by about $0.11.
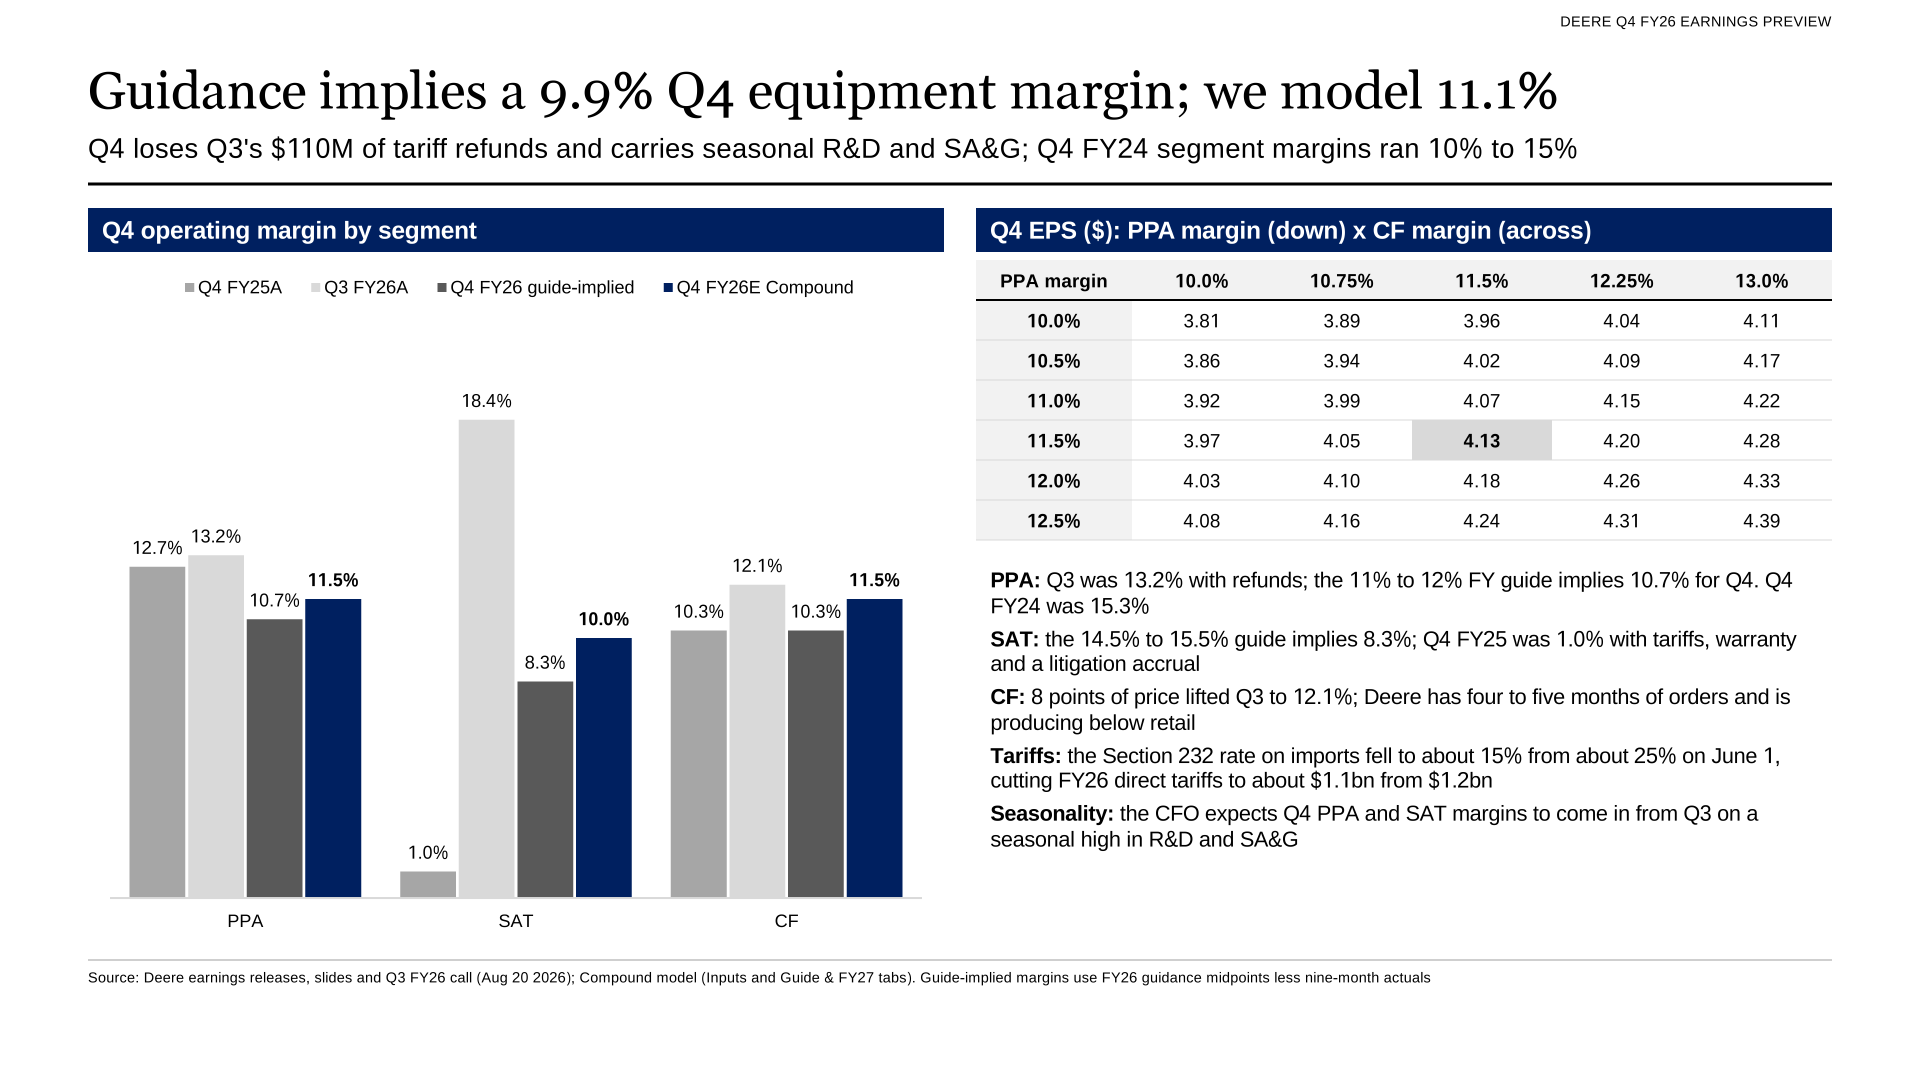
Guidance implies a 9.9% Q4 equipment margin; we model 11.1%. Slide 4.
Track record
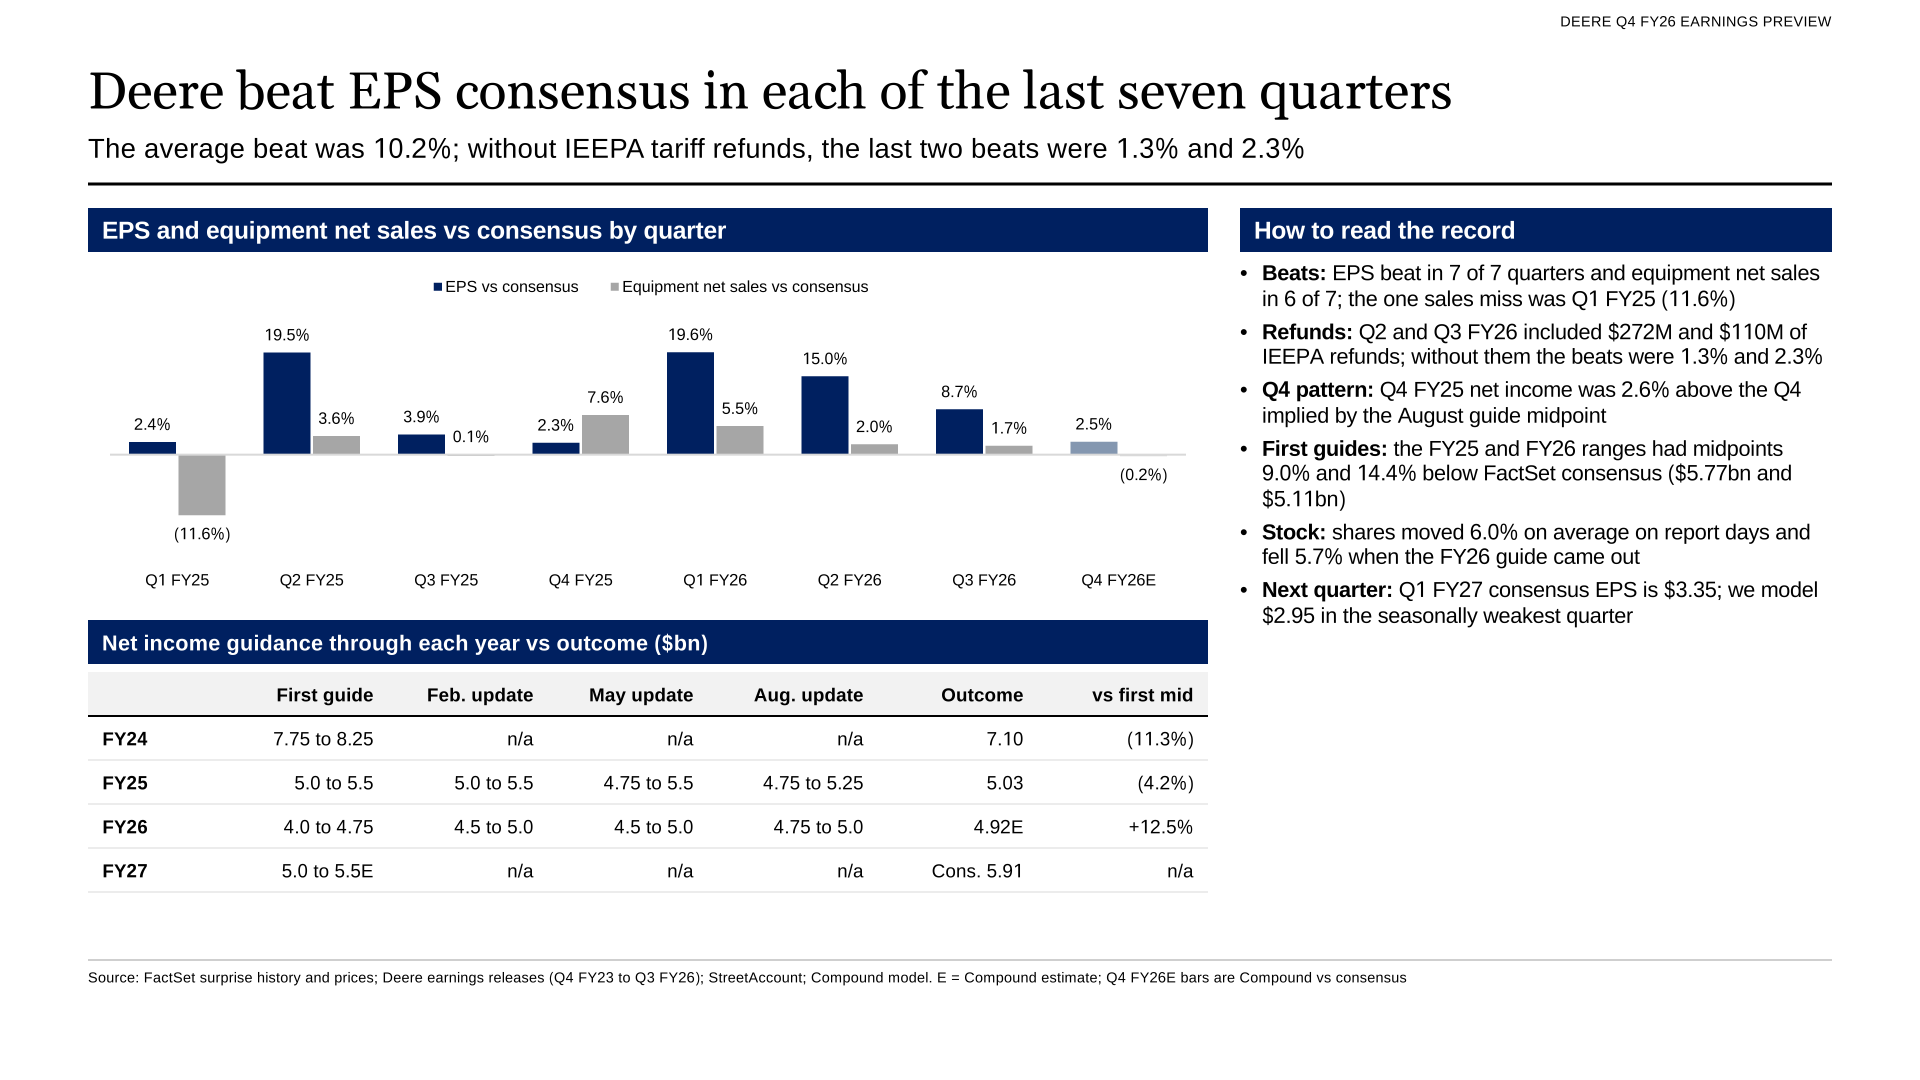
Deere beat the FactSet EPS consensus in each of the last seven quarters, by 10.2% on average, and beat the equipment net sales consensus in six of the seven. The two most recent beats included refunds of tariffs imposed under the International Emergency Economic Powers Act, $272 million in the second quarter and $110 million in the third. Without them, the beats were 1.3% and 2.3%. Our forecast is a 2.5% beat.
In last year's fourth quarter, net income came in 2.6% above the figure implied by the midpoint of Deere's August guidance.
Deere beat EPS consensus in each of the last seven quarters. Slide 5.
Large ag demand
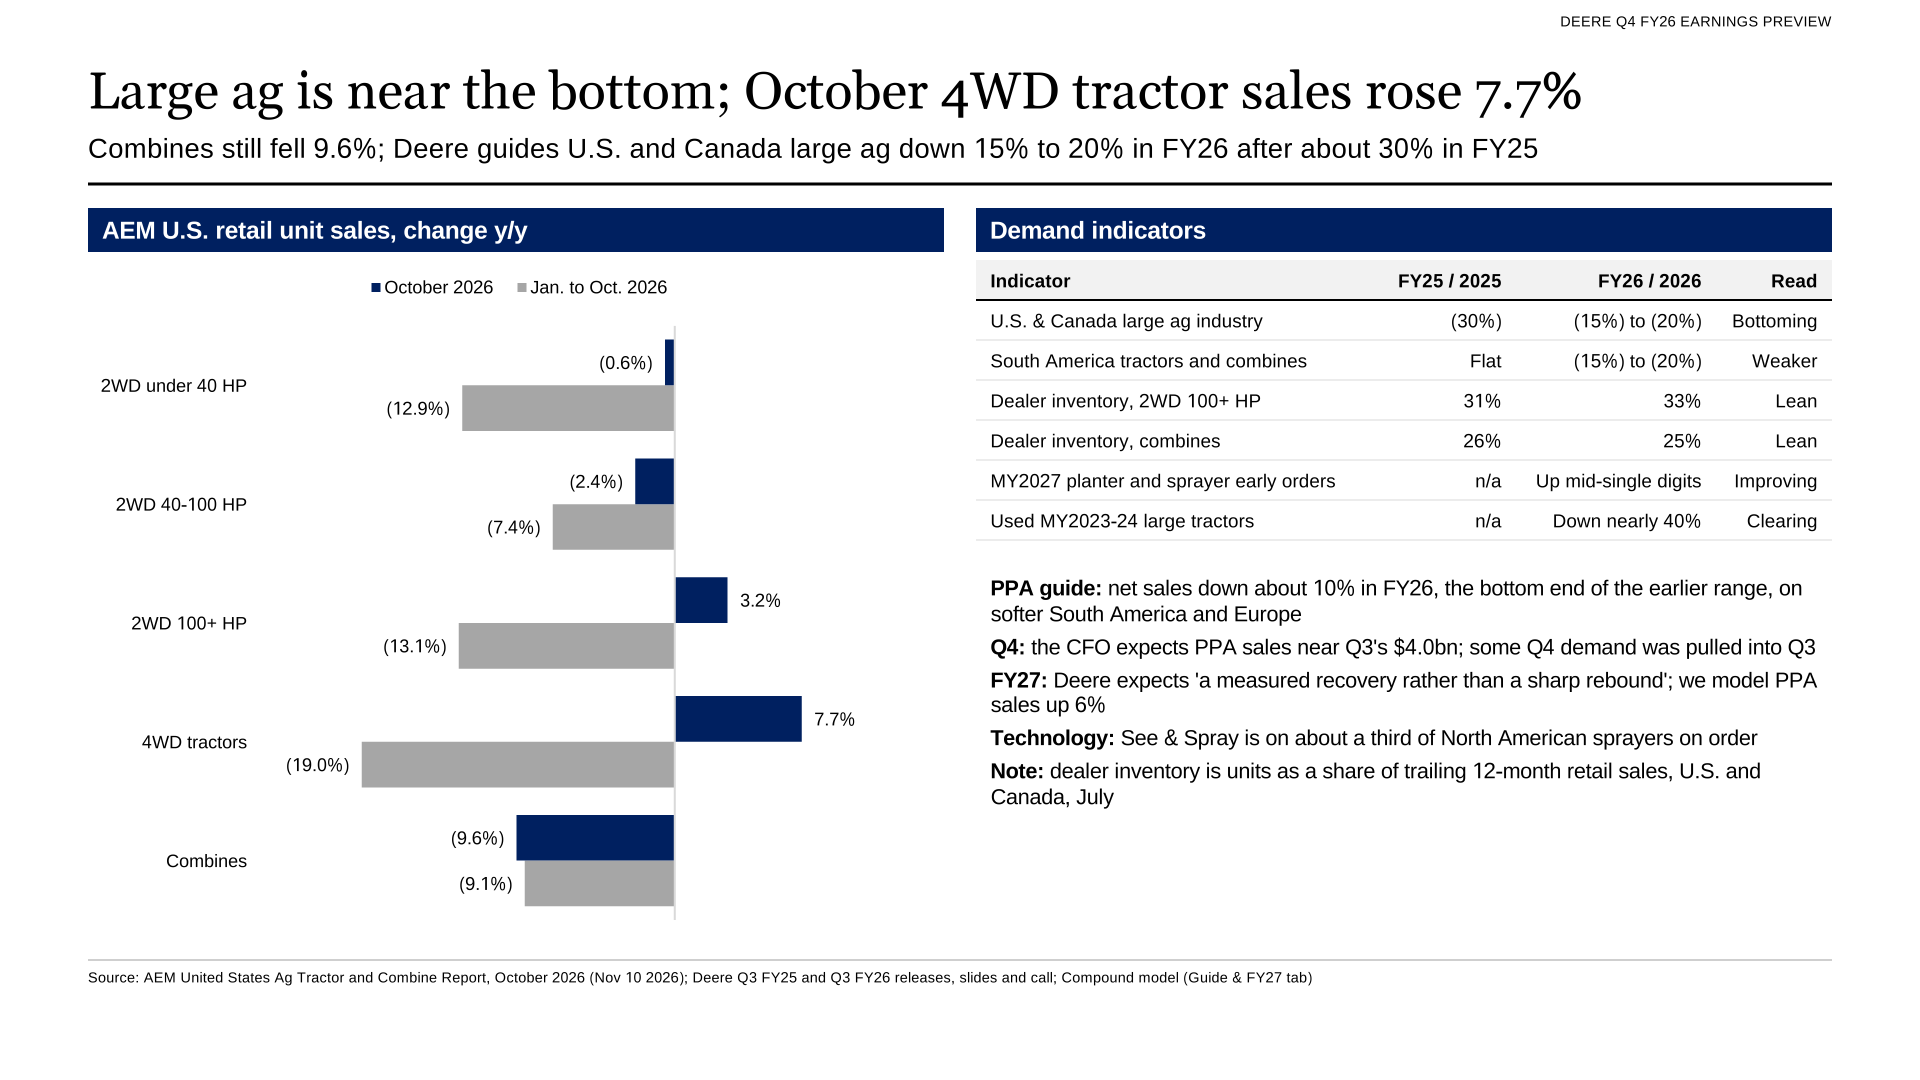
U.S. retail sales of four-wheel-drive tractors rose 7.7% in October from a year earlier and sales of two-wheel-drive tractors of 100 horsepower and more rose 3.2%, the Association of Equipment Manufacturers reported Nov. 10. Combine sales fell 9.6%. Through October, four-wheel-drive tractor sales were down 19.0% and combine sales 9.1%.
Deere expects U.S. and Canada large ag industry sales to fall 15% to 20% in fiscal 2026, after a drop of about 30% in fiscal 2025, and in August it cut its South America outlook to a 15% to 20% decline. Early orders for model year 2027 planters and sprayers were up mid-single digits, the company said, and it described the outlook as "a measured recovery rather than a sharp rebound in 2027."
Large ag is near the bottom; October 4WD tractor sales rose 7.7%. Slide 6.
Tariffs
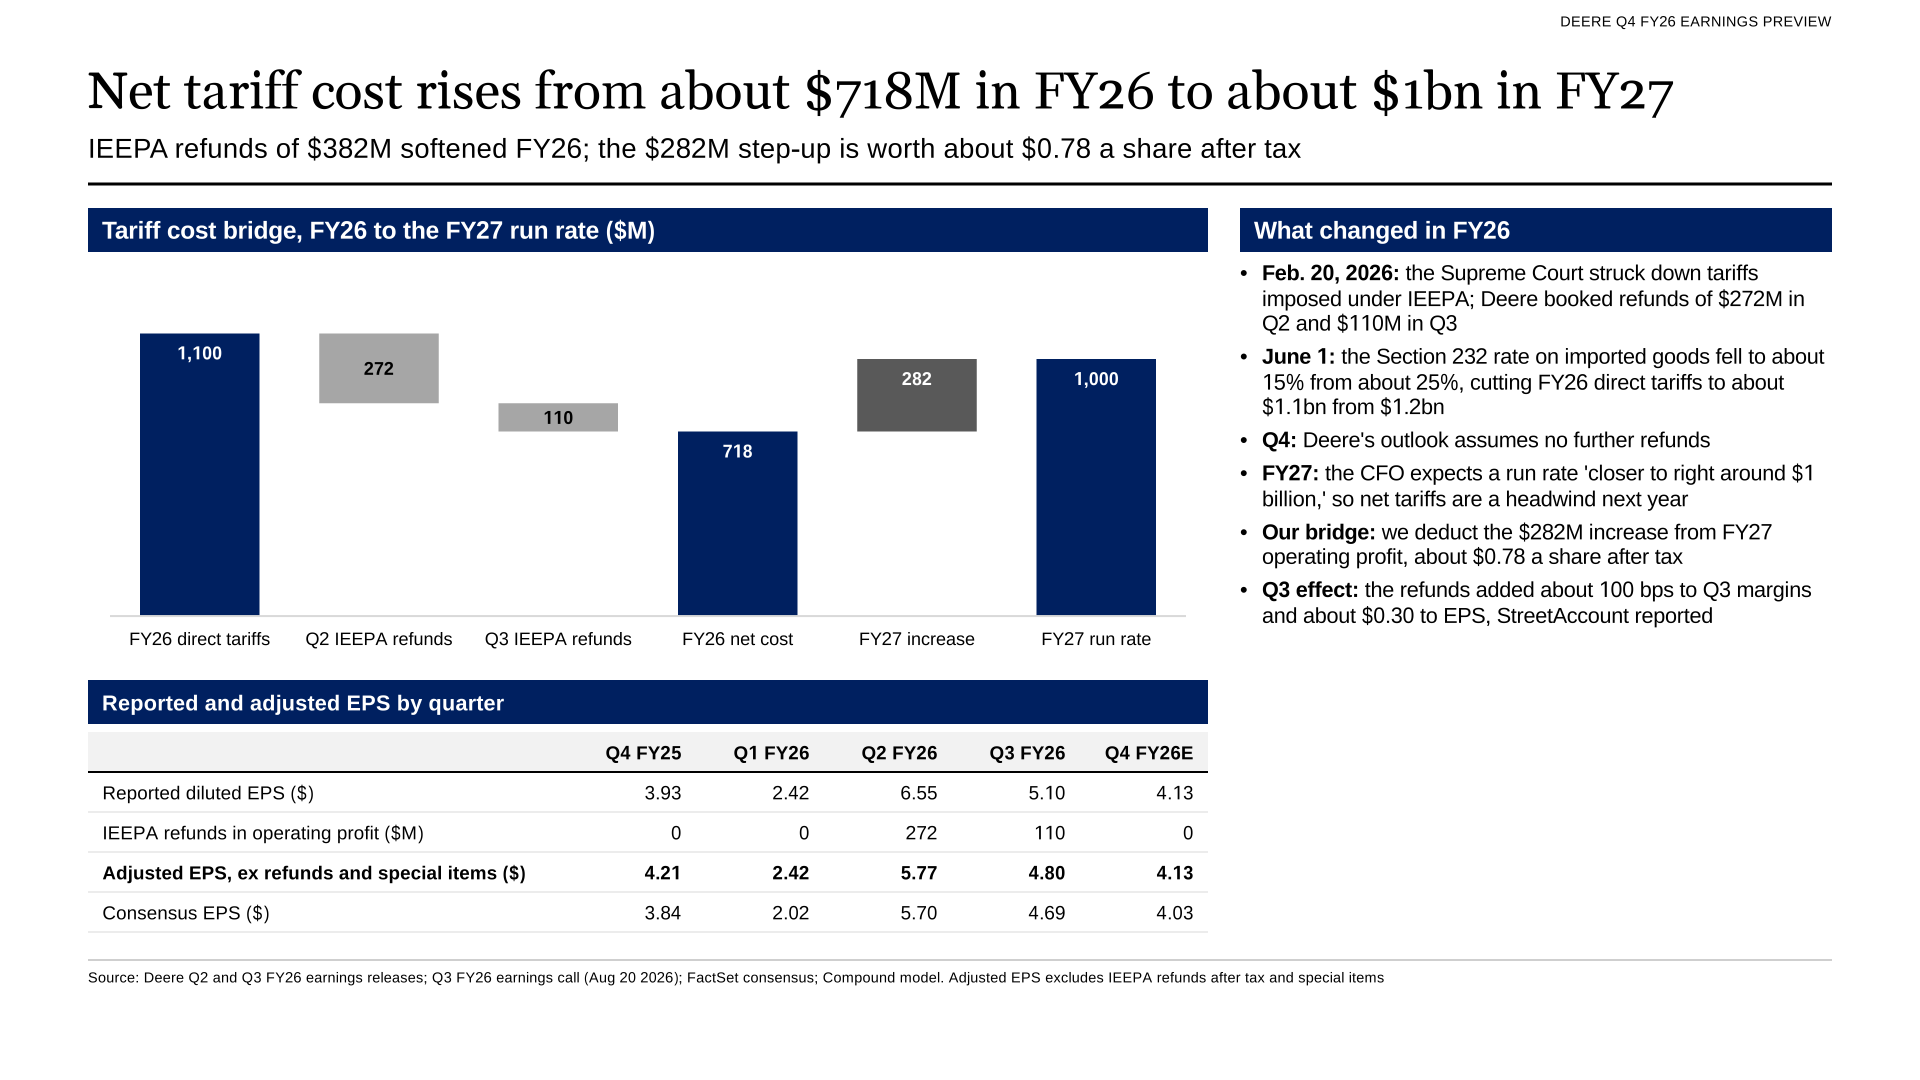
Deere expects about $1.1 billion of direct tariff expense in fiscal 2026, down from $1.2 billion after the Section 232 rate on its imports fell to about 15% from about 25% on June 1, the company said in August. The Supreme Court struck down tariffs imposed under IEEPA on Feb. 20, and Deere has booked $382 million of refunds this year. Its outlook assumes no more in the fourth quarter.
Norwood put the fiscal 2026 net tariff cost at about $750 million; our count from the disclosed figures is $718 million. He said fiscal 2027 would run "closer to right around $1 billion for the year." On our numbers that is a $282 million increase, about $0.78 a share after tax.
Net tariff cost rises from about $718 million in FY26 to about $1 billion in FY27. Slide 7.
Fiscal 2027 guidance
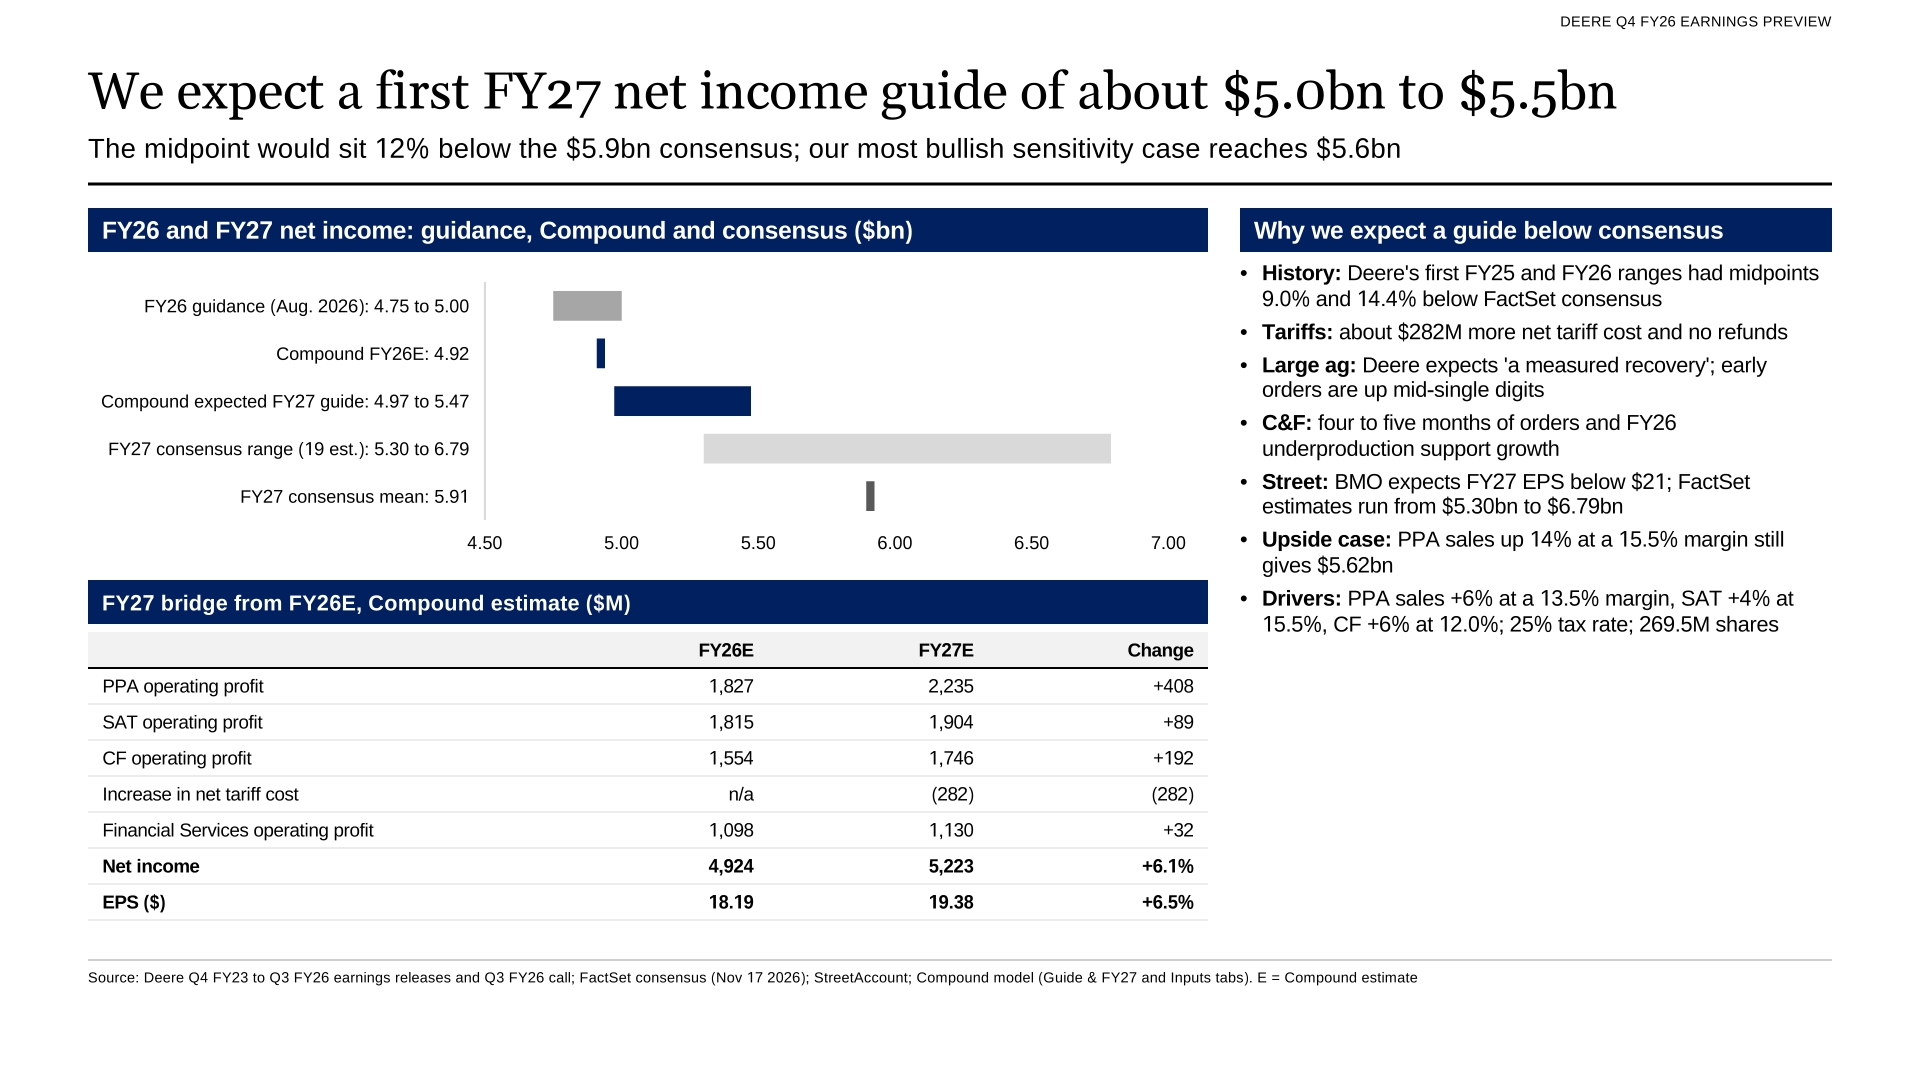
We expect Deere to guide fiscal 2027 net income to about $5.0 billion to $5.5 billion. The FactSet consensus is $5.91 billion, with estimates from $5.30 billion to $6.79 billion. Consensus EPS is $22.66; our estimate is $19.38.
Deere's first guide has come in below consensus in each of the last two years, according to StreetAccount. In November 2024 it guided fiscal 2025 net income to $5.0 billion to $5.5 billion against a FactSet consensus of $5.77 billion. In November 2025 it guided fiscal 2026 to $4.0 billion to $4.75 billion against $5.11 billion. The midpoints were 9.0% and 14.4% below consensus, and the shares fell 5.7% on the day of the fiscal 2026 guide.
Our bridge starts from fiscal 2026 net income of $4.92 billion. It grows Production & Precision Ag and Construction & Forestry sales 6% and Small Ag & Turf 4%, lifts the Production & Precision Ag margin to 13.5% from about 11.7%, and deducts the higher tariff bill. With Production & Precision Ag sales up 14% at a 15.5% margin, the model reaches $5.62 billion. BMO analyst Joel Jackson said in August that he expects fiscal 2027 EPS below $21, StreetAccount reported.
We expect a first FY27 net income guide of about $5.0 billion to $5.5 billion. Slide 8.
Cash flow
Deere guided fiscal 2026 equipment operations cash flow to $5.0 billion to $5.5 billion and generated $4.01 billion in the first nine months. We model $1.35 billion in the fourth quarter, for $5.36 billion for the year. Inventory was $7.81 billion at the end of the third quarter, and Deere said it is producing below retail demand in Production & Precision Ag and Construction & Forestry.
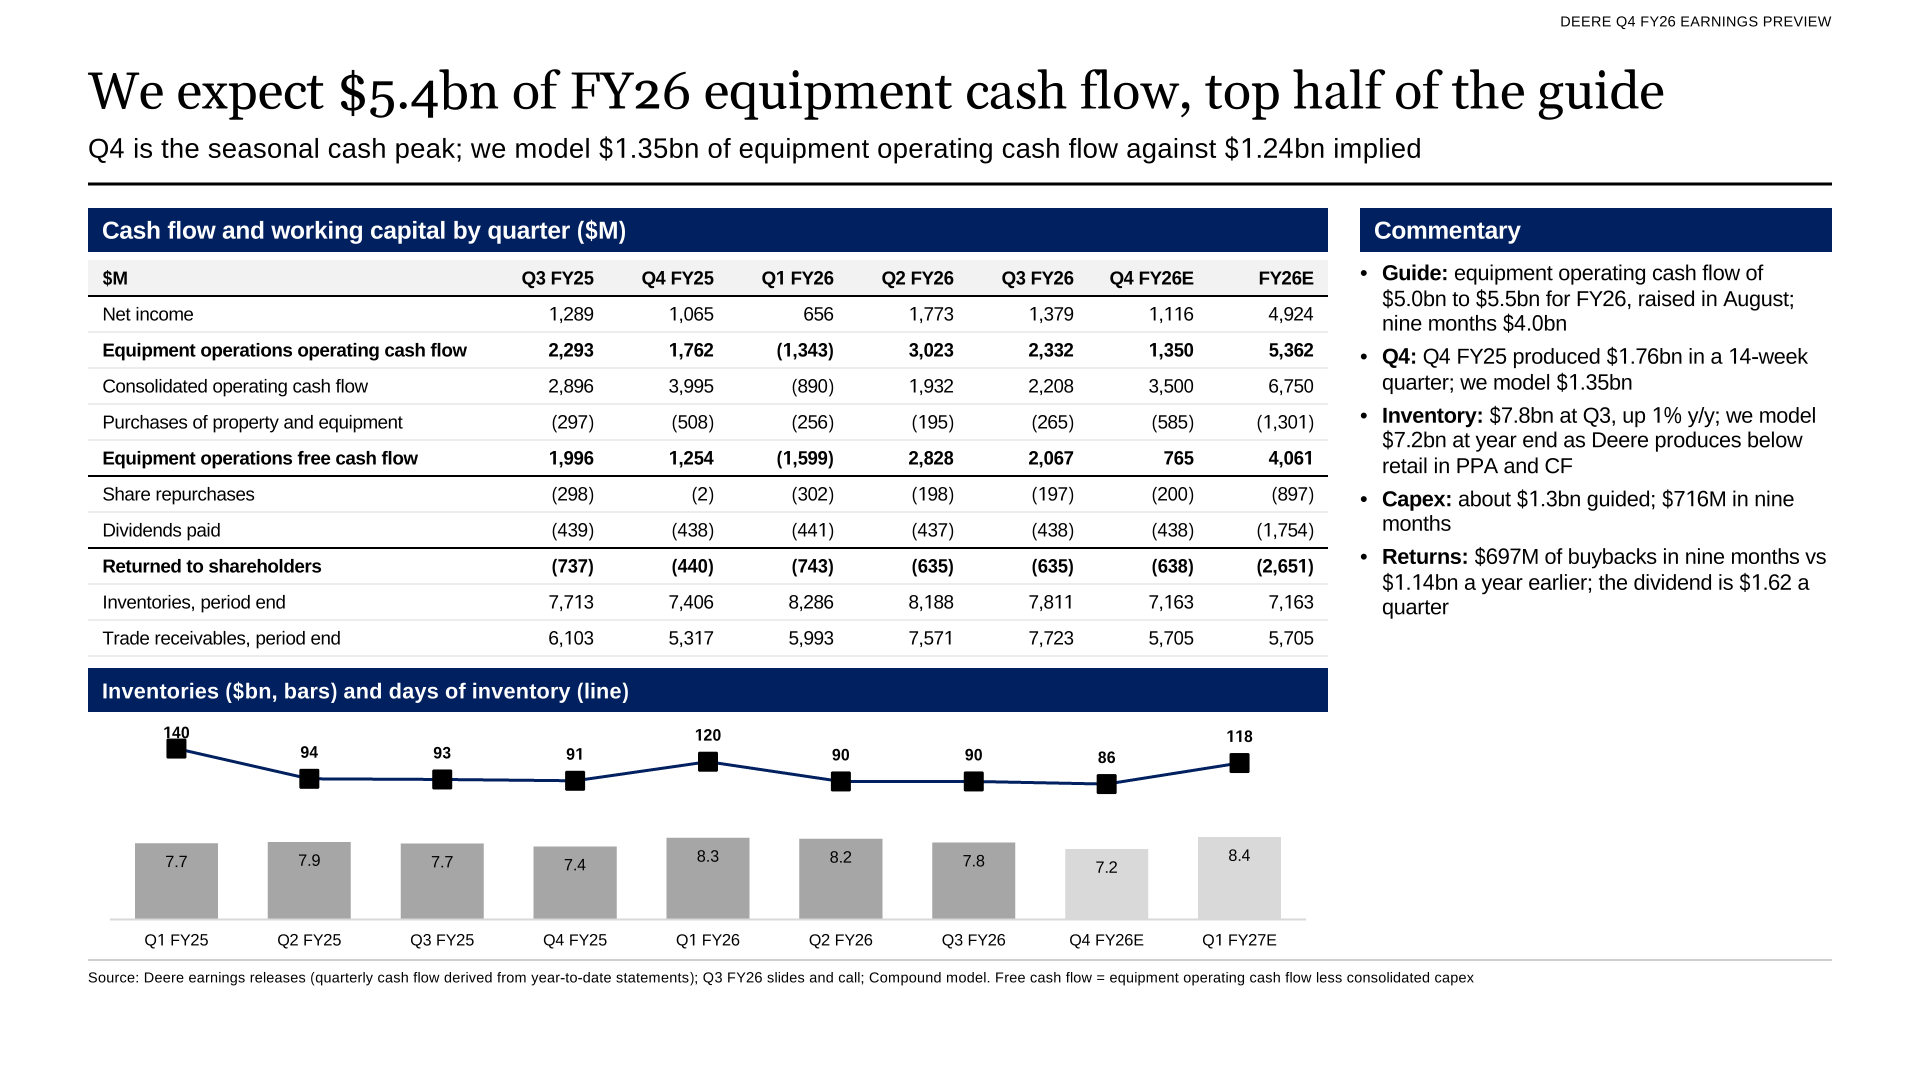
We expect $5.4 billion of FY26 equipment cash flow, in the top half of the guide. Slide 9.
Share price
Deere shares moved 6.0% on average on the last seven report days, according to FactSet. They rose 11.6% on the first-quarter report in February and fell 5.7% when the fiscal 2026 guide came out a year ago. On Oct. 7 they fell 3.8% after the Federal Trade Commission opened a probe of agricultural equipment makers, StreetAccount reported. On Nov. 4, Deere said it will close its Ottumwa, Iowa, factory after moving windrower and baler production to Des Moines, StreetAccount reported. The FactSet mean price target is $701.
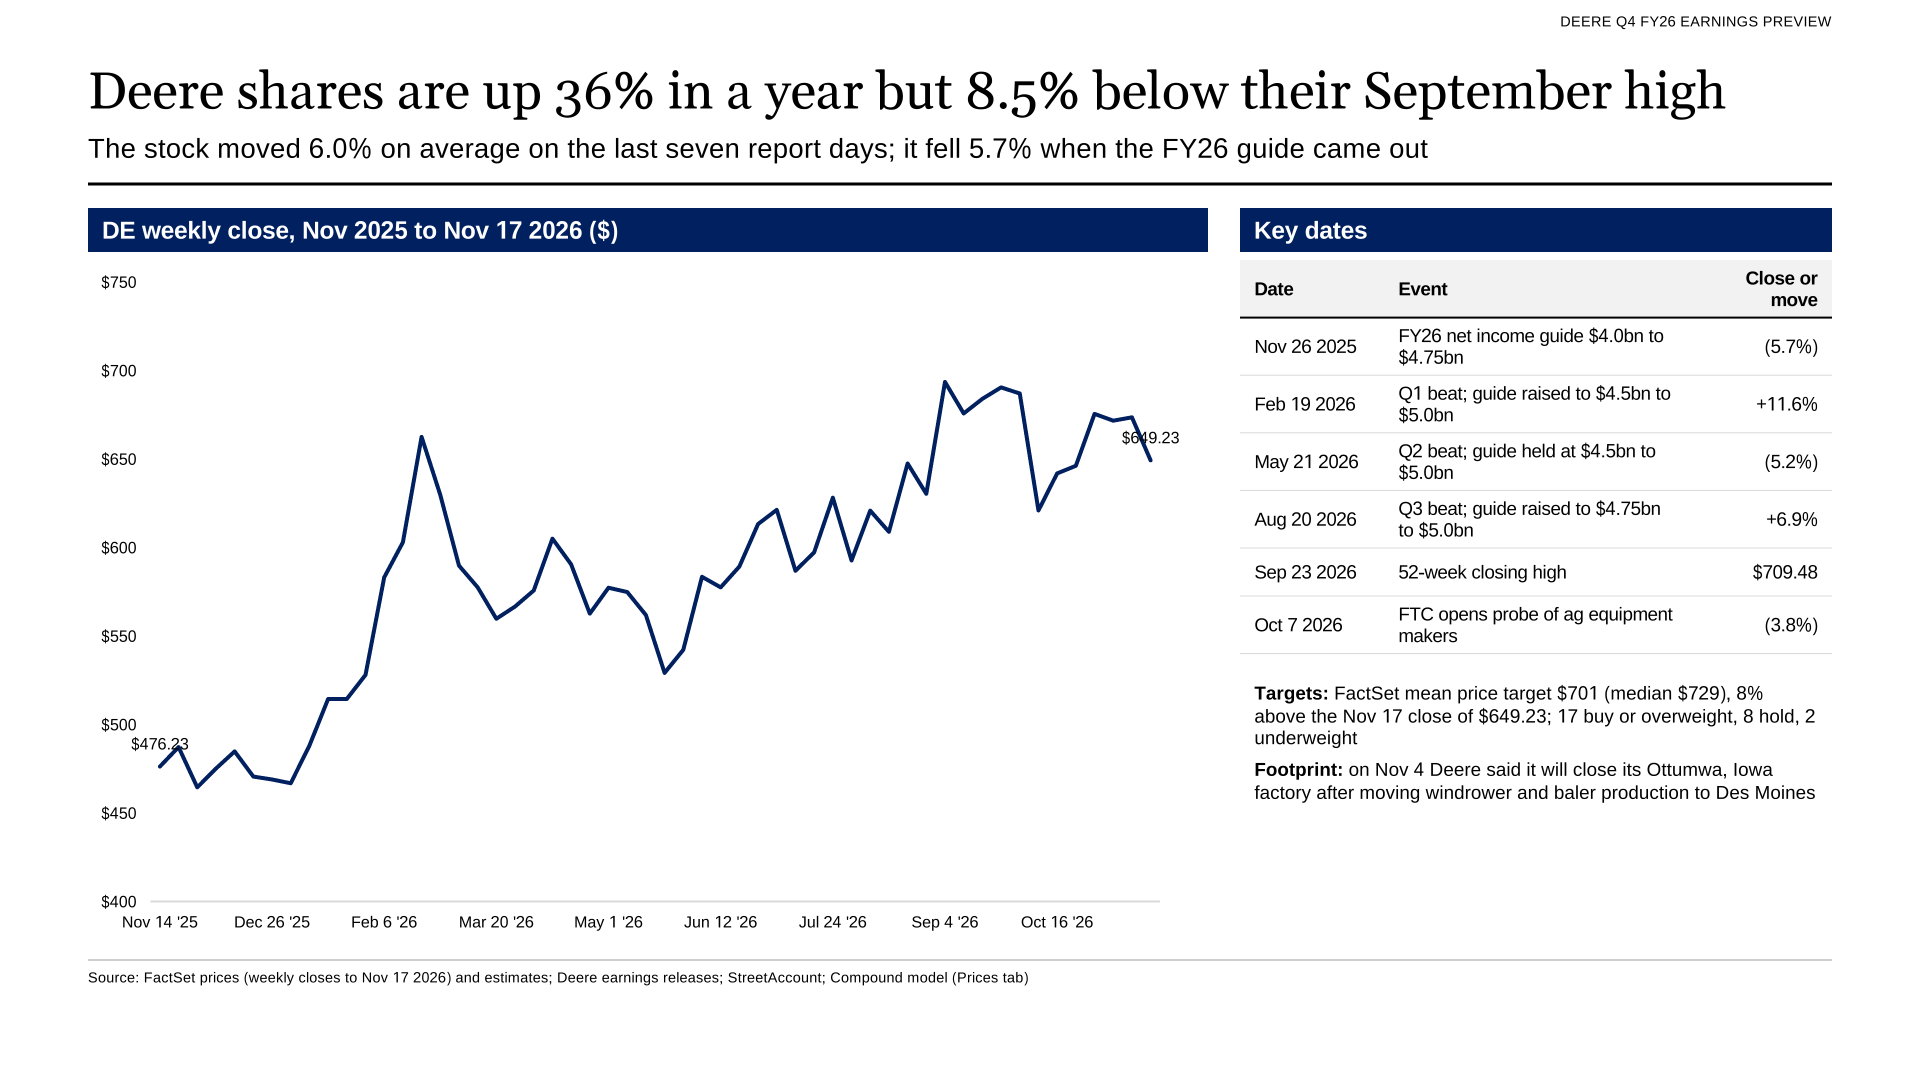
Deere shares are up 36% in a year but 8.5% below their September high. Slide 10.
The model
The Excel model has seven quarters of history from Deere's filings, the segment build, GAAP and adjusted income statements, quarterly cash flow, the balance sheet and working capital, the guidance and consensus track record, the fourth quarter implied by guidance, the fiscal 2027 bridge and data-table sensitivities. Every assumption is on one tab.
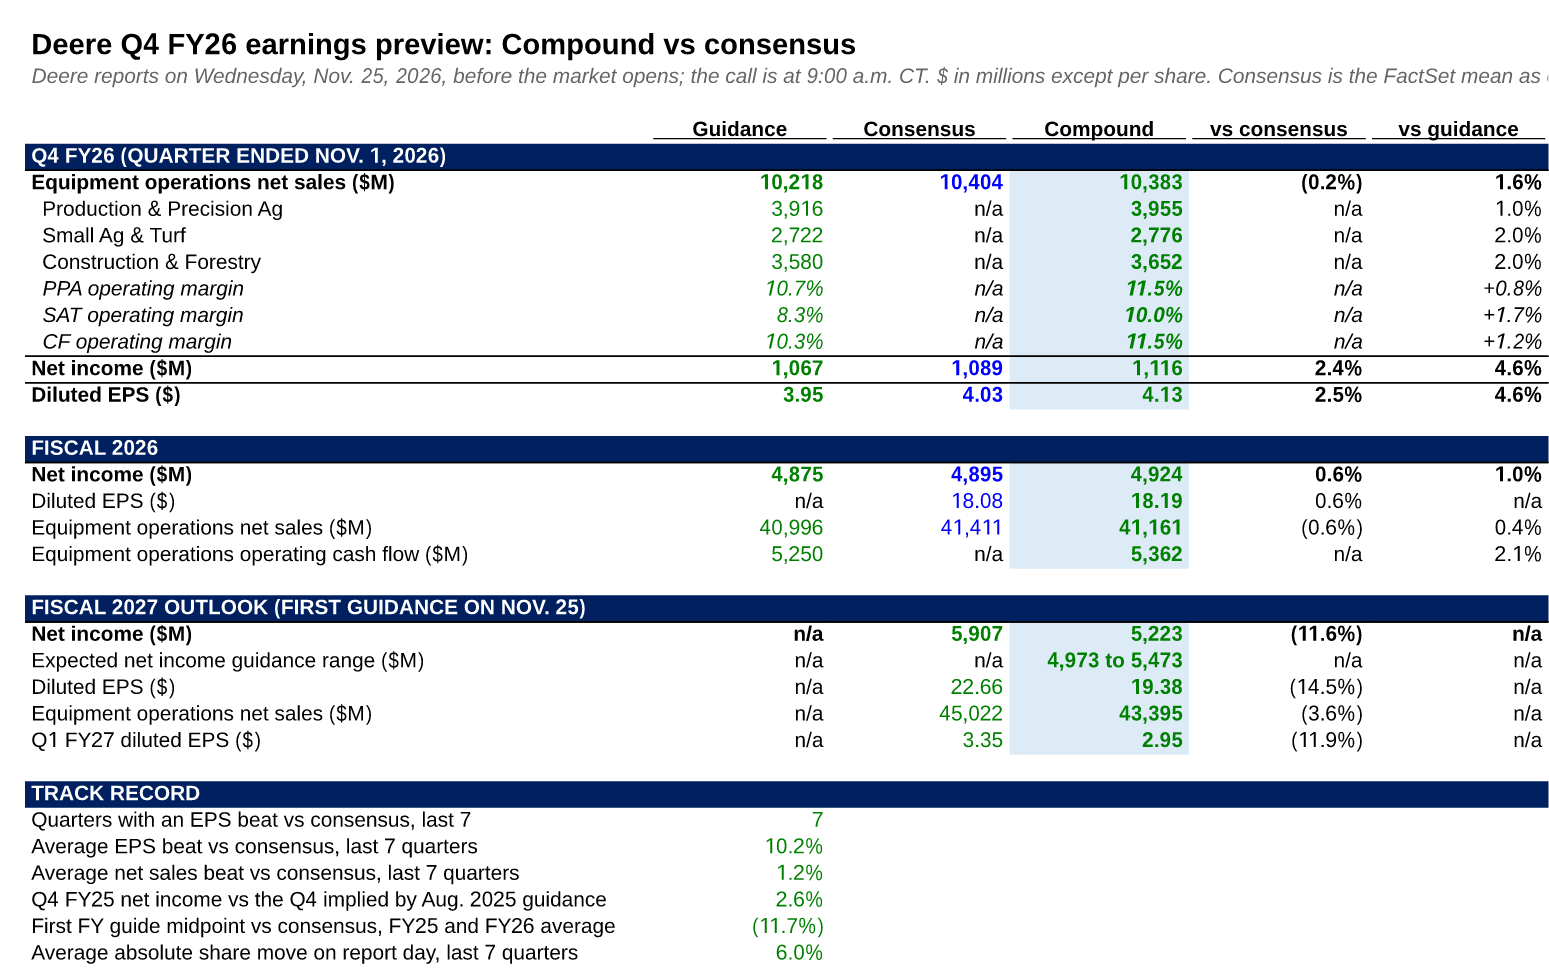
The Preview tab of the Excel model, which links every estimate to its drivers.
What to watch on Wednesday
- Fiscal 2027 net income guidance against the $5.91 billion consensus and our $5.0 billion to $5.5 billion.
- Fourth-quarter EPS against the $4.03 consensus and the $3.95 implied by guidance.
- The fourth-quarter equipment operating margin, which guidance puts at about 9.9%.
- Fiscal 2027 industry outlooks for U.S. and Canada large ag and for South America.
- The fiscal 2027 tariff estimate and any further IEEPA refunds.
- Any charges for the Ottumwa closure and the Hagie sprayer move announced Nov. 4.
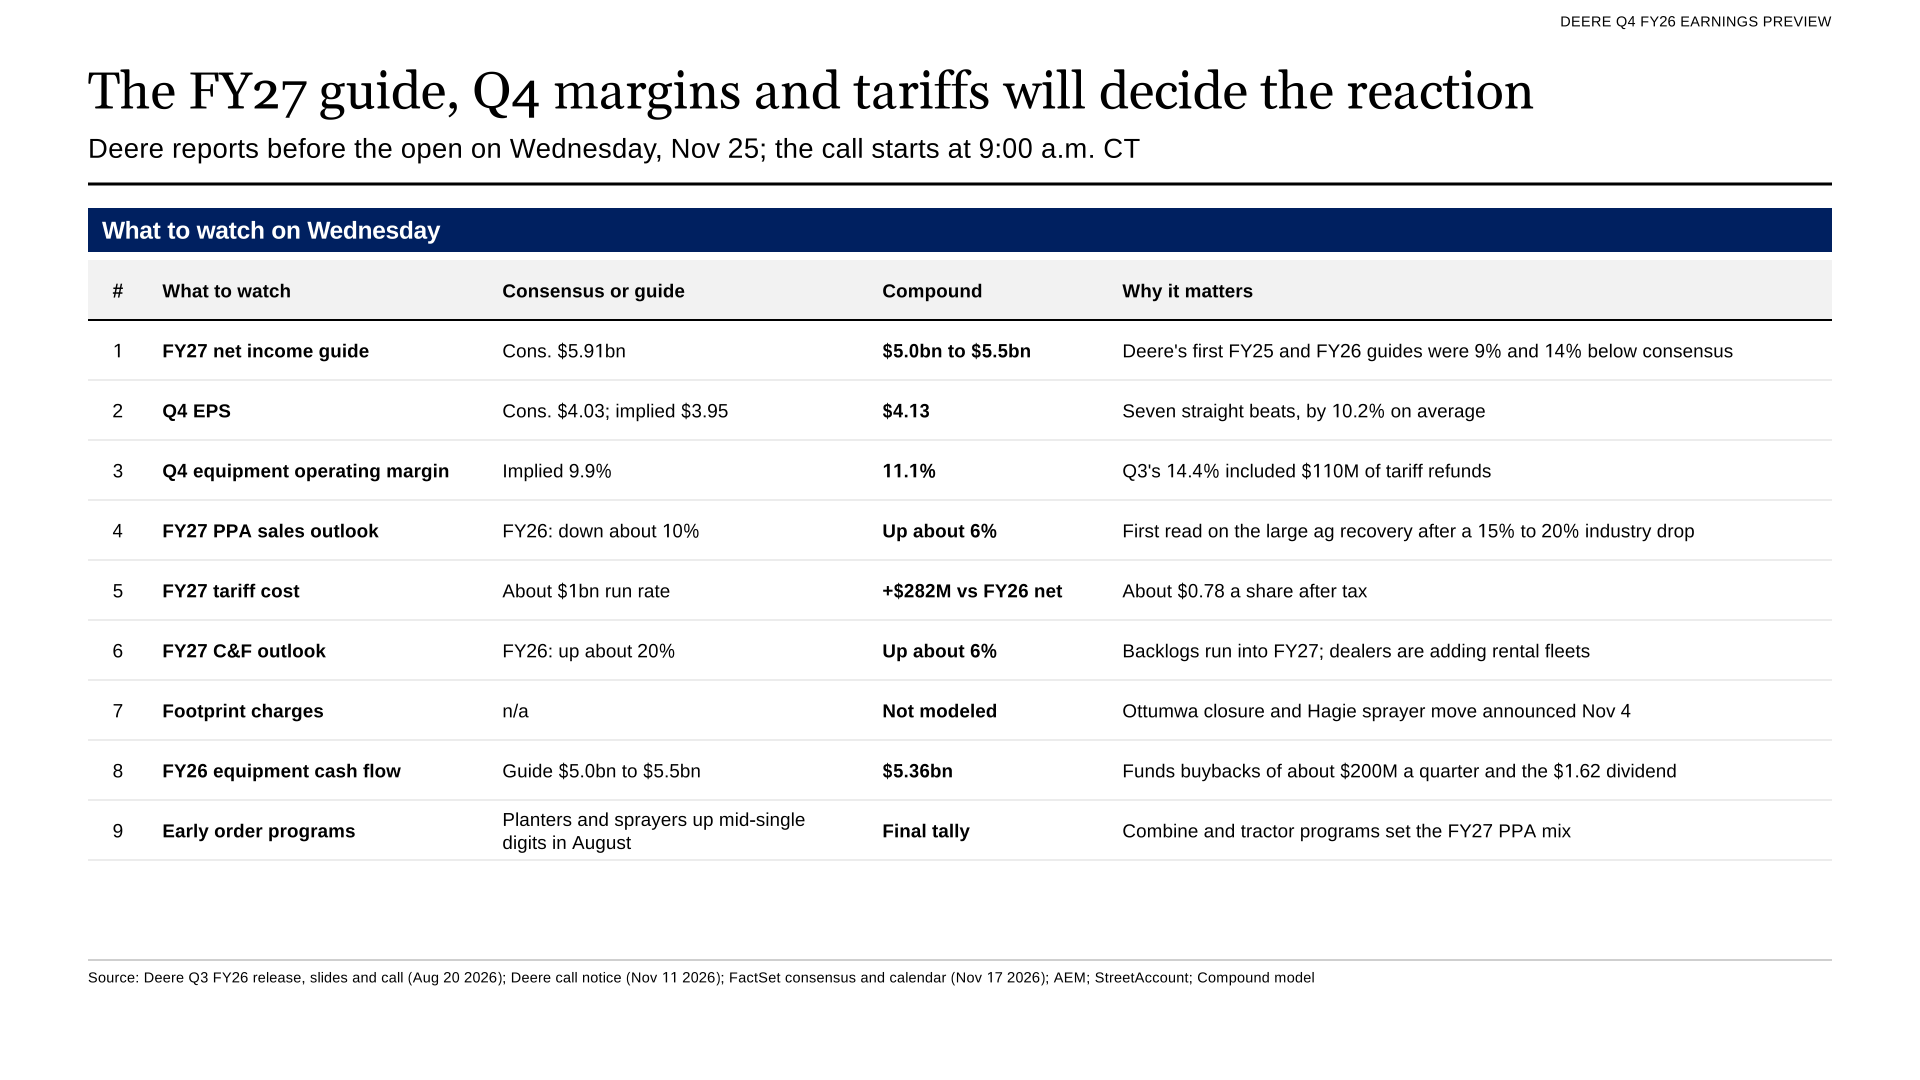
Nine things to watch on the call. Slide 11.
We will score this forecast against the reported numbers after the release.
 Deere Q4 FY26 earnings model (Excel)Quarterly model from Q1 FY25: segment build, operating profit, GAAP and adjusted income statements, quarterly cash flow, balance sheet and working capital, guidance and consensus track record, the Q4 implied by guidance, the FY27 bridge and data-table sensitivities, with formulas and sources.Download · Free
 Deere Q4 FY26 earnings preview deck (PowerPoint)11 slides: our call, forecast vs consensus, Q4 margins, track record, large ag demand, tariffs, FY27 guidance, cash flow, share price and what to watch, with editable charts and tables.Download · Free
 Deere Q4 FY26 earnings preview deck (PDF)The same 11 slides as a PDF.Download · Free
More from Compound News
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Read article →
Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Read article →
Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Read article →