Dell Q3 Earnings Preview: $6.57 EPS vs $6.60 Consensus
Dell reports Tuesday after the close. Our model puts AI server revenue above the $19 billion guide and PC revenue below it, for revenue of $48.9 billion and non-GAAP EPS of $6.57 against $6.60 consensus. The shares are down 45% from their Sept. 17 high.
Dell Technologies reports fiscal third-quarter results after the market closes on Tuesday, Nov. 24, with a conference call at 3:30 p.m. CT, the company said in a Nov. 10 release.
Compound's model forecasts revenue of $48.9 billion for the quarter that ended Oct. 30, 0.1% below Dell's $49.0 billion guidance midpoint and 0.6% below the FactSet consensus of $49.25 billion. We forecast non-GAAP EPS of $6.57 against Dell's guide of $6.50 and consensus of $6.60.
The shares closed at $322.79 on Nov. 17, down 45.1% from their 2026 closing high of $588.40 on Sept. 17 and still up 156% for the year. Options imply a move of about 10% after the report, Investing.com reported.
We built an 11-page earnings preview deck on the model. The slides below come from it, and the deck and the Excel model are free to download at the end.
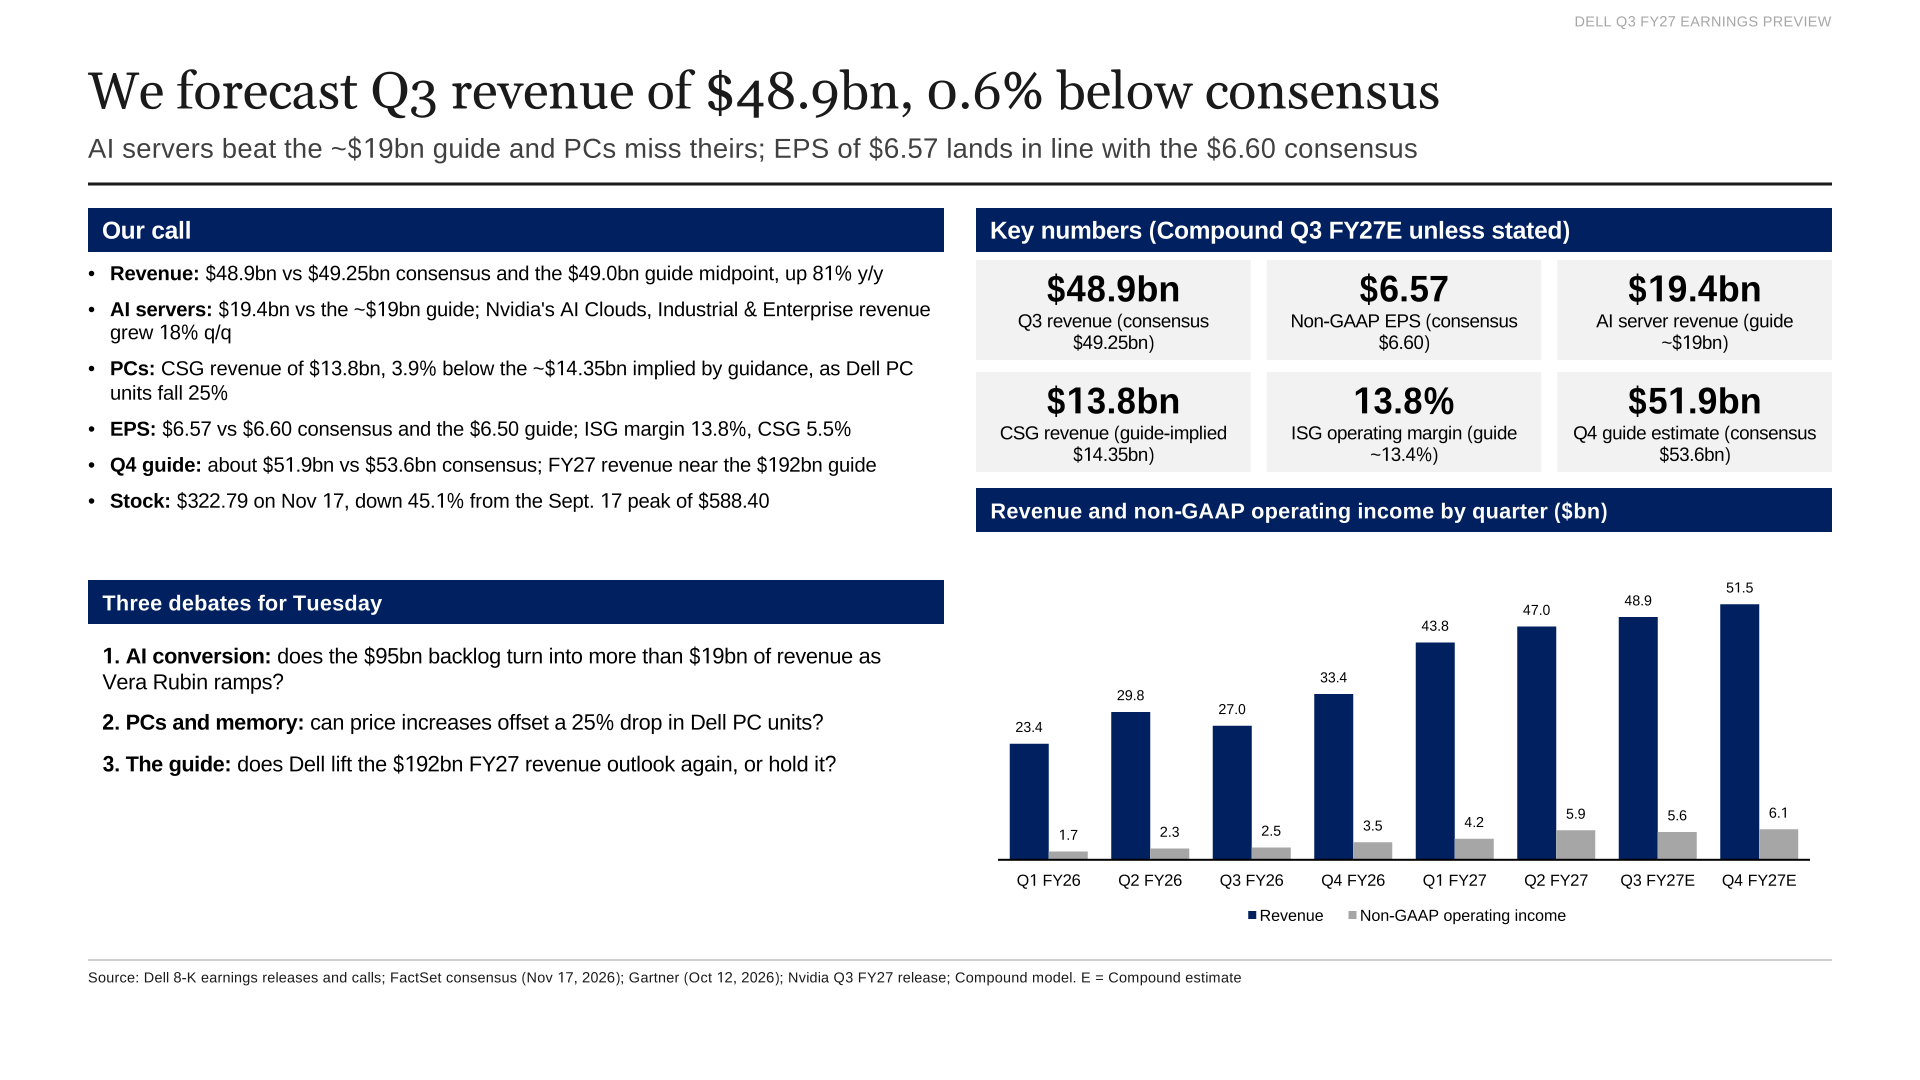
Executive summary: our call against consensus and the three debates for Tuesday.
Forecast vs consensus
| Q3 FY27 | Guidance | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Revenue | $49.0B | $49.25B | $48.9B | -0.6% |
| ISG revenue | about $34.6B | n/a | $35.0B | n/a |
| AI-optimized servers | about $19.0B | n/a | $19.4B | n/a |
| CSG revenue | about $14.35B | n/a | $13.8B | n/a |
| Non-GAAP gross margin | n/a | 19.2% | 19.5% | +0.3 pt |
| Non-GAAP operating income | about $5.51B | $5.54B | $5.60B | +1.1% |
| Non-GAAP EPS | $6.50 | $6.60 | $6.57 | -0.4% |
| GAAP EPS | $6.10 | $6.10 | $5.99 | -1.8% |
Consensus is the FactSet mean as of Nov. 17. Segment guidance is from Dell's Sept. 1 call: ISG revenue up about 145%, CSG revenue up about 15%, ISG operating margin up just over a point and CSG margin near 6%. StreetAccount had not published segment consensus for the quarter as of Nov. 17. Our GAAP figure includes $120 million of other corporate expenses that Dell's guide leaves out.
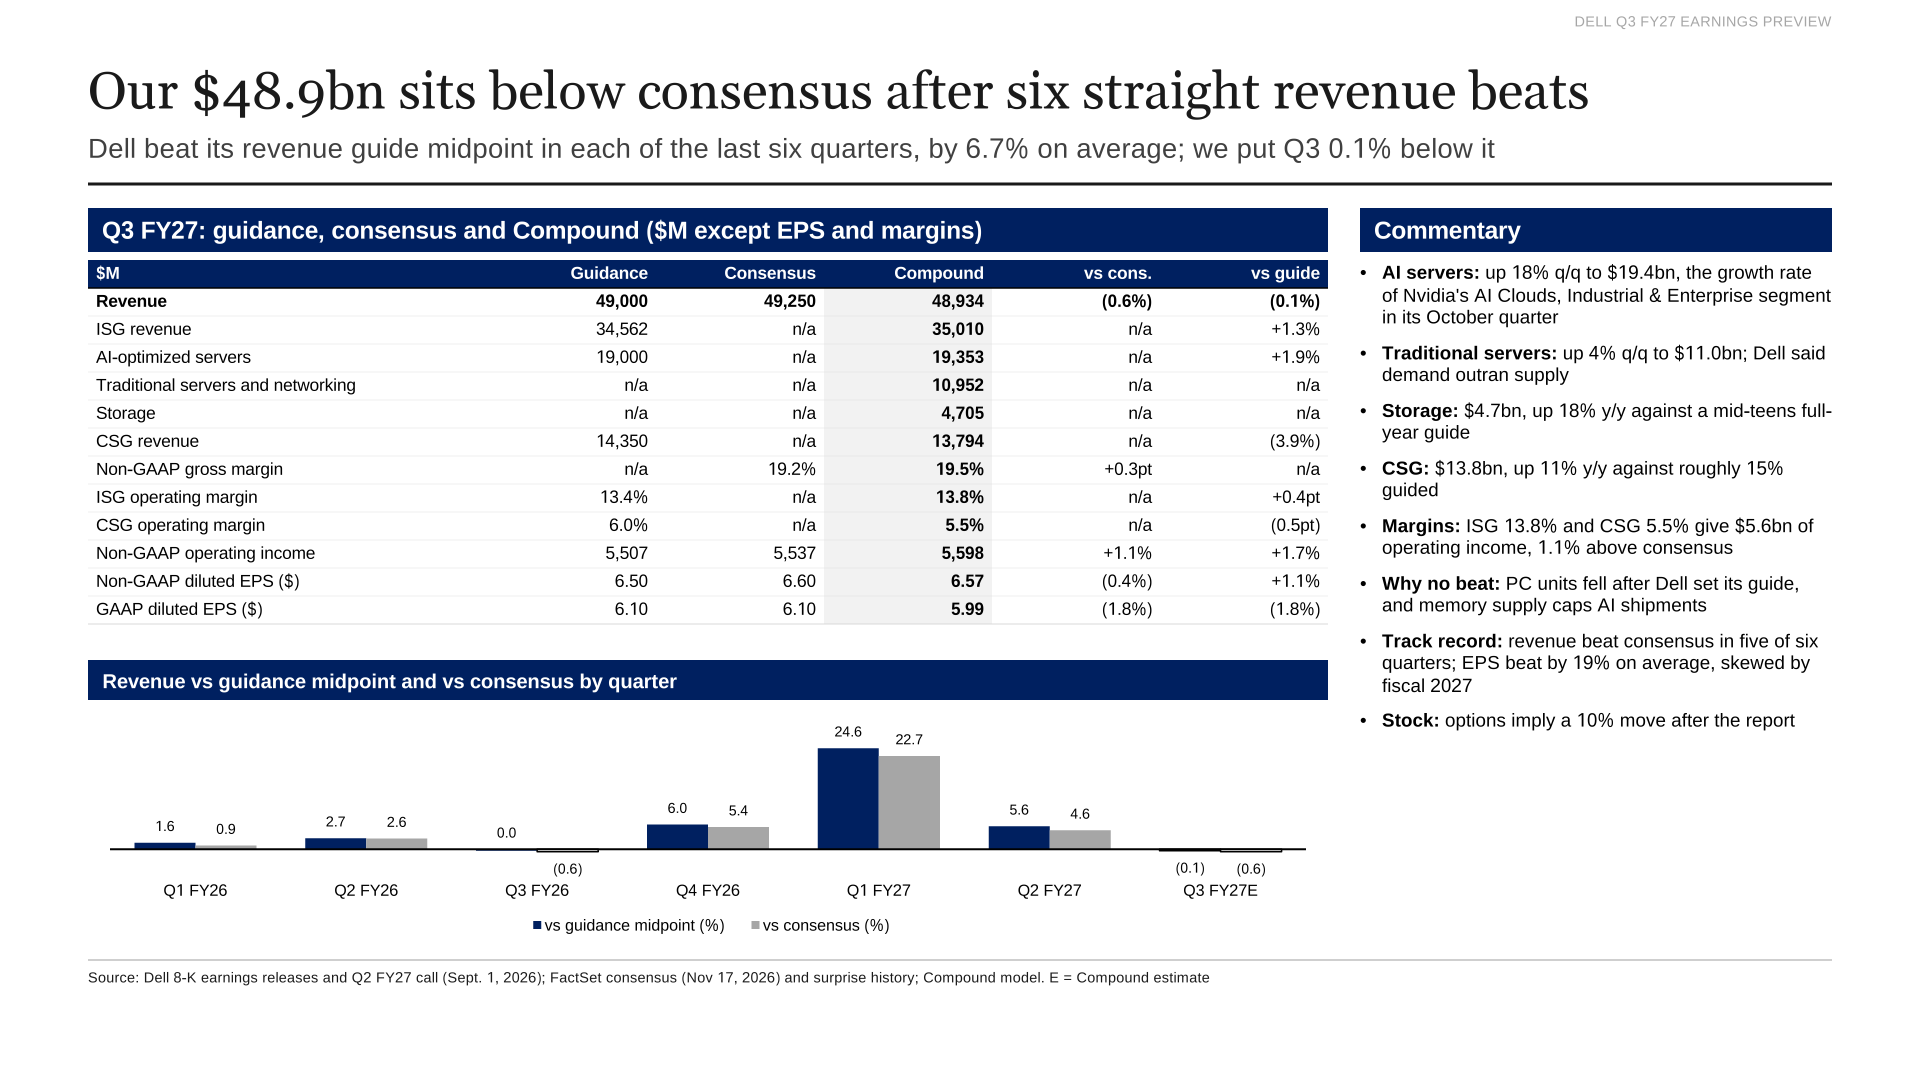
Dell beat its revenue guidance midpoint in each of the last six quarters, by 6.7% on average. We put this quarter 0.1% below it.
How we built the forecast
The model grows each line from its second-quarter level. AI-optimized server revenue rises 18% to $19.4 billion, the sequential growth Nvidia reported on Nov. 17 for its AI Clouds, Industrial & Enterprise segment, which covers the neoclouds, sovereign buyers and enterprises that buy Dell's AI systems. Dell's AI revenue was 40.7% of that segment's revenue in the July quarter. At the same share, Nvidia's $47.5 billion October quarter points to $19.3 billion for Dell.
Traditional servers and networking grow 4% to $11.0 billion. Storage falls 3% from Q2 to $4.7 billion, up 18% from a year earlier. Dell said on its Sept. 1 call that demand outran supply in both of the first two quarters.
PCs are where we part with the guide. Client Solutions Group (CSG) revenue falls 8% from Q2 to $13.8 billion, up 10.5% from a year earlier against roughly 15% guided.
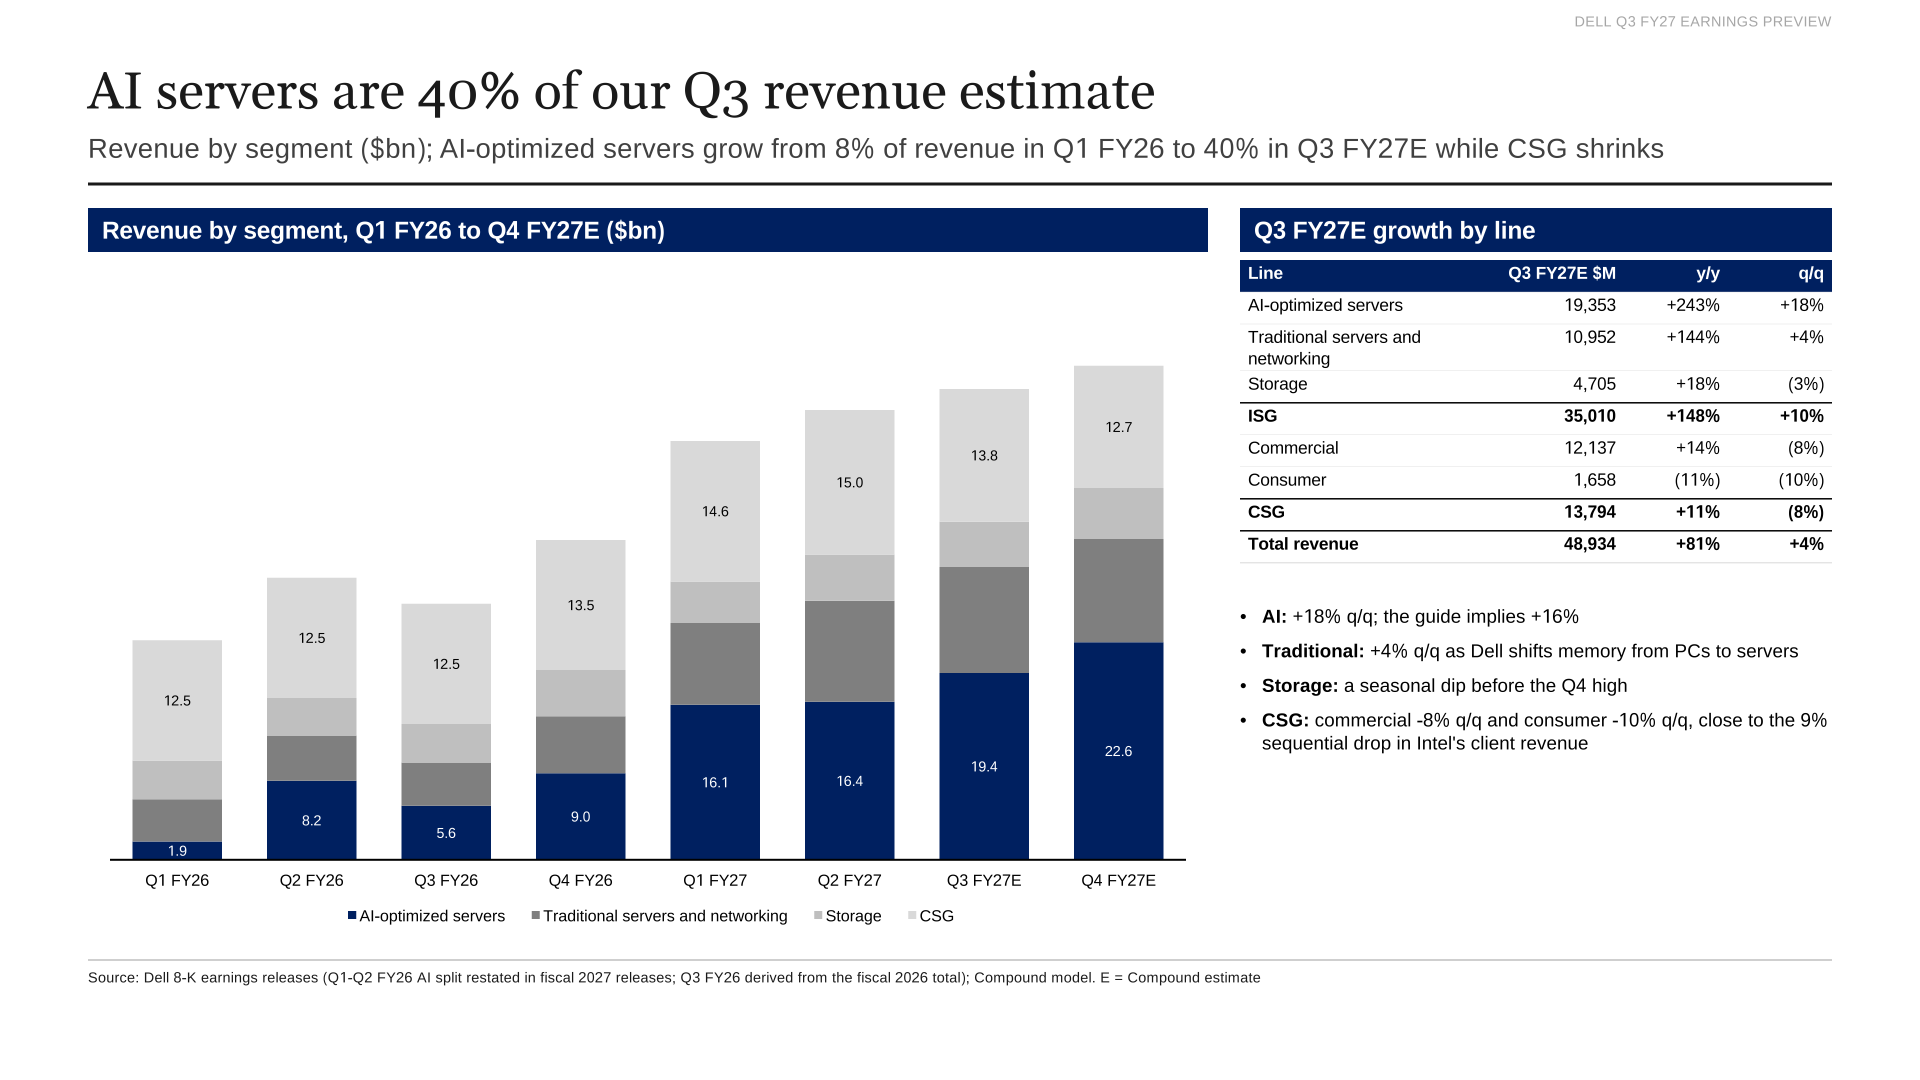
AI-optimized servers rise to 40% of our Q3 revenue estimate, from 8% in Q1 FY26.
AI orders, backlog and the Vera Rubin ramp
Dell booked a record $60.9 billion of AI orders in the July quarter and ended it with $95 billion of AI backlog, against $16.4 billion of AI server revenue, according to its Q2 release and call. It also said it was the first to ship rack systems built on Nvidia's Vera Rubin platform.
Nvidia said on Nov. 17 that Rubin was its fastest architecture ramp ever. Dell guided AI server revenue to about $19 billion for the October quarter and $74 billion for fiscal 2027, which, after our Q3, leaves $22.1 billion for Q4.
Supply sets the pace. "DRAM, DRAM, followed by NAND, NAND," Chief Operating Officer Jeff Clarke said on the Sept. 1 call when asked about constraints. We assume $30 billion of AI orders in Q3, half of the Q2 record, which would lift the backlog to about $105.6 billion.
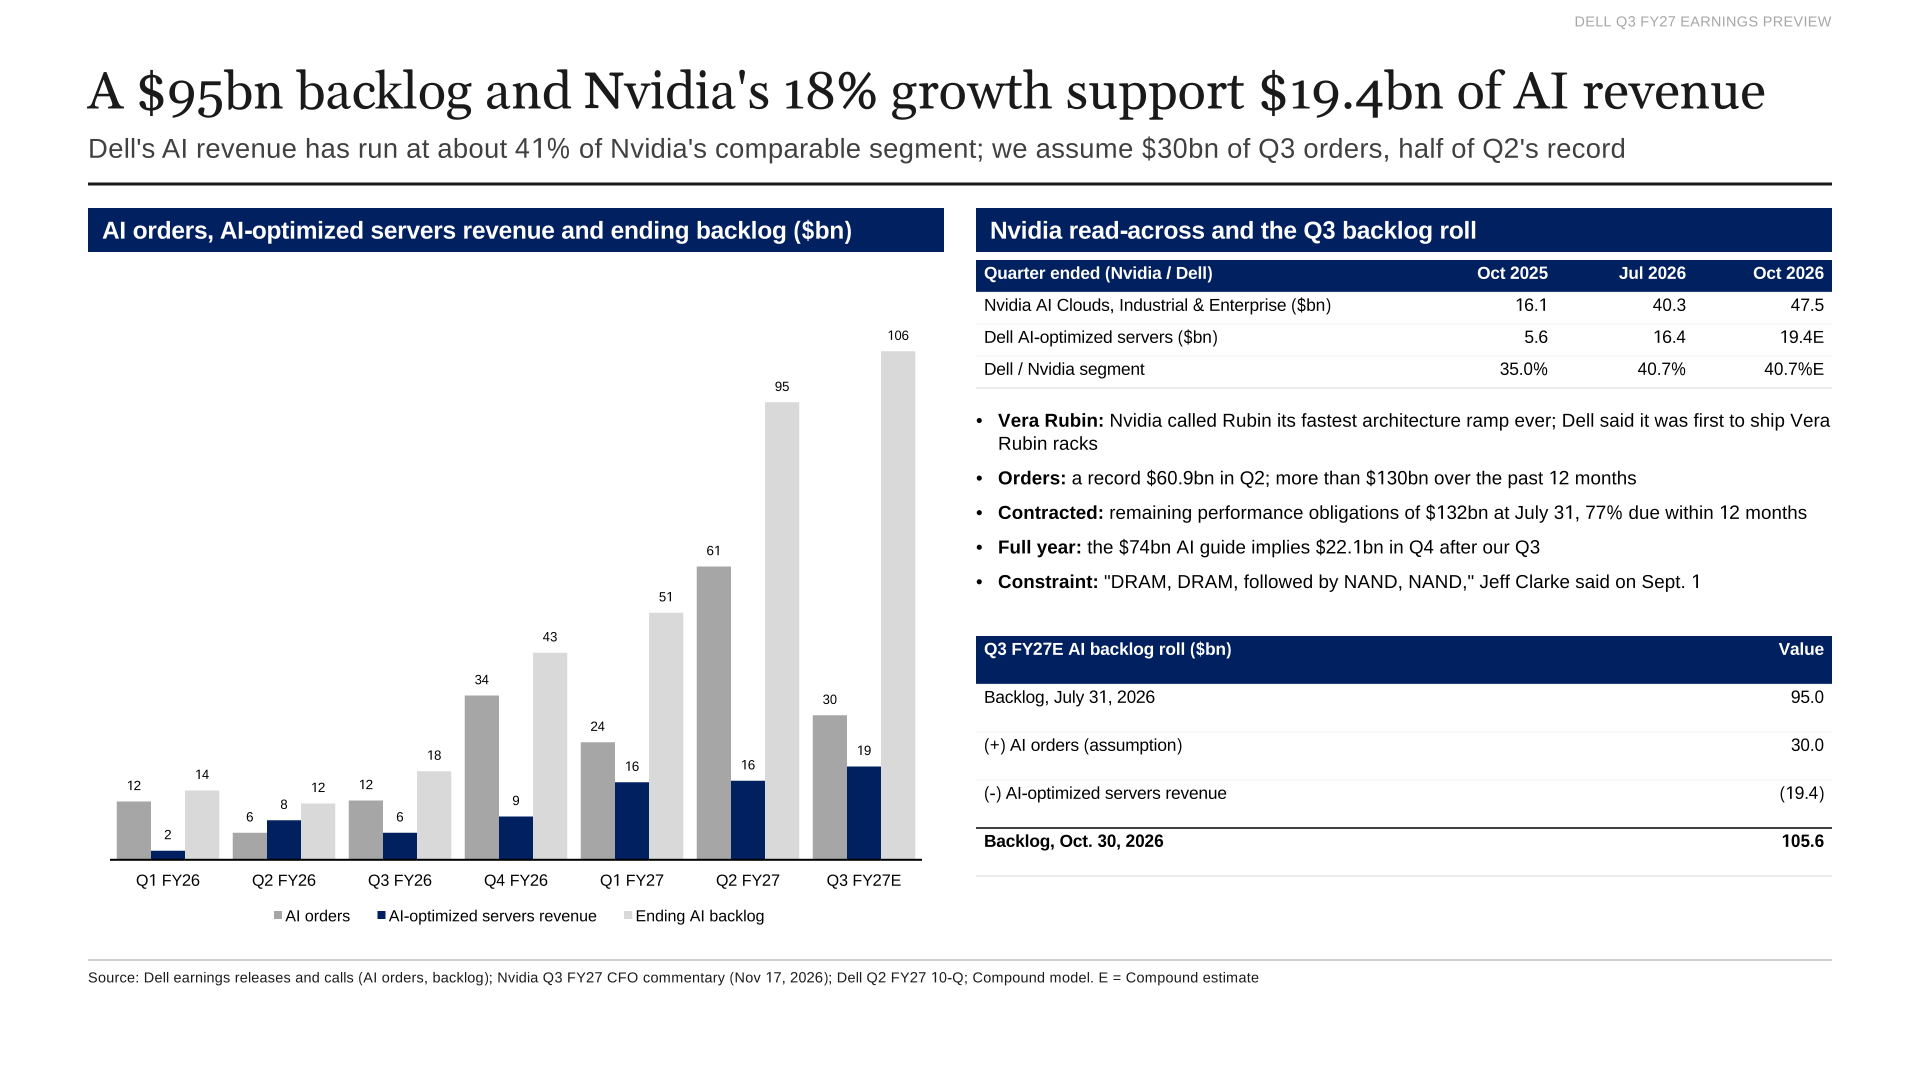
Dell's AI revenue has run at about 41% of Nvidia's comparable segment.
PCs and memory
Gartner estimated on Oct. 12 that Dell shipped 7.58 million PCs in the July-to-September quarter, down 25.4% from a year earlier, as worldwide shipments fell 22.4%. Gartner said DRAM costs rose five times year over year in the second quarter and PC makers passed them on to customers.
At that unit decline, Dell would need revenue per PC up about 54% to grow CSG revenue 15%. In the July quarter, CSG revenue rose 20% while IDC estimated Dell's units fell 5%, which implies about 27%. Our $13.8 billion assumes about 48%.
Intel said on Oct. 29 that it expects PC units to fall 12% in 2026 and 10% in 2027, and its client revenue to drop more than 20% sequentially in the December quarter, FinanceFeeds reported. Dell shares fell 10.8% the next day. On its Sept. 1 call, Dell said it had moved memory from PCs to servers as the PC market softened.
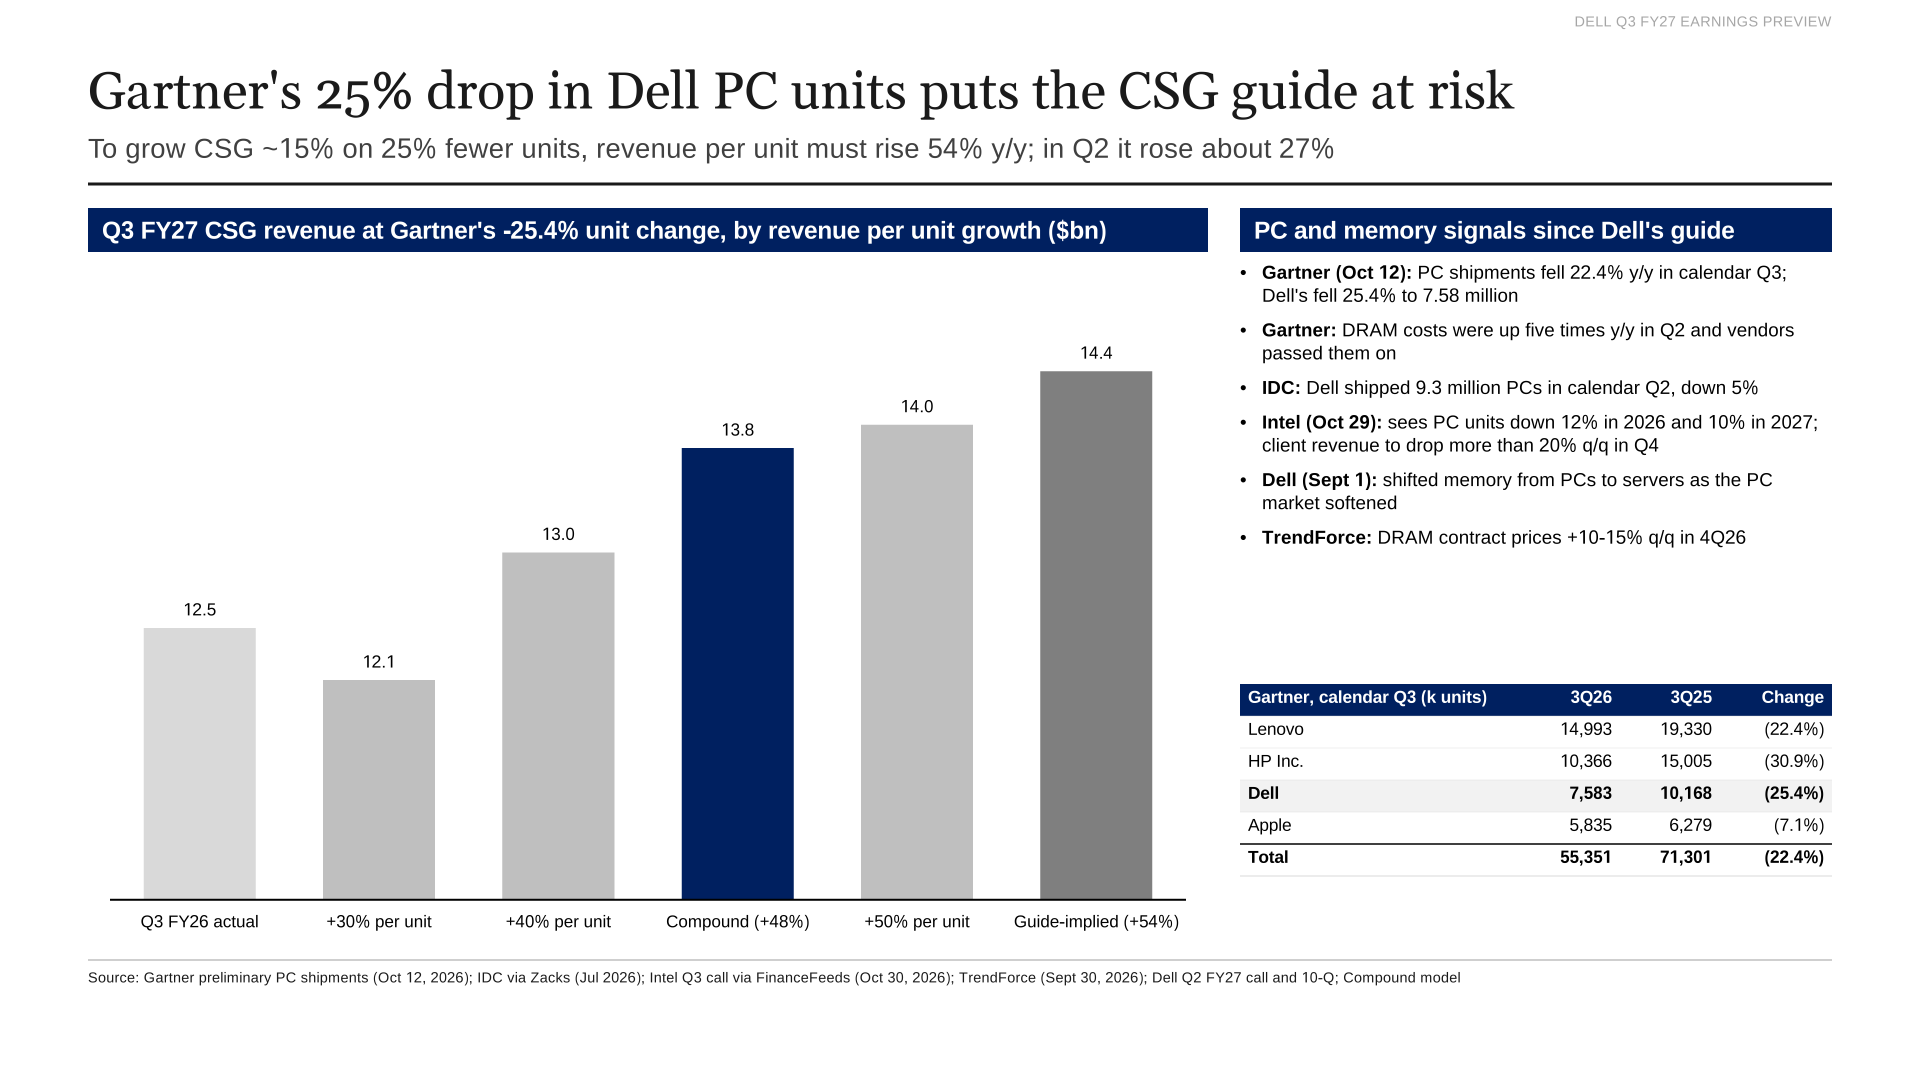
Revenue per unit has to rise 54% for CSG to meet the guide on Gartner's unit estimate.
Margins
We put ISG operating margin at 13.8%, above the roughly 13.4% implied by Dell's guidance of a gain of just over a point from 12.4% a year earlier, and below the 15.0% of Q2. Dell's product gross margin rose 5.2 points to 17.3% in Q2, which its 10-Q attributes primarily to disciplined pricing. CSG operating margin falls to 5.5% from 7.6%, against guidance of about 6%. In our model each point of ISG margin is worth about $0.44 of EPS.
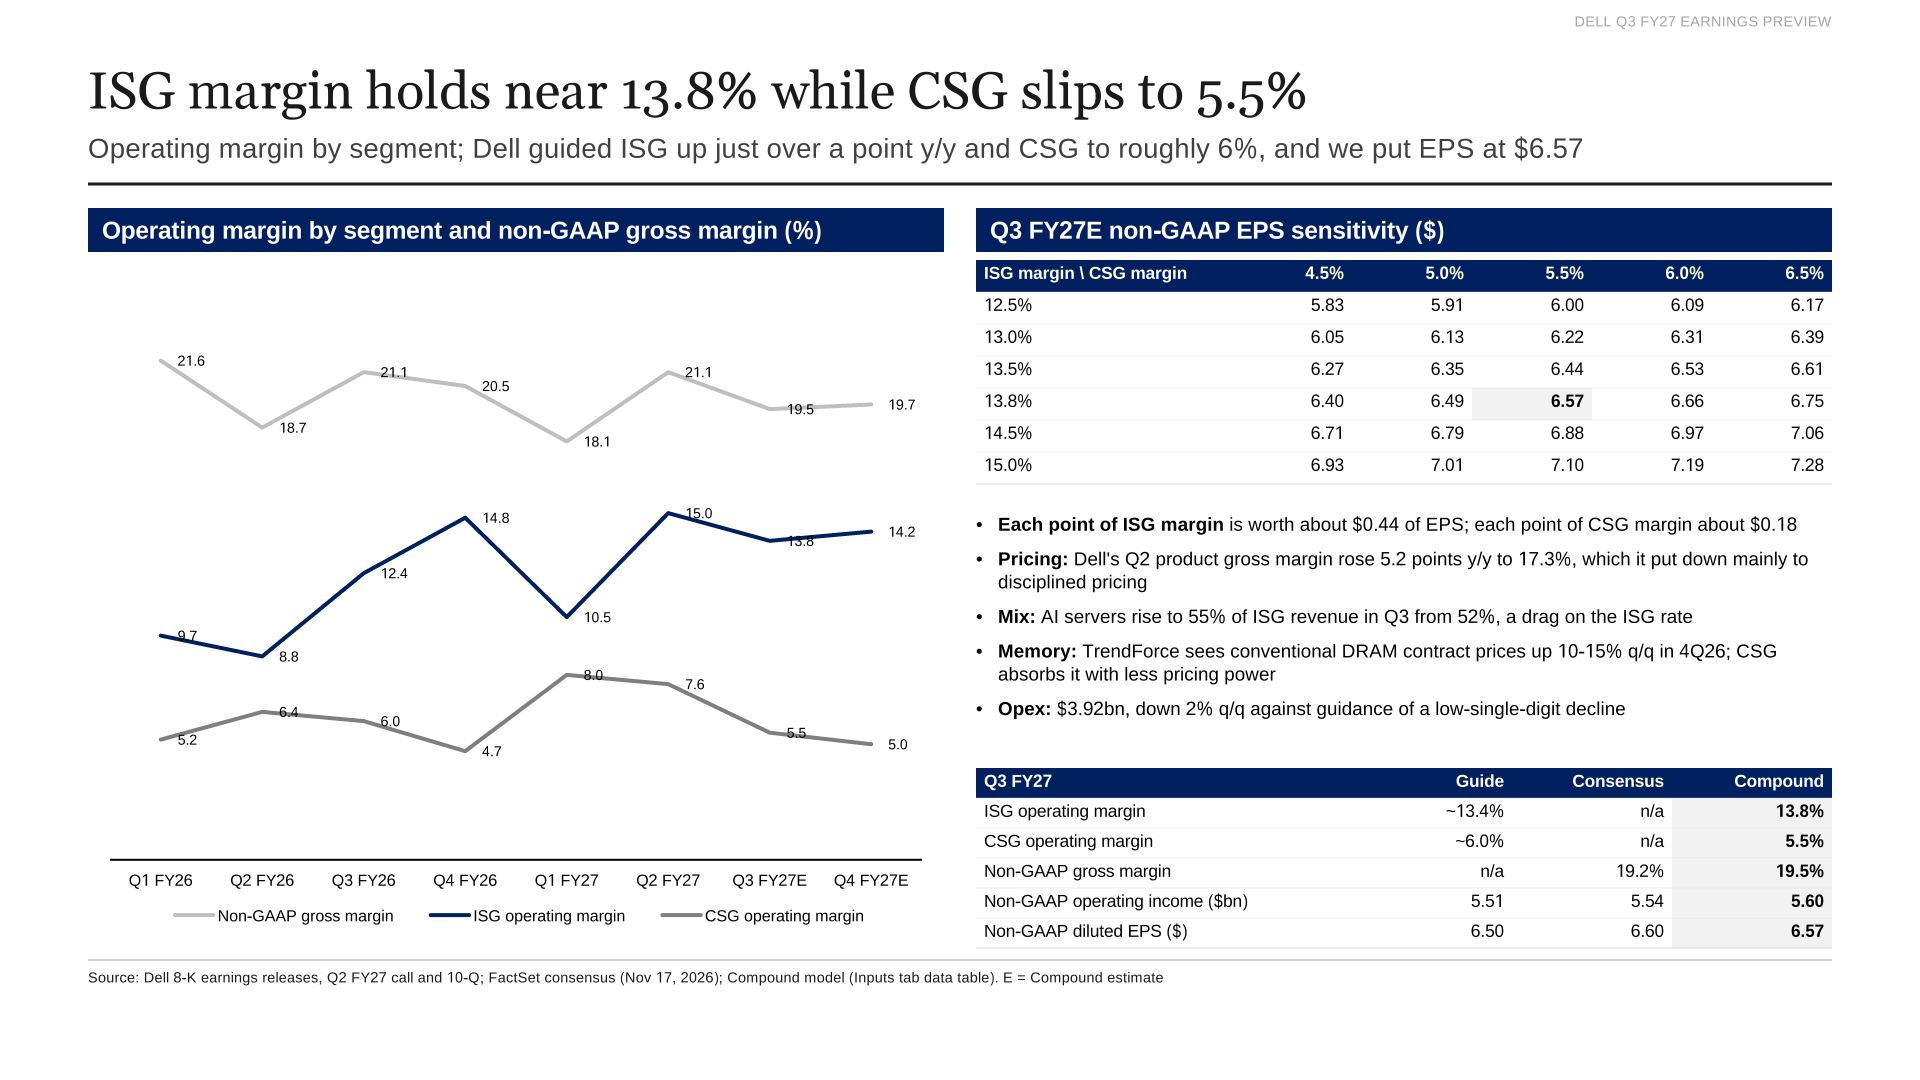
ISG margin holds near 13.8% while CSG slips to 5.5%.
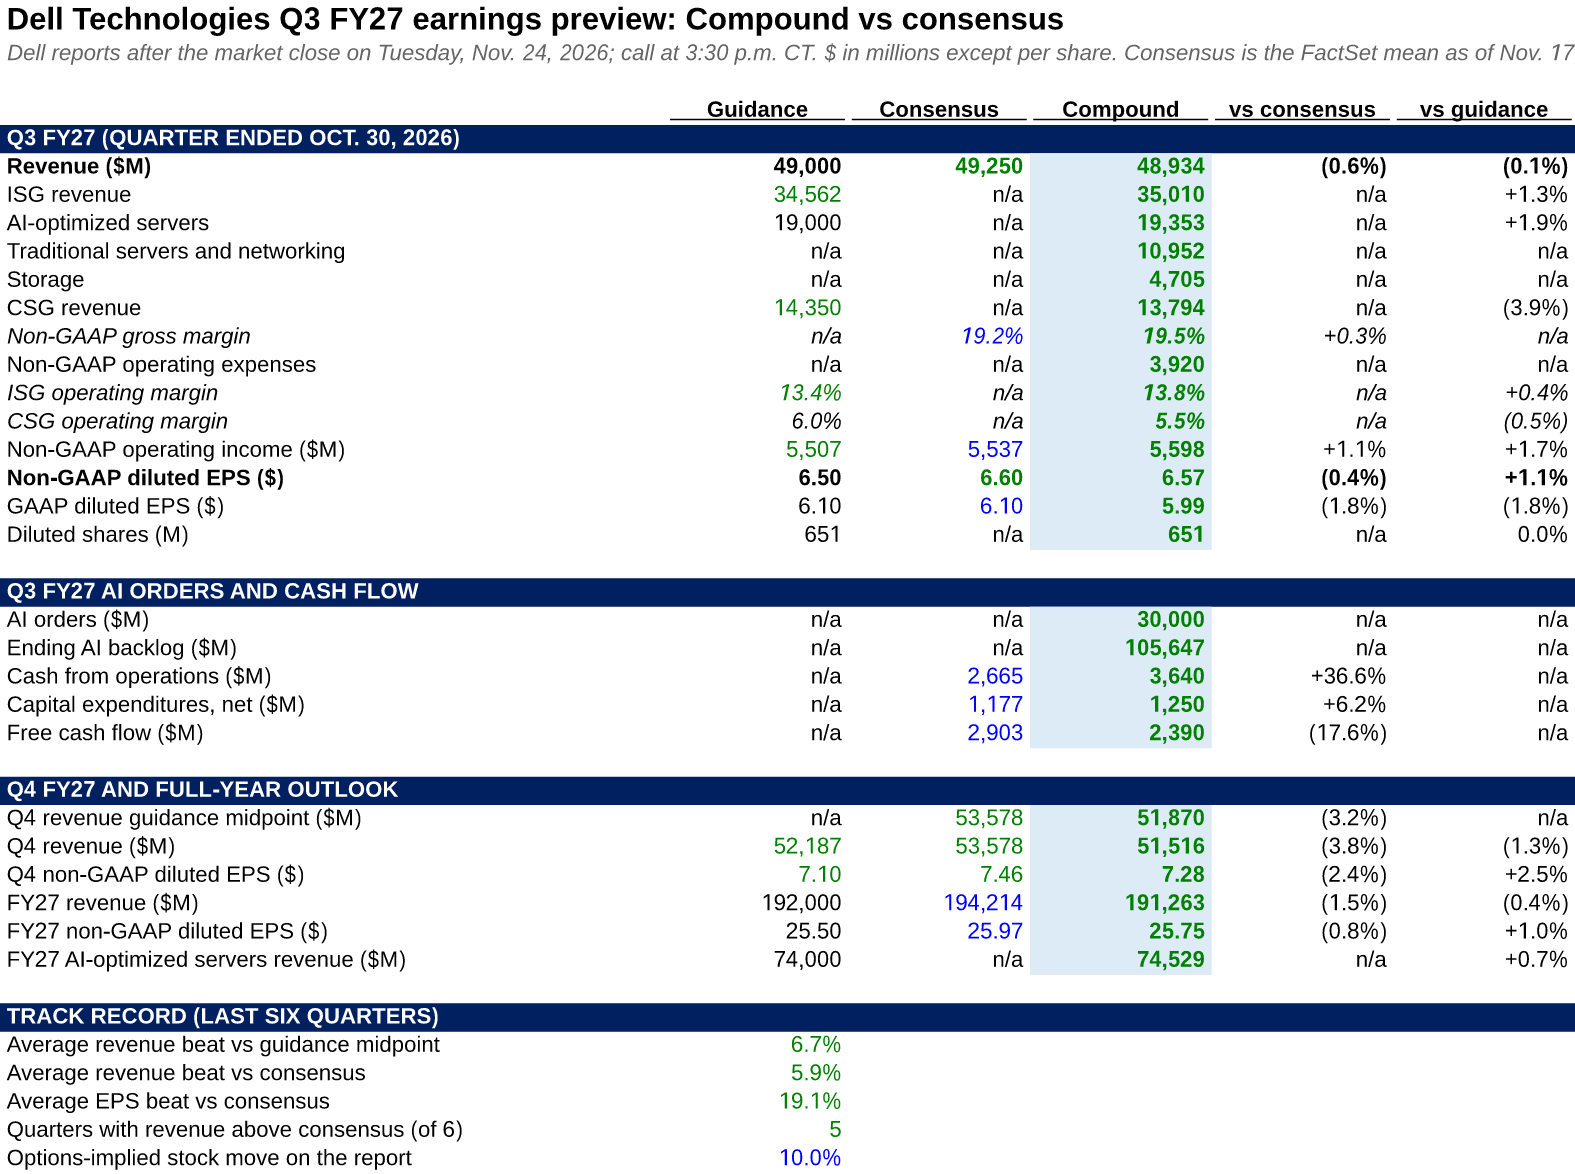
The Preview tab of the Excel model, which links every estimate to its drivers.
Cash flow
We forecast cash from operations of $3.6 billion and free cash flow of $2.4 billion, against FactSet consensus of $2.7 billion and $2.9 billion, which come from different groups of analysts. Inventory nearly tripled in a year to $21.3 billion at July 31, $15.9 billion of it production materials, and purchase obligations reached $34.8 billion, according to Dell's 10-Q. We hold days of inventory near 50 in Q3.
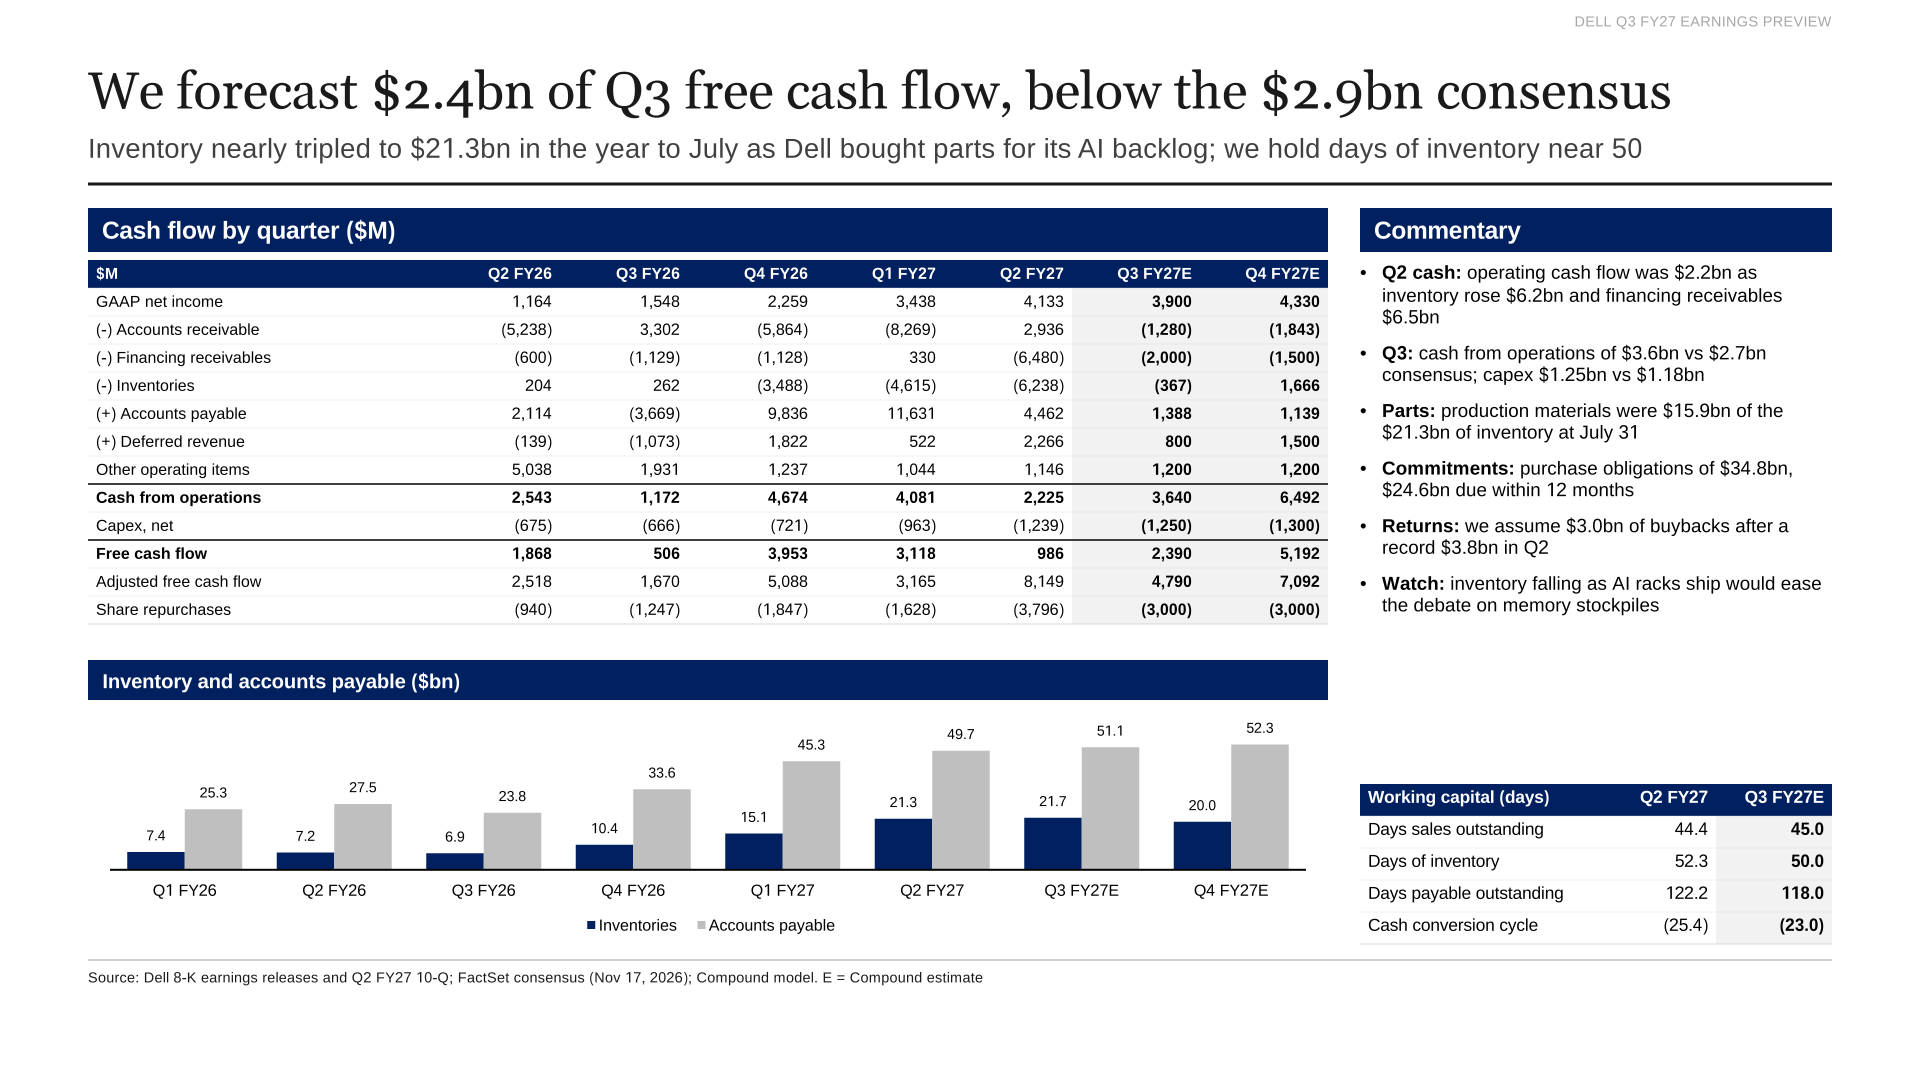
Inventory and receivables decide the cash number.
Q4 guidance
FactSet consensus for fourth-quarter revenue is $53.6 billion. Dell's $192 billion fiscal-year guide, less first-half revenue and the Q3 midpoint, implies $52.2 billion. We expect a Q4 guide near $51.9 billion, with AI server revenue up 17% and PC revenue down again, and fiscal 2027 revenue close to the $192 billion guide. Dell raised that guide by $27 billion in May and $25 billion in September, the main risk to this call.
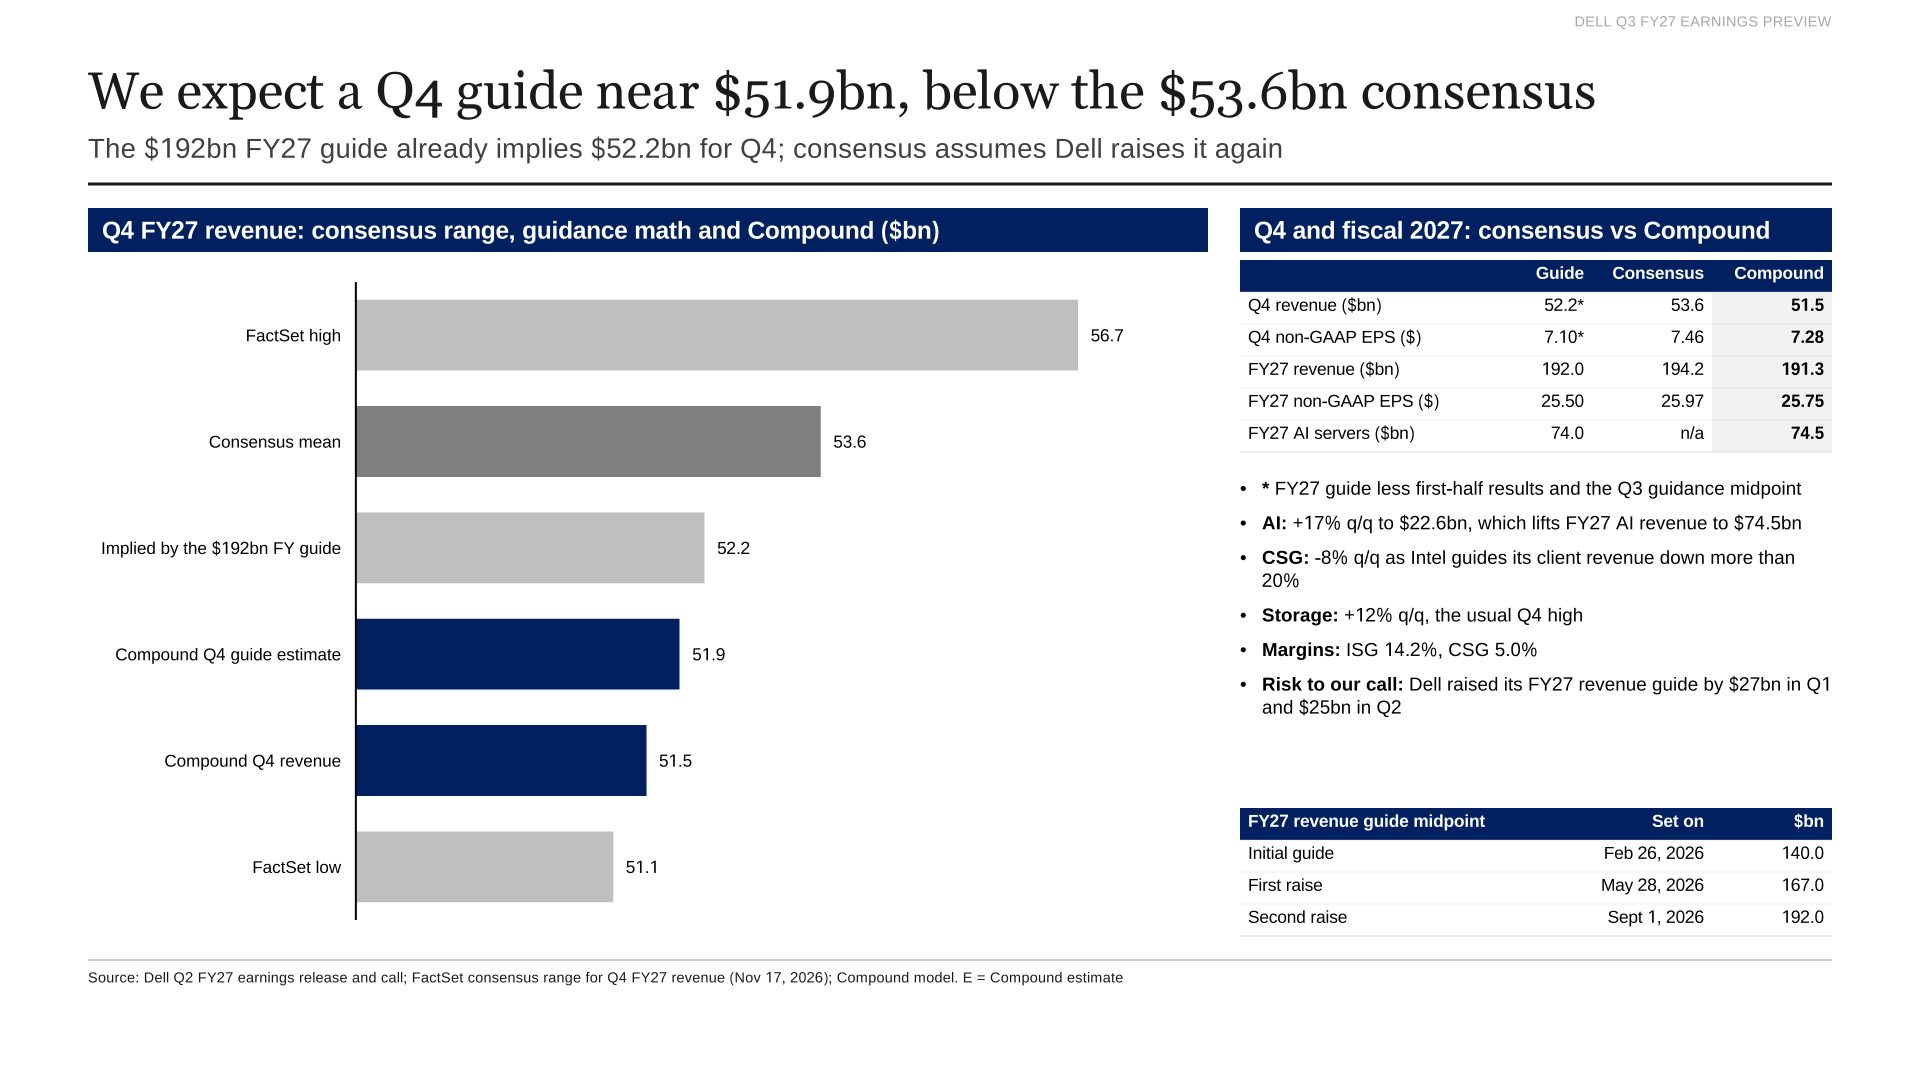
The full-year guide already implies $52.2 billion for Q4.
The selloff
Dell fell 11.3% on Oct. 14 after Barclays cut the stock to equal weight. Analyst Tim Long said high memory costs had lifted revenue without a strong AI boost, CMEG reported. The shares fell 14.9% on Nov. 5 in a selloff in AI hardware after the Nov. 3 midterm elections, 24/7 Wall St. reported, and 7.0% on Nov. 16 after reports that a research firm had cut its forecast for AI accelerator spending (unconfirmed), Kalkine reported.
Morgan Stanley cut its price target to $403 from $511 and Citi to $550 from $600 on Nov. 16.
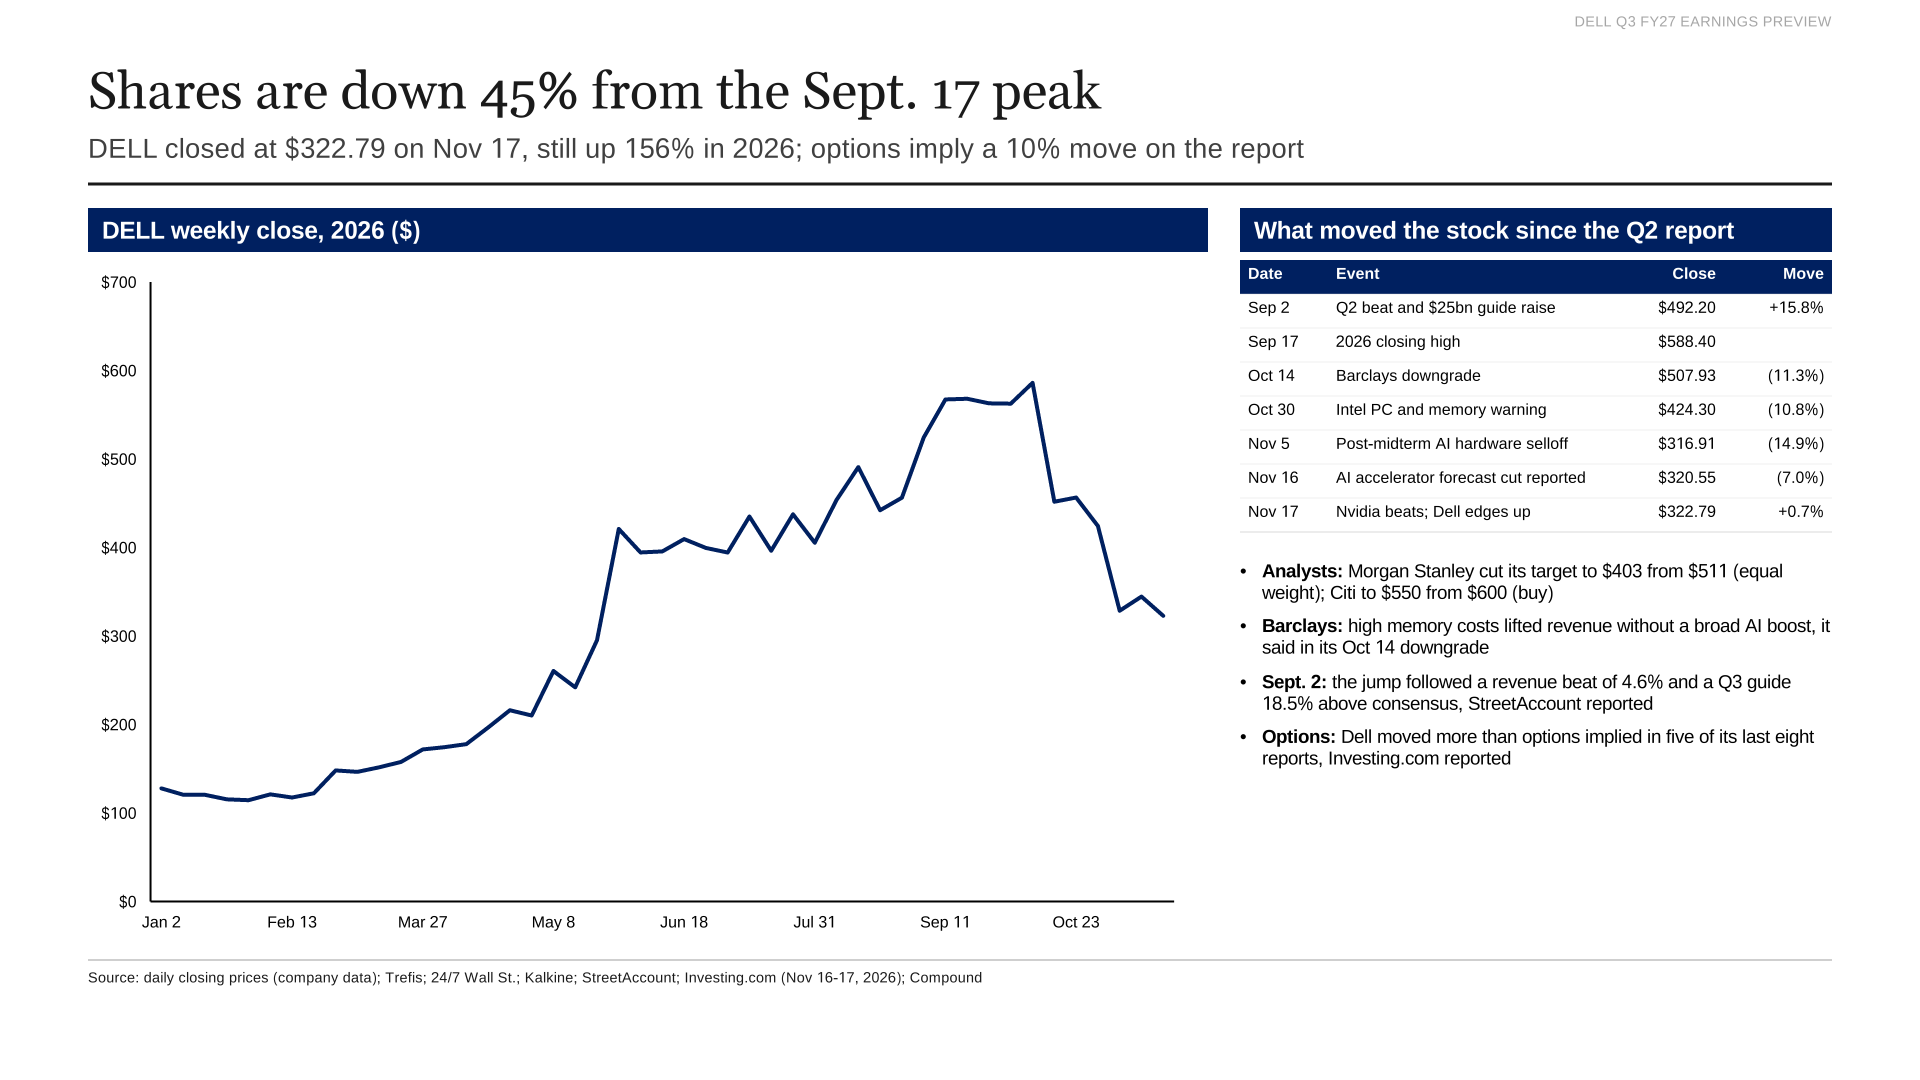
The shares are down 45% from the Sept. 17 high.
What to watch on Tuesday
- AI server revenue against the roughly $19 billion guide and our $19.4 billion.
- AI orders and backlog after Q2's $60.9 billion and $95 billion.
- CSG revenue against the roughly $14.35 billion implied by guidance and our $13.8 billion.
- ISG operating margin against about 13.4% guided and our 13.8%.
- The Q4 revenue guide against the $53.6 billion consensus and our $51.9 billion, and any change to the $192 billion fiscal-year guide.
- Inventory against $21.3 billion at the end of Q2.
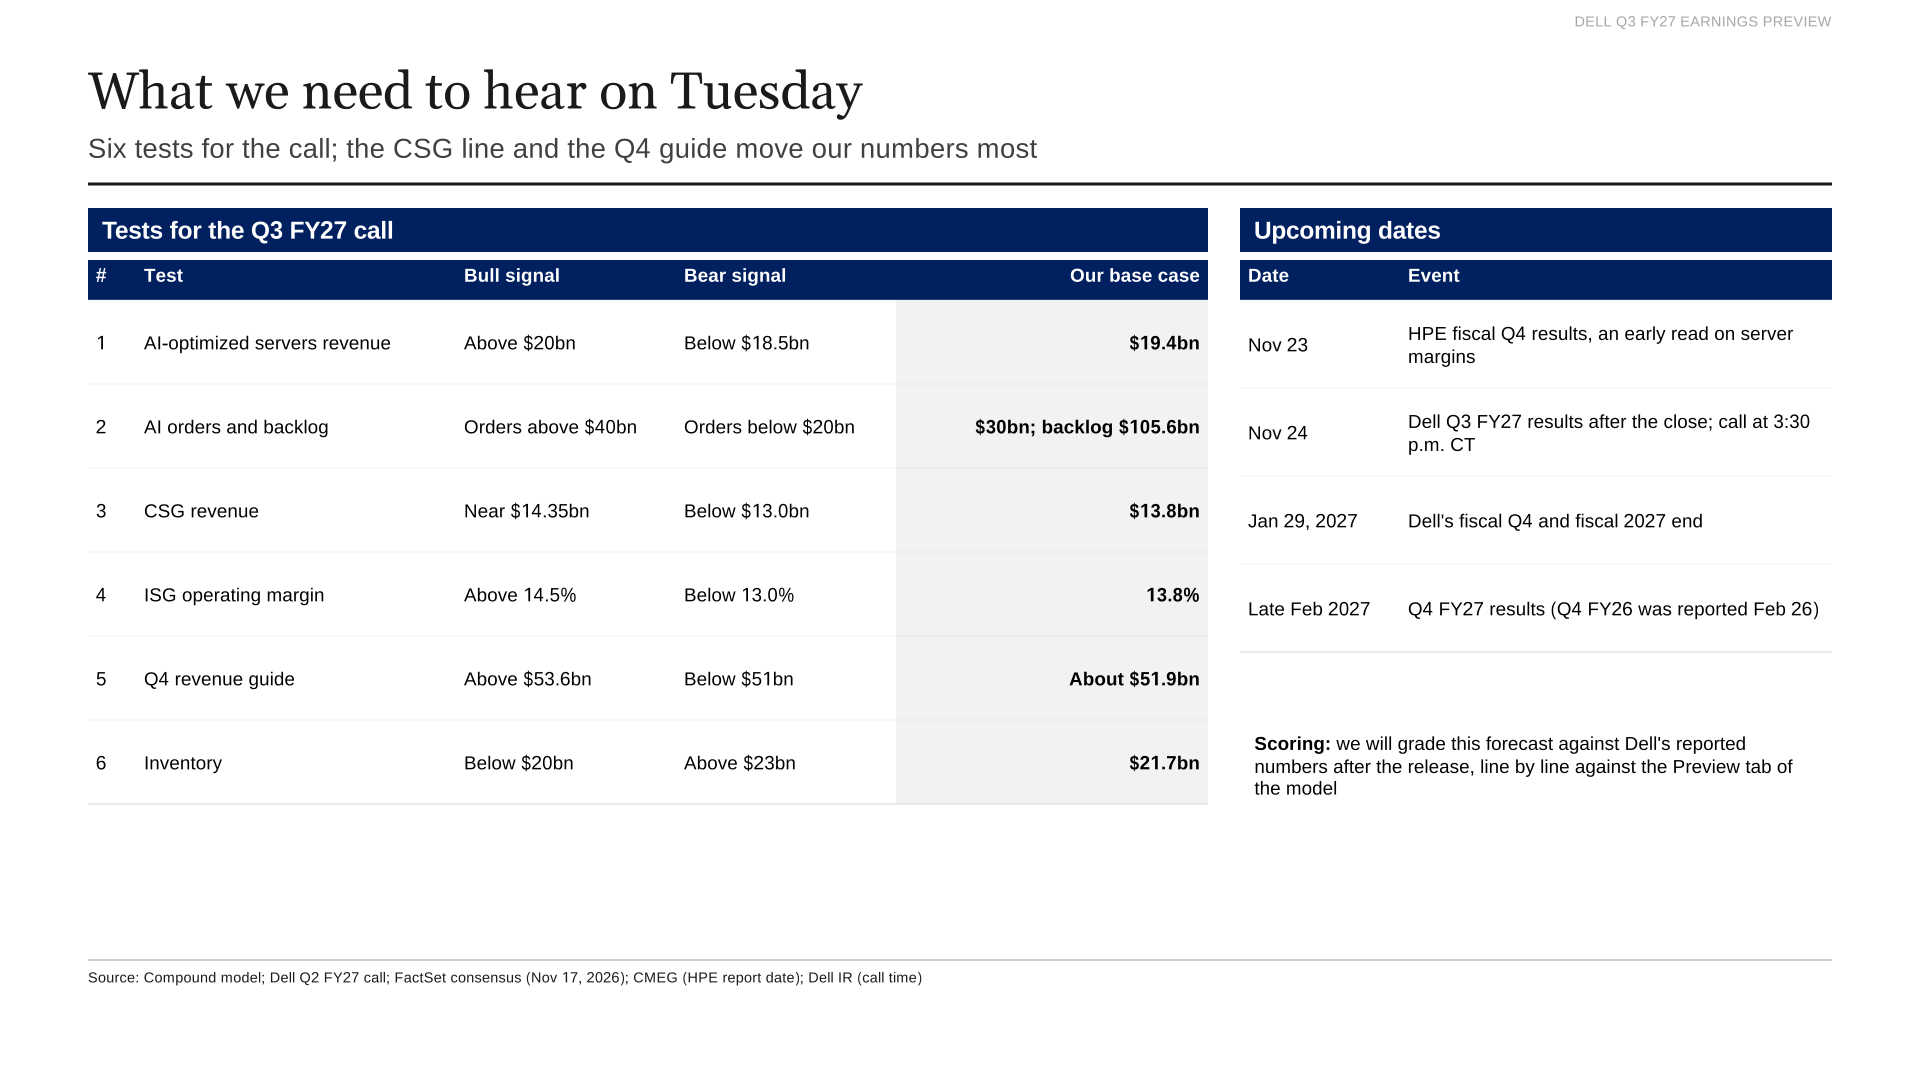
Six tests for the call, with what would support the bull and bear cases.
Hewlett Packard Enterprise reports its fiscal fourth quarter on Nov. 23, a day before Dell, CMEG reported. We will score this forecast against Dell's reported numbers after the release.
 Dell Q3 FY27 earnings preview deck (PowerPoint)The 11-page preview: executive summary, forecast against consensus, revenue build, AI orders and the Nvidia read-across, margins, the PC cross-check, the share price, cash flow, Q4 guidance and the checklist for the call, with editable charts and tables.Download · Free
 Dell Q3 FY27 earnings model (Excel)Quarterly model from Q1 FY26: segment and AI build, non-GAAP and GAAP income statements, cash flow, balance sheet and working capital, the guidance and consensus track record, Compound's Q3 and Q4 estimates, sensitivity tables and the AI servers and PC cross-check tab, with formulas and sources.Download · Free
More from Compound News
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Read article →
Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Read article →
Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Read article →