Intuit Q1 Earnings: $2.91 EPS vs $2.46 Consensus
Intuit's Q1 non-GAAP EPS of $2.91 beat the $2.46 consensus and our $2.57, and revenue of $4.354 billion came within $1 million of our forecast. A Q2 guide below consensus and a lower Credit Karma outlook sent shares down 13% after hours.
Intuit reported fiscal first-quarter non-GAAP EPS of $2.91 on Thursday, 18.2% above the FactSet consensus of $2.46 and 13.2% above Compound's forecast of $2.57, according to its earnings release.
Revenue rose 12% to $4.354 billion, against a $4.305 billion consensus and our $4.355 billion. Non-GAAP operating income was $1.05 billion, a 24.0% margin, above the $902 million to $915 million Intuit had guided and our $945 million.
Intuit guided second-quarter revenue to $4.931 billion to $4.954 billion and non-GAAP EPS to $3.17 to $3.22, below the $5.11 billion and $3.73 consensus and below the $5.09 billion and $3.55 we expected. It lowered its fiscal 2027 revenue range on Credit Karma, kept its profit ranges, and agreed to sell Mailchimp to Bending Spoons for about $3.68 billion.
Intuit shares fell 13.0% to $269.70 in after-hours trading, StreetAccount reported.
Results vs consensus vs Compound
| Q1 FY27 | Consensus | Compound | Actual | Actual vs consensus | Actual vs Compound |
|---|---|---|---|---|---|
| Revenue | $4,305M | $4,355M | $4,354M | +1.1% | 0.0% |
| Global Business Solutions | n/a | $3,053M | $3,083M | n/a | +1.0% |
| Online Ecosystem | n/a | $2,420M | $2,433M | n/a | +0.5% |
| Consumer | n/a | $987M | $958M | n/a | -3.0% |
| Credit Karma | n/a | $736M | $708M | n/a | -3.8% |
| Mailchimp | n/a | $314M | $313M | n/a | -0.3% |
| Non-GAAP operating income | $909M | $945M | $1,046M | +15.1% | +10.7% |
| Operating margin | 21.1% | 21.7% | 24.0% | +2.9 pt | +2.3 pt |
| Non-GAAP EPS | $2.46 | $2.57 | $2.91 | +18.2% | +13.2% |
| GAAP EPS | n/a | $1.83 | $2.59 | n/a | +41.6% |
| Cash from operations | n/a | $722M | $1,062M | n/a | +47.1% |
| Q2 revenue guidance midpoint | $5,110M | $5,093M | $4,943M | -3.3% | -3.0% |
| Q2 non-GAAP EPS guidance midpoint | $3.73 | $3.55 | $3.20 | -14.3% | -10.0% |
Consensus is the FactSet mean as of Nov. 17, as published in our preview; FactSet had no segment consensus on Intuit's new basis. Non-GAAP figures include share-based compensation. The guidance rows compare the midpoint Intuit issued on Nov. 19 with consensus for the quarter and with the guidance we expected.
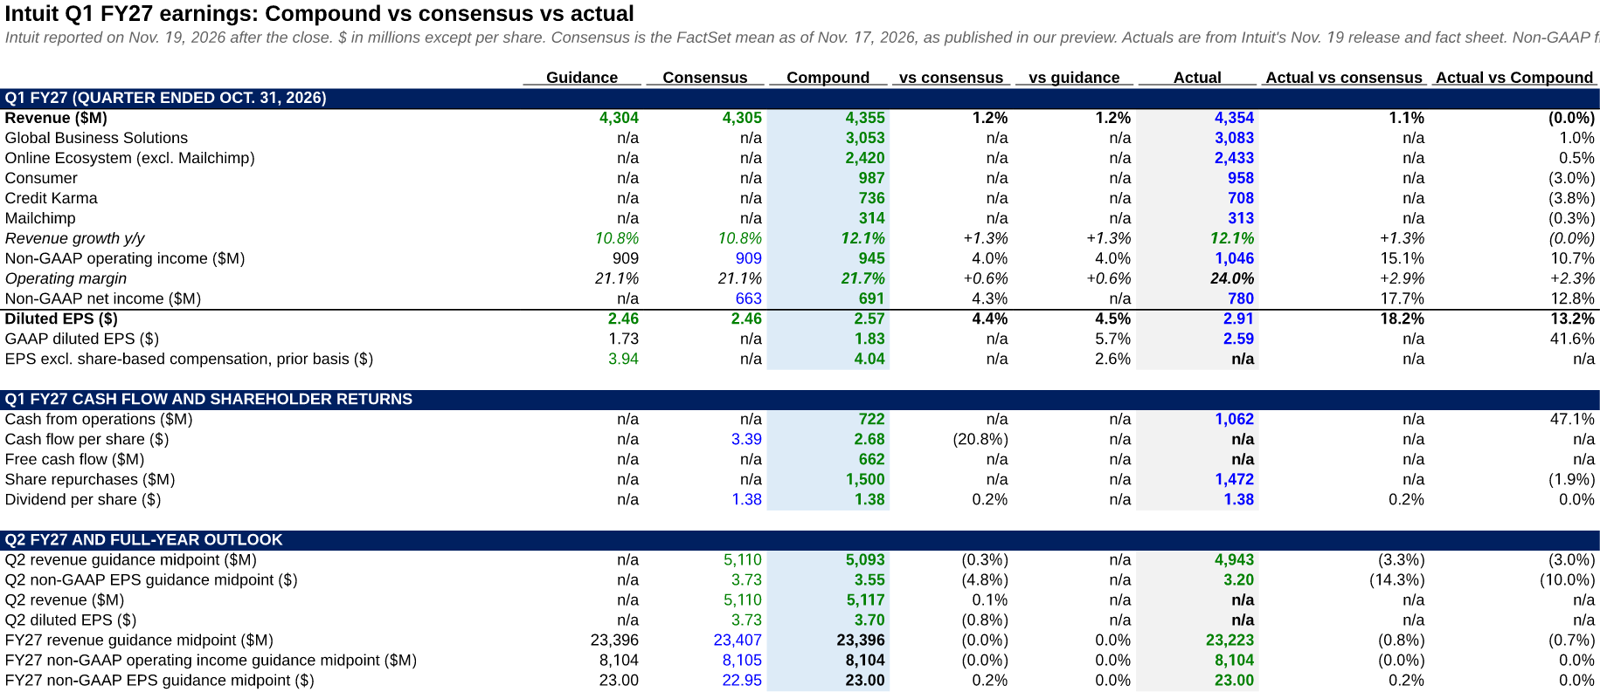
The Preview tab of our Excel model, now with the reported figures.
Guidance
For the second quarter, which ends Jan. 31, Intuit guided revenue to $4.931 billion to $4.954 billion, growth of 6% to 7%, and non-GAAP EPS to $3.17 to $3.22. The $4.94 billion revenue midpoint is 3.3% below the FactSet consensus of $5.11 billion, and the $3.20 EPS midpoint is 14.3% below the $3.73 consensus. We had expected about $5.09 billion and $3.55.
Intuit lowered its fiscal 2027 revenue guidance to $23.081 billion to $23.365 billion, from $23.279 billion to $23.512 billion, which it attributed to a change to Credit Karma. Credit Karma guidance fell to $2.721 billion to $2.826 billion, growth of 3% to 7%, from $2.919 billion to $2.973 billion. Intuit reiterated non-GAAP operating income of $8.063 billion to $8.145 billion and non-GAAP EPS of $22.88 to $23.12. FactSet consensus was $23.41 billion of revenue and $22.95 of EPS.
None of the guidance includes the Mailchimp sale, which Intuit expects to close in early calendar 2027. Intuit said it will update guidance at closing and use the cash proceeds to repurchase shares within fiscal 2027.
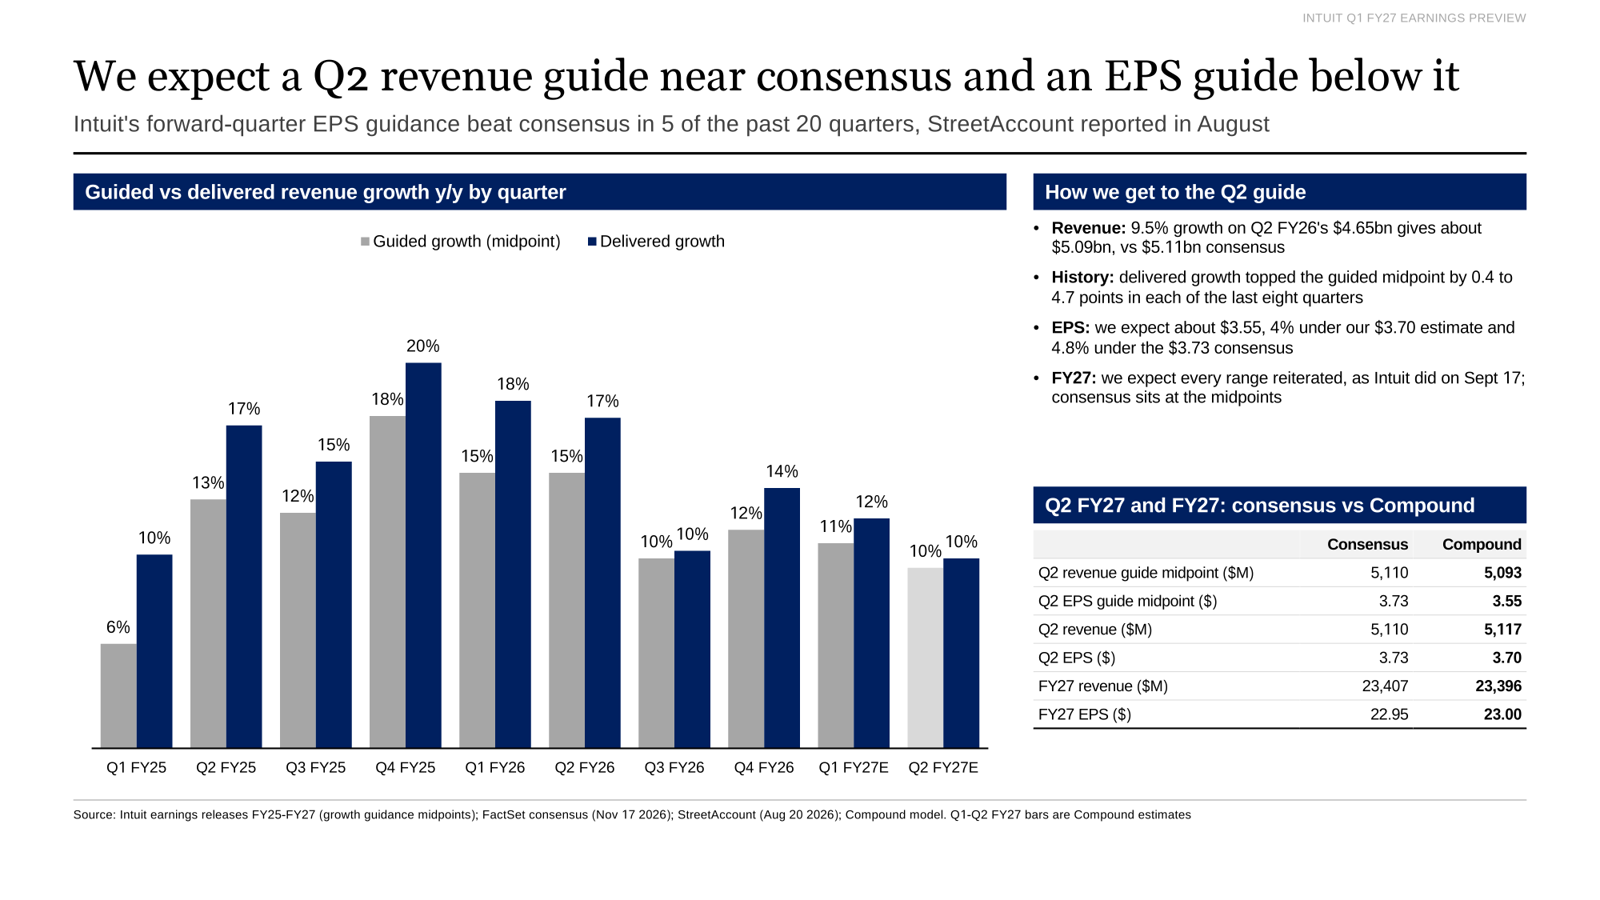
From our preview: the Q2 guide we expected, against Intuit's record of guiding below what it delivers.
What drove the quarter
Global Business Solutions revenue rose 15% to $3.083 billion, above the $3.02 billion StreetAccount consensus. QuickBooks Online Accounting grew 19% to $1.434 billion, "driven by higher effective prices, mix shift, and customer growth," Intuit said, and Online Services grew 21% to $999 million on money and payroll. Desktop Ecosystem grew 2% to $650 million.
Consumer revenue rose 7% to $958 million, below the $970.6 million StreetAccount consensus. Credit Karma grew 9% to $708 million, against a $719.0 million FactSet consensus that StreetAccount cited, after growing 27% a year earlier. TurboTax grew 1% to $199 million and ProTax 13% to $51 million. Mailchimp fell 1% to $313 million.
Non-GAAP costs rose 4.4% while revenue grew 12%. Research and development fell 6.5% to $788 million and general and administrative fell 9.5% to $382 million, both including stock pay. Selling and marketing rose 4.8% to $1.134 billion. Share-based compensation was $495 million, against $521 million in Intuit's guidance. Intuit had said in August that savings from its workforce changes would expand margins in fiscal 2027.
Segment operating margins were 76% in Global Business Solutions, 66% in Consumer and 65% in Mailchimp, according to Intuit's fact sheet. Bending Spoons will pay about $3.68 billion for Mailchimp: $3.31 billion in cash and $368 million in Bending Spoons stock, Intuit said. Mailchimp had $1.27 billion of revenue in fiscal 2026.
How our forecast did
Revenue: our $4.355 billion was $0.6 million above the actual. We assumed Intuit would beat its guidance midpoint by 1.2%, below its 2.6% average over eight quarters, and it beat by 1.2%. The mix was off. Business Solutions came in $30 million above our estimate and Consumer $29 million below, mostly Credit Karma, which grew 9% against our 13%. QuickBooks Online Accounting, at $1.434 billion, was $1 million from our figure.
Margin and EPS: we had non-GAAP costs up 7.6% and a 21.7% operating margin. Costs rose 4.4% and the margin was 24.0%. Research and development, which we had growing 7%, fell 6.5%. Higher operating income explains about $0.29 of the $0.34 gap between actual EPS and our $2.57; smaller non-GAAP other expense and a lower share count explain the rest.
Guidance: we expected the Q2 EPS guide to land 4.8% below consensus; it landed 14.3% below. We expected the fiscal 2027 ranges to be reiterated; the revenue range came down. We score each preview after the report; our Nvidia Q3 preview is the previous example.
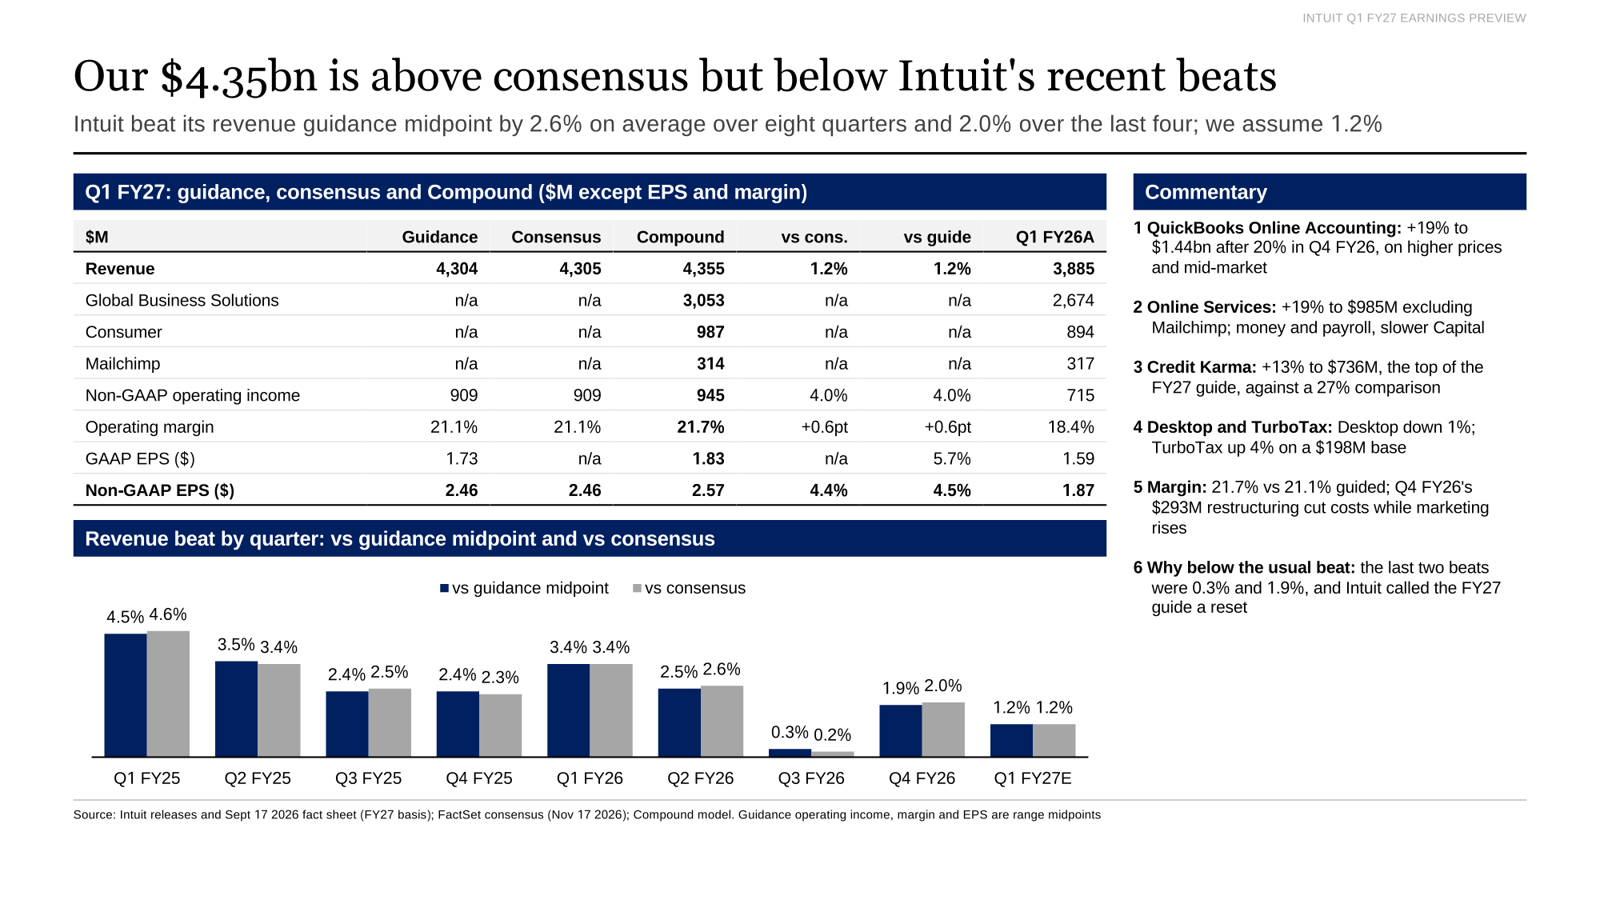
Our preview's forecast slide, published before the report.
Stock reaction
Intuit shares fell 13.0% to $269.70 in after-hours trading on Thursday, StreetAccount reported. They had closed the regular session at $310.02, down 10.3% from $345.56 on Nov. 16, the close used in our preview.
What to watch next
- The Q1 10-Q, with segment and lending detail; Intuit filed last year's on Nov. 20.
- The Mailchimp sale, expected to close in early calendar 2027, and the updated guidance Intuit will give at closing.
- Buybacks: Intuit had $6.4 billion of authorization left at Oct. 31 and plans to use the sale's cash proceeds for repurchases within fiscal 2027.
- Second-quarter results in late February 2027; the quarter ends Jan. 31, and Intuit reported last year's on Feb. 26.
- The fiscal third quarter, which ends April 30, 2027, when TurboTax's pricing changes meet the tax season.
 Intuit Q1 FY27 earnings model with actuals (Excel)Our preview model updated with Intuit's reported Q1 FY27 results: Actual, Actual vs consensus and Actual vs Compound columns, the Q2 and fiscal 2027 guidance issued Nov. 19, the quarterly model from Q1 FY25, sensitivity tables and the segments tab, with formulas and sources.Download · Free
 Intuit Q1 FY27 earnings preview deck (PowerPoint)The 11-page preview published before the report: executive summary, forecast against consensus, revenue build, margins, Q2 guidance, the low-end debate, the new reporting basis, share price, cash flow and the checklist for the call.Download · Free
More from Compound News
Intuit cut Mailchimp's costs 38% in a year, then sold it for 4.6 times profit
Mailchimp's segment expenses fell 38% in the year before Intuit agreed to sell it to Bending Spoons for $3.68 billion, lifting its margin to 65%. The price is 4.6 times annualized segment profit; Intuit trades at about 10.6 times and Bending Spoons at about 21.
Read article →
Alibaba Q2 Earnings: $1.21 EPS vs $1.63 Consensus
Alibaba's September-quarter non-GAAP EPS of RMB8.10 per ADS missed consensus by 25.6% and our forecast by 8.6%, while revenue of RMB271.5 billion beat both. The miss came below adjusted EBITA, as our preview expected.
Read article →
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint.
Read article →