Lowe's Q3 Earnings: $3.10 EPS vs $2.88 Consensus
Lowe's adjusted EPS of $3.10 beat the $2.88 consensus and our $2.94, but $0.34 came from tariff refunds. Comparable sales rose 1.8%, and Lowe's raised its sales outlook to about $92.5 billion while holding EPS at about $12.25.
Lowe's reported third-quarter adjusted EPS of $3.10 on Wednesday, above the FactSet consensus of $2.88 and Compound's forecast of $2.94. IEEPA tariff refunds added $0.34 a share, the company said; without them, adjusted EPS was $2.76, below both numbers.
Net sales were $22.76 billion, against a $22.39 billion consensus and our $22.50 billion. Comparable sales rose 1.8%, against StreetAccount's 0.1% consensus and our 0.3%.
Lowe's raised its fiscal 2026 sales outlook to about $92.5 billion from $92.0 billion and its comparable sales outlook to up about 0.5% from flat. It held adjusted EPS at about $12.25, as we expected. That implies fourth-quarter adjusted EPS of about $1.72, against consensus of $1.97.
Results vs consensus vs Compound
| Q3 FY26 | Consensus | Compound | Actual | Actual vs consensus | Actual vs Compound |
|---|---|---|---|---|---|
| Comparable sales | +0.1% | +0.3% | +1.8% | +1.7 pt | +1.5 pt |
| Net sales | $22.39B | $22.50B | $22.76B | +1.6% | +1.2% |
| Gross margin | 33.1% | 33.1% | 32.95% | -0.15 pt | -0.15 pt |
| SG&A, % of sales | 19.5% | 19.45% | 19.04% | -0.46 pt | -0.41 pt |
| Adjusted operating margin | 11.4% | 11.5% | 11.7% | +0.3 pt | +0.2 pt |
| Adjusted operating income | $2.55B | $2.59B | $2.67B | +4.6% | +3.3% |
| Adjusted EPS | $2.88 | $2.94 | $3.10 | +7.7% | +5.4% |
| Adjusted EPS excluding tariff refunds | $2.88 | $2.94 | $2.76 | -4.1% | -6.2% |
| Cash from operations | n/a | $1.50B | $1.68B | n/a | +11.9% |
| Free cash flow | n/a | $0.80B | $1.08B | n/a | +34.7% |
| FY26 adjusted EPS guidance | $12.27 | About $12.25 | About $12.25 | -0.1% | 0.0% |
Actuals are from Lowe's Nov. 18 release. Consensus is the FactSet mean as of Nov. 17; comps, margin and SG&A consensus is from StreetAccount's Nov. 16 metrics preview. Adjusted operating income is GAAP operating income of $2.58 billion plus $96 million of FBM and ADG amortization; GAAP operating margin was 11.3%. Third-quarter cash flow is the nine-month figure less the first half. The Compound column is our preview forecast of Nov. 16, unchanged.
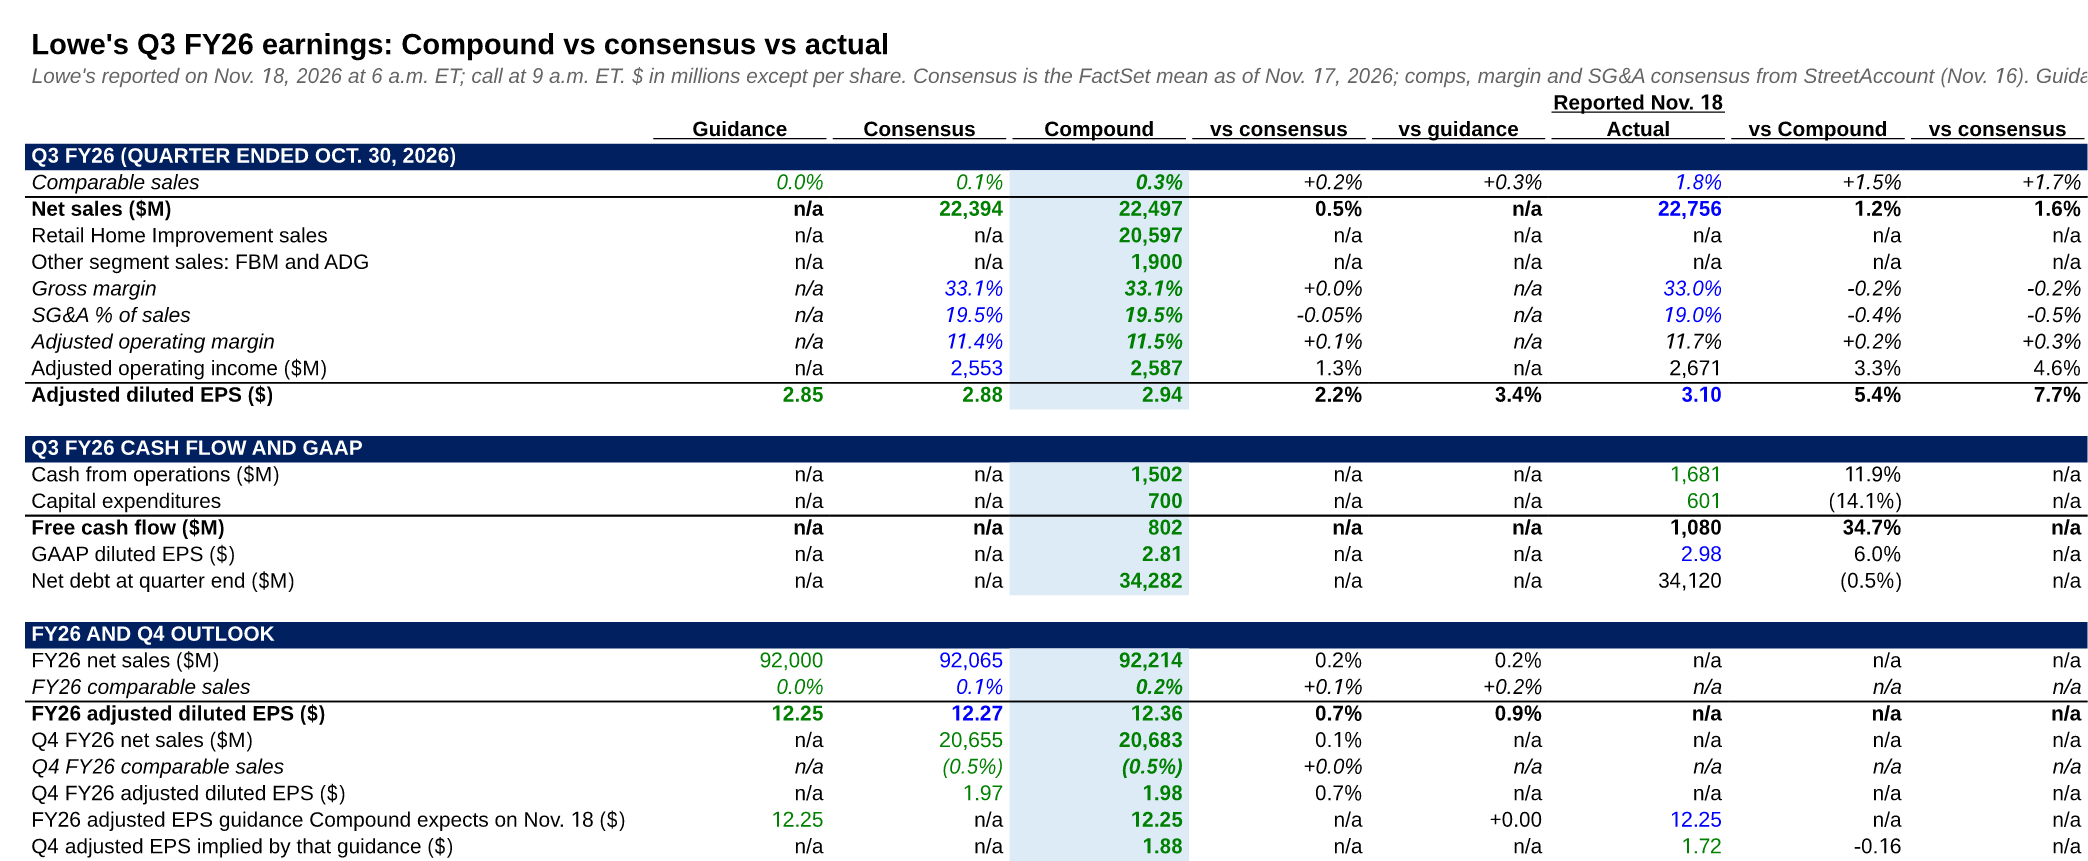
The Preview tab of our model, with the reported actuals added.
Guidance
| FY26 outlook | Prior (Aug. 19) | New (Nov. 18) | Consensus | Compound |
|---|---|---|---|---|
| Net sales | About $92.0B | About $92.5B | $92.07B | $92.21B |
| Comparable sales | Flat | Up about 0.5% | +0.1% | +0.2% |
| Adjusted operating margin | About 11.6% | About 11.5% | 11.6% | 11.7% |
| Adjusted EPS | About $12.25 | About $12.25 | $12.27 | $12.36 |
| GAAP diluted EPS | About $11.75 | About $11.75 | n/a | n/a |
| Net interest expense | About $1.6B | About $1.5B | n/a | n/a |
| Implied Q4 adjusted EPS | n/a | About $1.72 | $1.97 | $1.98 |
| Implied Q4 net sales | n/a | About $20.71B | $20.66B | $20.68B |
Lowe's said the update reflects results for the first three quarters, current demand trends and cost pressures across the business. The implied fourth quarter is the new guidance less reported results for the first three quarters. Holding $12.25 after a $3.10 third quarter leaves about $1.72 for the fourth, 12.7% below consensus. The higher sales outlook comes with a lower adjusted operating margin outlook, 11.5% from 11.6%, and the company cut its interest expense estimate to about $1.5 billion.
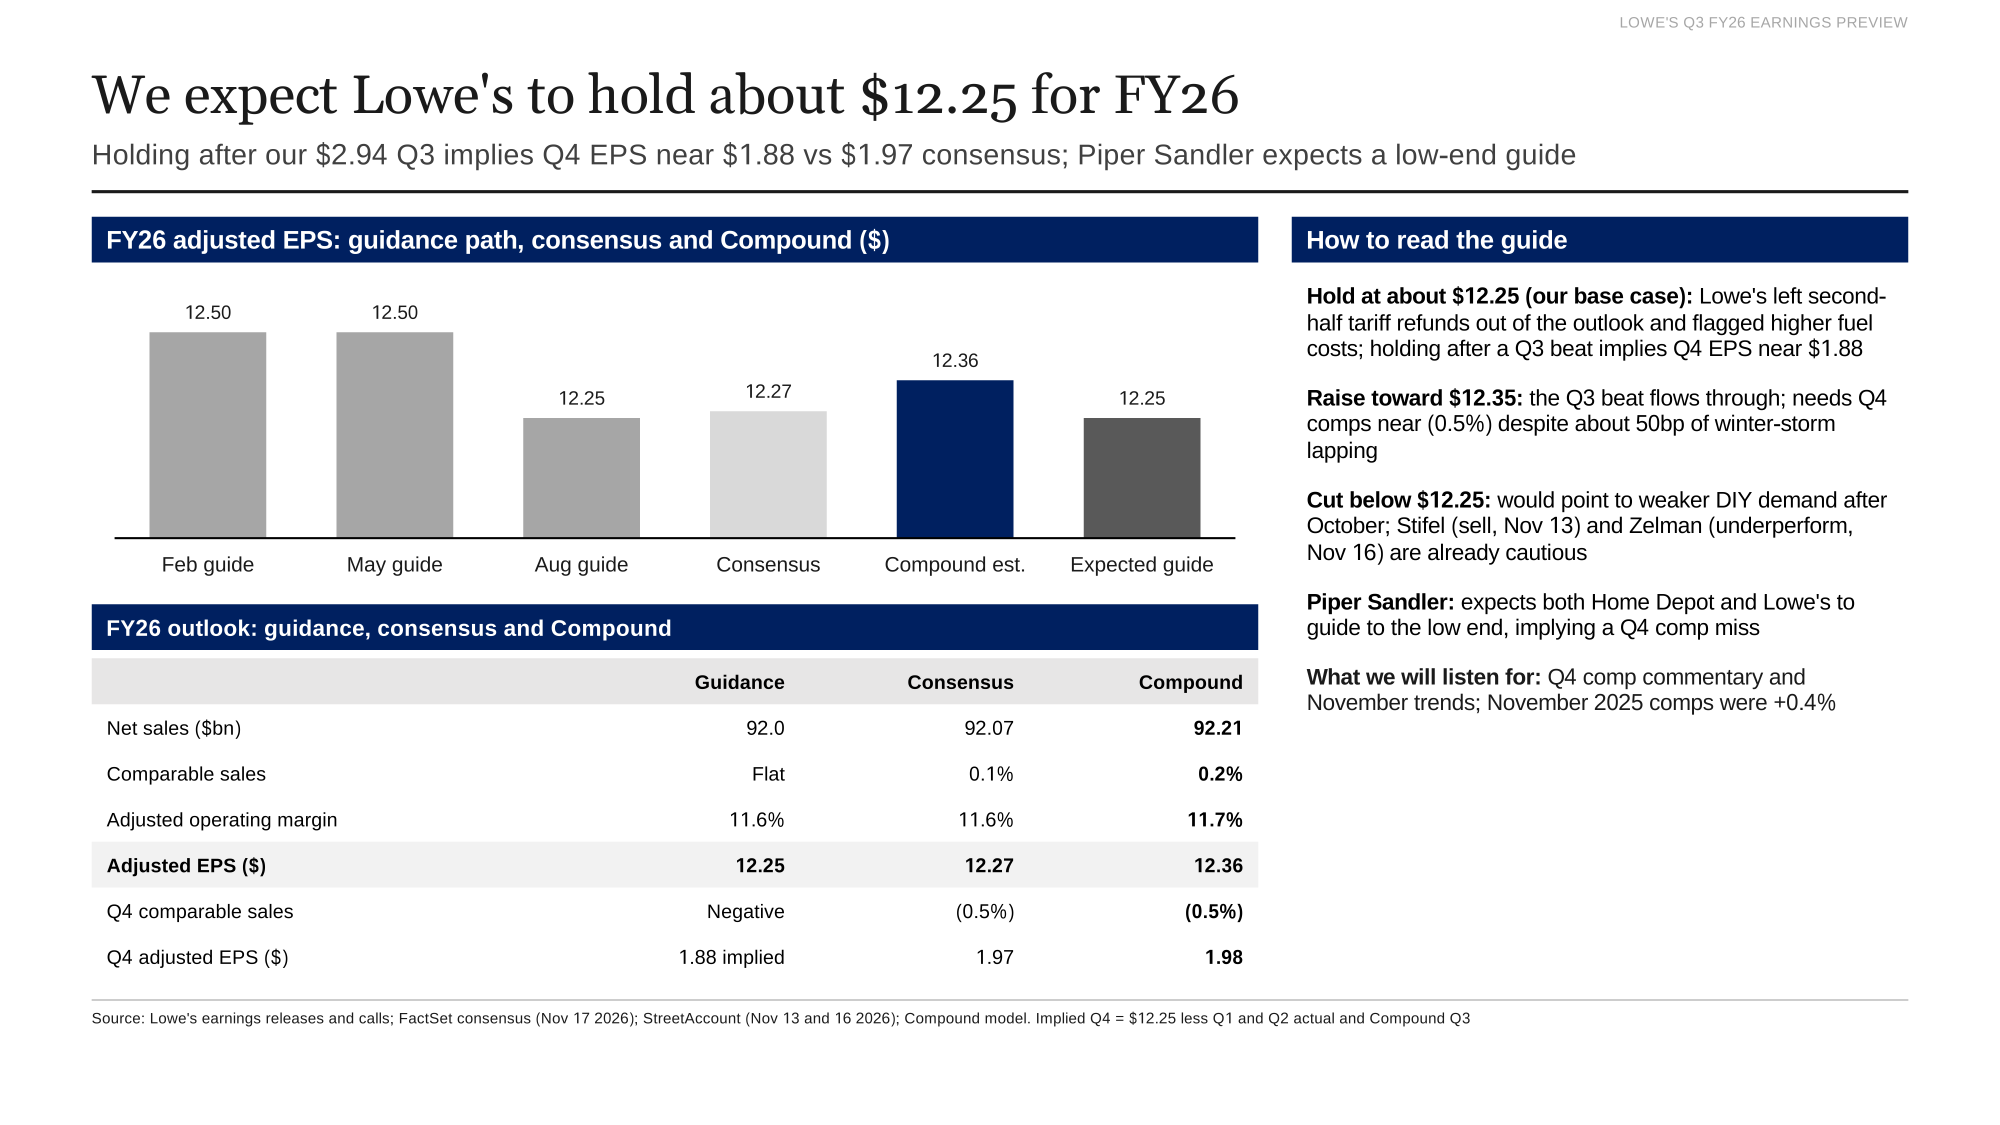
The guidance slide from our preview deck, prepared Nov. 16. Lowe's took the first path: a hold at about $12.25.
What drove the quarter
Lowe's said comparable sales were driven by a 17.4% increase in online sales and solid performance in Pro and home services. CEO Marvin Ellison called it the sixth consecutive quarter of positive comparable sales.
The company recognized a positive pre-tax impact of about $250 million from IEEPA tariff refunds, against about $80 million in the second quarter. The refunds are in both GAAP and adjusted EPS.
Gross margin was 32.95% of sales, down from 34.19% a year earlier, including the refunds. SG&A fell to 19.04% of sales from 19.99%. GAAP operating income rose to $2.58 billion from $2.48 billion. Net interest expense was $358 million, against $352 million a year earlier.
Merchandise inventory was $18.31 billion at Oct. 30, up from $17.18 billion a year earlier. Lowe's ended the quarter with $3.43 billion of cash, paid $701 million in dividends and operated 1,762 stores. The release does not split sales between the stores and the FBM and ADG segment; that comes in the 10-Q.
How our forecast did
We got the direction of EPS and the guidance call right, and the size of the comp wrong.
- Comparable sales: we forecast 0.3% and Lowe's reported 1.8%. On our $20.6 billion estimate of store sales, that 1.5-point gap alone is worth about $0.31 billion, more than our $0.26 billion sales miss, so the rest of the business came in a little below our forecast. The 10-Q will show the segment split.
- EPS: we forecast $2.94, a beat of 2.2%, and Lowe's beat by 7.7%. We assumed no tariff refunds because Lowe's had left them out of its outlook. Without the $0.34 of refunds, adjusted EPS was $2.76, 6.2% below our forecast and 4.1% below consensus.
- Margins: SG&A came in at 19.04% of sales against our 19.45%. Reported gross margin of 32.95% was 0.15 points below our 33.1% with about $250 million of refunds included. If the refunds sit in gross margin, as the $80 million did in the second quarter, the underlying gross margin was weaker than we modeled.
- Guidance: we expected Lowe's to hold about $12.25, and it did. We had estimated the implied fourth quarter at $1.88 on our own third quarter; on the reported $3.10 it is $1.72.
- Cash flow: third-quarter cash from operations was $1.68 billion and free cash flow $1.08 billion, above our $1.50 billion and $0.80 billion.
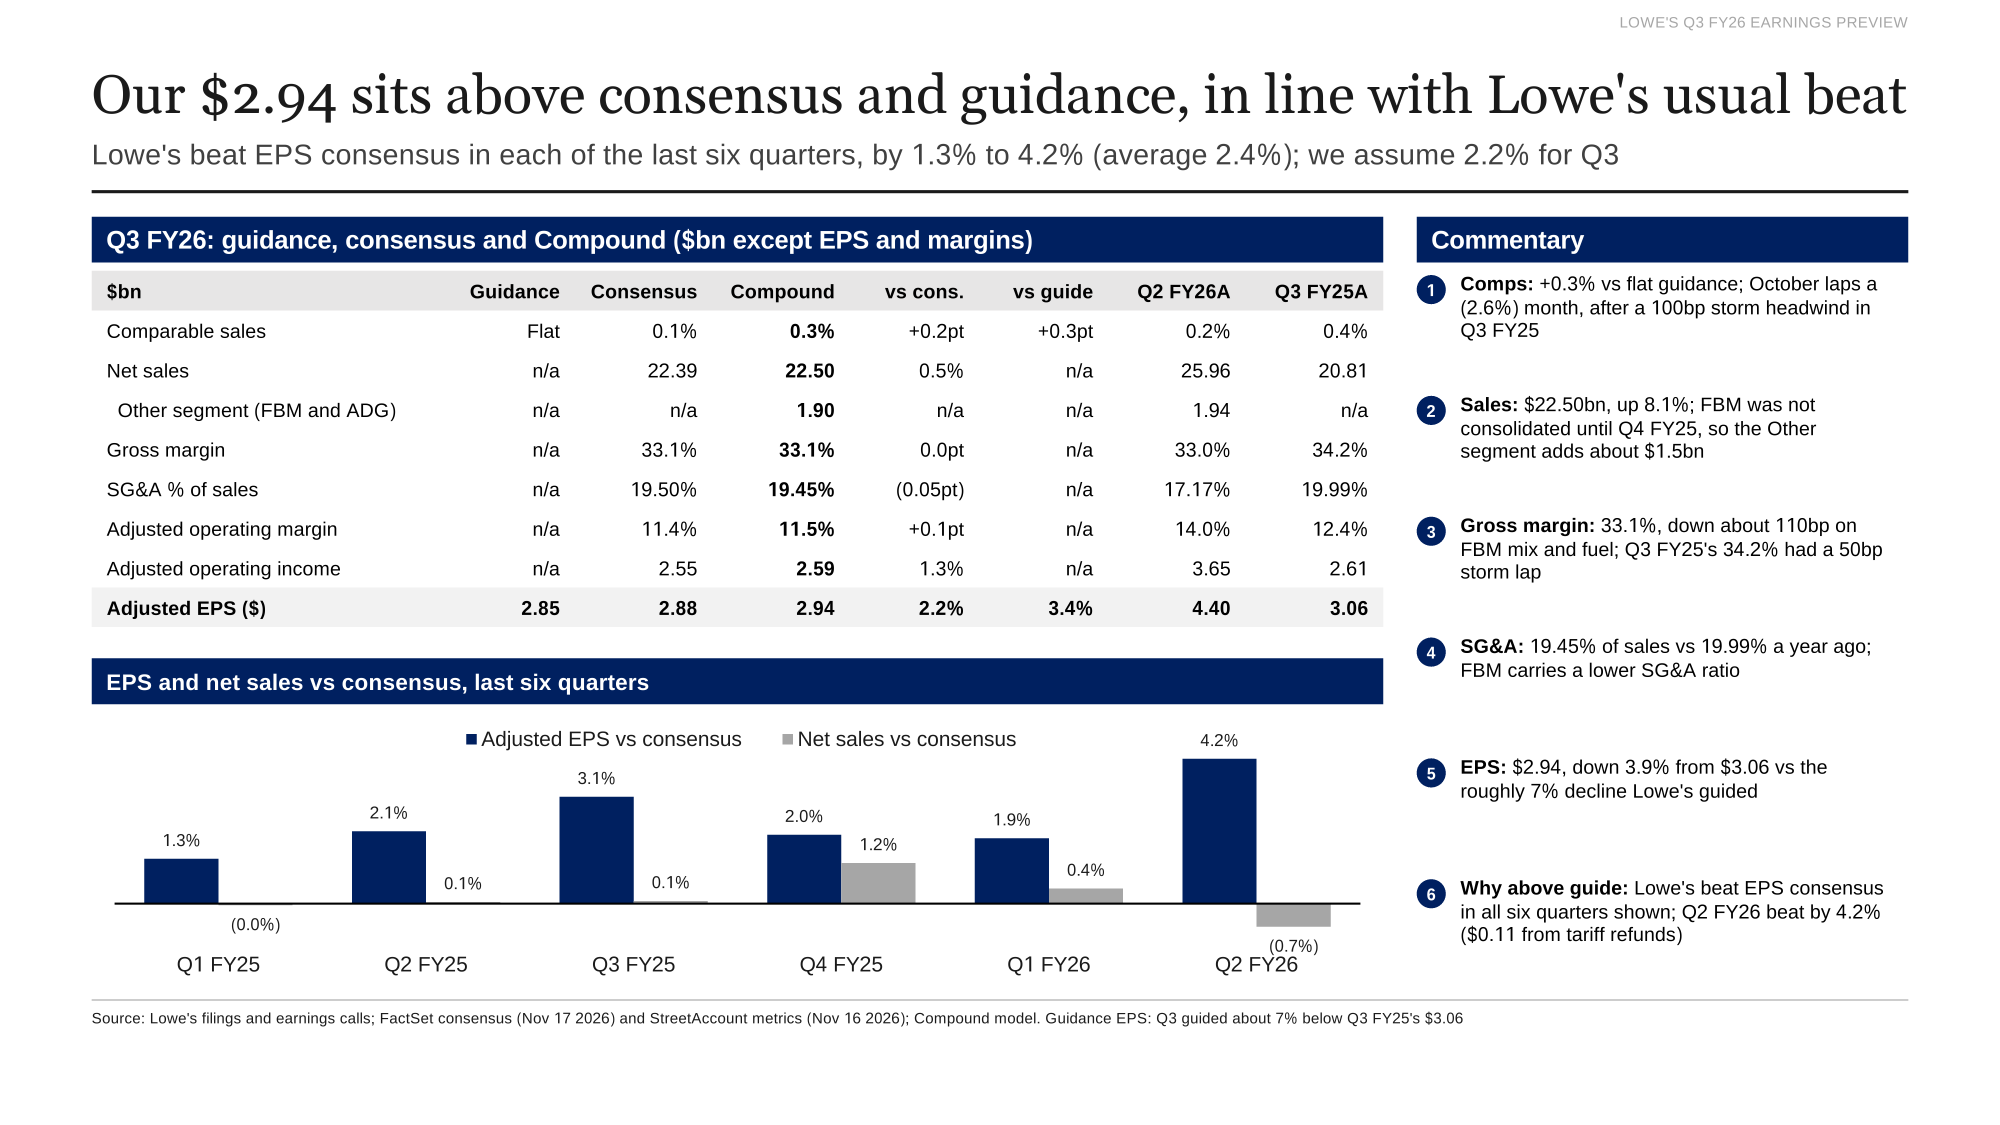
Our forecast slide from the preview deck, prepared Nov. 16.
Stock reaction
Lowe's closed at $220.46 on Nov. 17, according to FactSet prices. Shares were down about 1.4% after the release, Investing.com reported before the open.
What to watch next
- Nov. 18, 9 a.m. ET: the earnings call. Watch for comparable ticket and transactions, how much of the tariff refunds Lowe's plans to reinvest, and what it says about fourth-quarter comps.
- The third-quarter 10-Q, which will split sales and operating income between Retail Home Improvement and the FBM and ADG segment. Lowe's filed last year's third-quarter 10-Q on Nov. 26.
- December: Lowe's Analyst and Investor Conference, where the company said it will discuss its growth opportunities.
- Feb. 24, 2027 (expected): fourth-quarter results, against an implied adjusted EPS of about $1.72.
Our Nvidia third-quarter preview used the same model-and-deck format. The updated Lowe's model and our preview deck are free to download below.
 Lowe's Q3 FY26 earnings model with actuals (Excel)Our quarterly model from Q1 FY25 with the reported Q3 FY26 actuals added to the Preview tab beside guidance, consensus and our forecast, the updated FY26 guidance and implied Q4, plus the revenue build, income statements, cash flow, balance sheet, sensitivity tables and the housing and acquisitions tab, with formulas and sources.Download · Free
 Lowe's Q3 FY26 earnings preview deck (PowerPoint)The 11-page preview we prepared before the report: executive summary, forecast against consensus, revenue build, track record, margins, guidance, housing and the FBM and ADG acquisitions, the share price, cash flow and the checklist.Download · Free
More from Compound News
TJX Q3 Earnings: $1.34 EPS vs $1.34 Consensus
TJX matched the $1.34 consensus on adjusted EPS and beat on sales and comparable sales, but cut its fourth-quarter outlook on fuel costs. Our $1.36 forecast was $0.02 too high.
Read article →
Target Q3 Earnings: $2.65 EPS vs $2.08 Consensus
Target's third-quarter EPS of $2.65 included $0.50 of tariff refunds; excluding them, $2.15 beat the $2.08 consensus and our $2.10. Sales of $27.07 billion beat both, and Target raised its full-year outlook.
Read article →
Best Buy Q3 Earnings Preview: $1.52 EPS vs $1.49 Consensus
Best Buy reports Tuesday before the open. Our model has comparable sales up 2.6%, inside the 1% to 3% guide.
Read article →