TJX Q3 Earnings: $1.34 EPS vs $1.34 Consensus
TJX matched the $1.34 consensus on adjusted EPS and beat on sales and comparable sales, but cut its fourth-quarter outlook on fuel costs. Our $1.36 forecast was $0.02 too high.
TJX Companies reported fiscal third-quarter adjusted EPS of $1.34 on Wednesday, Nov. 18, matching the FactSet consensus of $1.34 and $0.02 below Compound's $1.36 forecast. Net sales of $15.95 billion beat the $15.82 billion consensus and our $15.90 billion estimate, according to the company's release.
Comparable sales rose 4%, above the 3.0% StreetAccount consensus, our 3.2% and the 2% to 3% TJX had planned. Marmaxx comps rose 2%, after 1% in the second quarter. GAAP EPS was $1.39, including a $0.05 net benefit from tariff refunds.
TJX lowered its fourth-quarter adjusted EPS outlook to $1.42 to $1.45, below the $1.48 FactSet consensus, on higher fuel costs, and set its full-year range at $5.17 to $5.20, from $5.15 to $5.20.
Results vs consensus and our forecast
| Q3 FY27 | Consensus | Compound | Actual | Actual vs consensus | Actual vs Compound |
|---|---|---|---|---|---|
| Net sales ($bn) | 15.82 | 15.90 | 15.95 | +0.9% | +0.3% |
| Comparable sales | +3.0% | +3.2% | +4% | +1.0 pts | +0.8 pts |
| Marmaxx comp | +1.4% | +1.5% | +2% | +0.6 pts | +0.5 pts |
| HomeGoods comp | +4.9% | +6.0% | +5% | +0.1 pts | -1.0 pts |
| TJX Canada comp | +4.4% | +5.0% | +6% | +1.6 pts | +1.0 pts |
| TJX International comp | +5.6% | +6.0% | +8% | +2.4 pts | +2.0 pts |
| Adjusted gross margin | 32.4% | 32.3% | 32.1% | -0.3 pts | -0.2 pts |
| Adjusted SG&A % of sales | 20.1% | 19.9% | 19.8% | -0.3 pts | -0.1 pts |
| Adjusted pretax margin | 12.6% | 12.6% | 12.5% | -0.1 pts | -0.1 pts |
| Adjusted EPS | $1.34 | $1.36 | $1.34 | $0.00 | -$0.02 |
| GAAP EPS | n/a | $1.41 | $1.39 | n/a | -$0.02 |
Consensus is the FactSet mean as of Nov. 17; comparable sales, division and margin consensus is from StreetAccount. Compound figures are from our Nov. 17 preview. Adjusted figures exclude tariff refunds and the related bonus accruals, as TJX reports them.
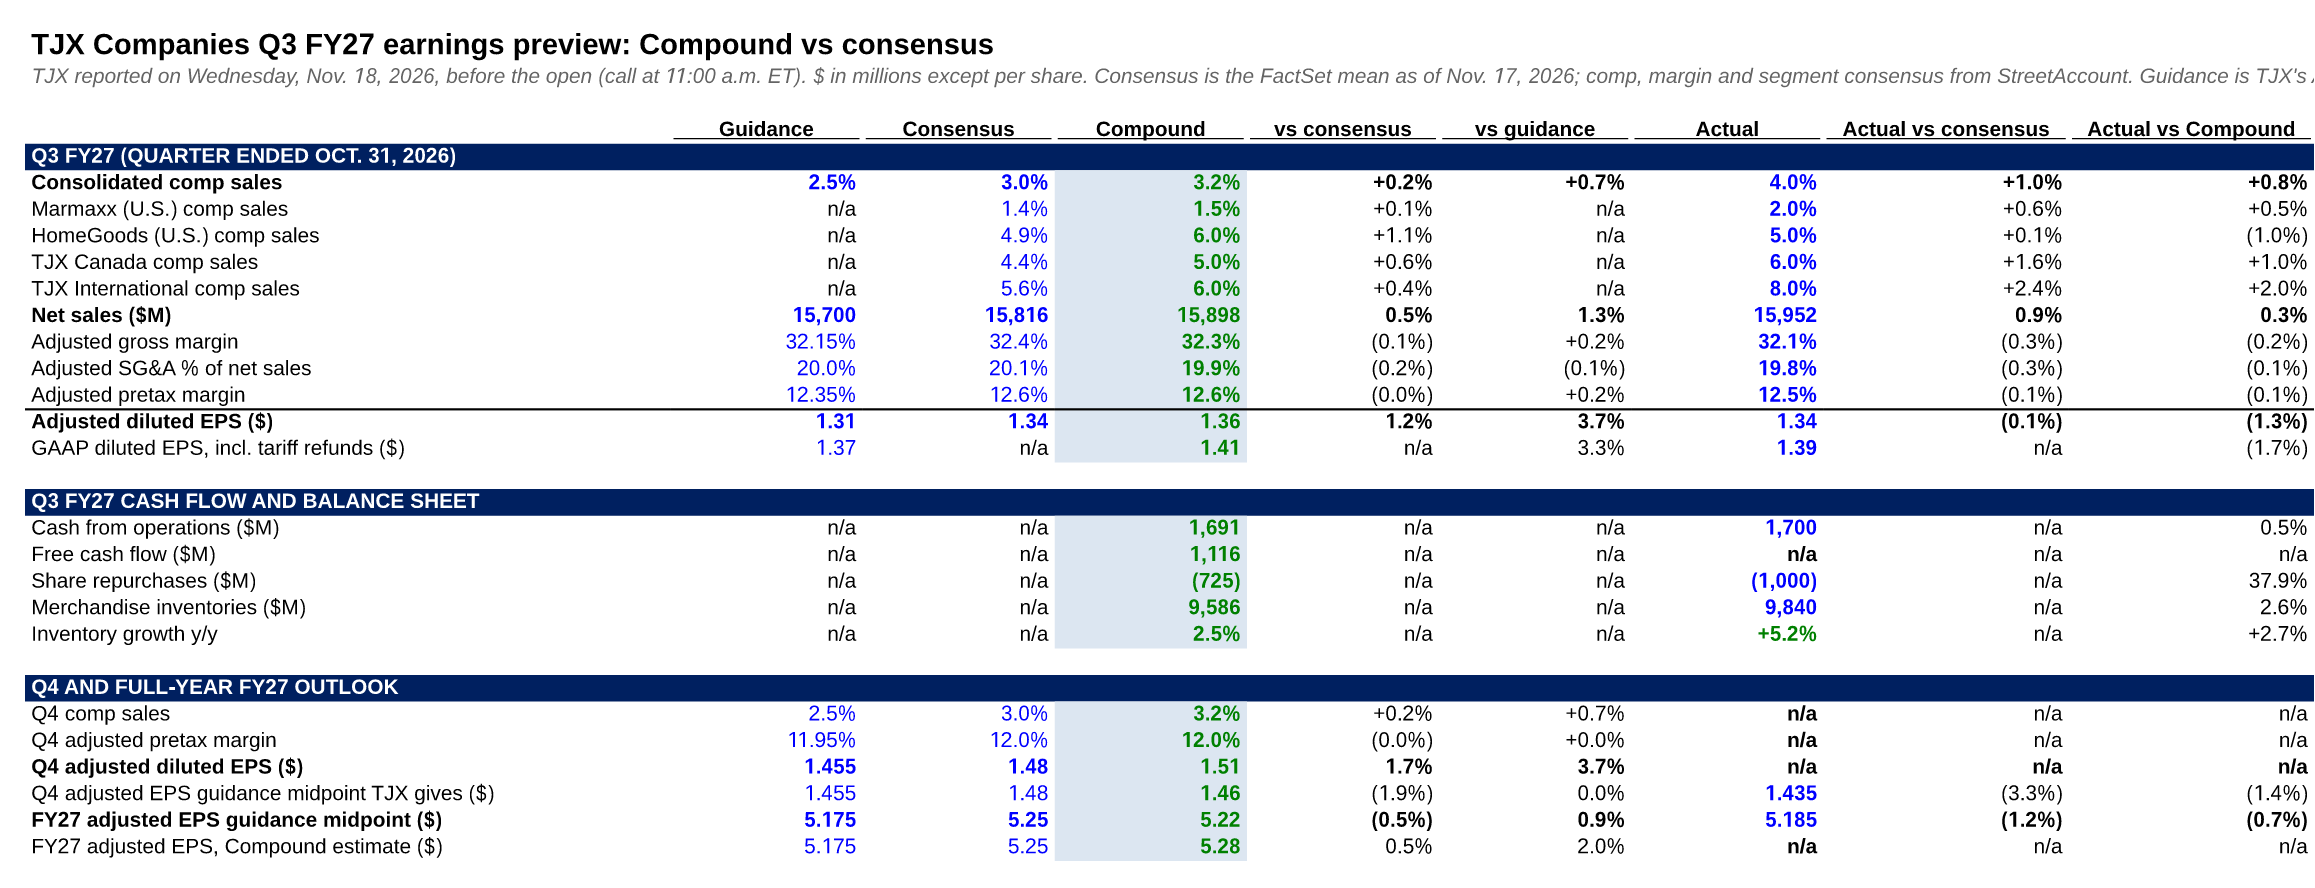
The Preview tab of our model, now with TJX's reported figures beside our estimates and consensus.
Guidance
For the fourth quarter, TJX plans comparable sales up 2% to 3%, adjusted pretax margin of 11.8% to 11.9% and adjusted EPS of $1.42 to $1.45. The company said the outlook now assumes more fuel cost than its prior guidance. In August, TJX's full-year and third-quarter ranges implied $1.44 to $1.47 for the fourth quarter. FactSet consensus was $1.48, and our model had $1.51.
For fiscal 2027, TJX now expects comparable sales up 4%, from 3% to 4%, adjusted pretax margin of 12.0% to 12.1% and adjusted EPS of $5.17 to $5.20. FactSet consensus was $5.25, and we had expected a range of about $5.20 to $5.25. GAAP EPS guidance is $5.33 to $5.36. TJX now plans about $3.0 billion of buybacks this year, the top of its earlier $2.75 billion to $3.0 billion range.
| Outlook | New guidance | Before the report | Consensus | Compound |
|---|---|---|---|---|
| Q4 adjusted EPS | $1.42-$1.45 | $1.44-$1.47 | $1.48 | $1.51 |
| Q4 comparable sales | +2% to +3% | +2% to +3% | +3.0% | +3.2% |
| Q4 adjusted pretax margin | 11.8%-11.9% | 11.9%-12.0% | 12.0% | 12.0% |
| FY27 adjusted EPS | $5.17-$5.20 | $5.15-$5.20 | $5.25 | $5.20-$5.25 expected range |
| FY27 comparable sales | +4% | +3% to +4% | +3.8% | n/a |
What drove the quarter
Overall sales, profitability, and earnings per share all exceeded our expectations. Consolidated comparable sales grew 4%, driven by continued strength at HomeGoods, TJX Canada, and TJX International, and we saw improved sales at Marmaxx.
CEO Ernie Herrman said that in the release. TJX International comps rose 8% and TJX Canada 6%. HomeGoods rose 5%, matching its gain a year earlier, and Marmaxx's 2% came on top of a 6% gain a year earlier. Net sales grew 3% at Marmaxx to $9.33 billion, 8% at HomeGoods and TJX Canada, and 11% at TJX International.
Adjusted gross margin fell 0.5 points to 32.1%, which TJX attributed to higher freight and fuel costs. Adjusted SG&A improved 0.3 points to 19.8% of sales, on lower incentive compensation accruals and the lapping of a contribution to the TJX Foundation a year earlier. Adjusted pretax margin was 12.5%, down 0.2 points from a year earlier.
TJX received $132 million of IEEPA tariff refunds in the quarter, $463 million so far this fiscal year, and accrued $55 million of related bonuses, for a net pretax benefit of $77 million. It expects no further refunds in the fourth quarter. Inventories were $9.8 billion, flat per store. TJX repaid its $1.0 billion note on Sept. 15, returned $1.5 billion to shareholders and ended the quarter with 5,349 stores, 64 more than at the start of the quarter.
Looking at the fourth quarter, Herrman said unseasonably warm weather in the U.S. and Canada has held back demand in some categories, and that TJX expects sales momentum to accelerate through the holiday season.
How our forecast did
We had the top line and the direction of the comp right. Net sales came in $0.05 billion above our estimate and comparable sales 0.8 points above it. The international divisions did most of that: we had TJX International at 6% and it reported 8%, and TJX Canada at 5% against 6% reported. Our Marmaxx call of 1.5% was half a point light, and HomeGoods at 5% was a point below our 6%.
We had the margin wrong. We modeled adjusted gross margin of 32.3%, above TJX's 32.1% to 32.2% guide, and it came in at 32.1%, the bottom of the range, as freight and fuel costs rose. Lower SG&A recovered part of the gap, but adjusted pretax margin finished at 12.5% against our 12.6%, and adjusted EPS at $1.34 against our $1.36.
We expected a smaller beat than usual, and it was smaller still: adjusted EPS beat the midpoint of TJX's guidance by 2.3%, against our 3.7% and 4.5% to 21.4% in each of the six prior quarters. Our tariff assumptions were close, with $125 million of refunds and $42 million of accruals against $132 million and $55 million reported. Our guidance call missed: we expected TJX to hold the fourth quarter and lift the full-year range to about $5.20 to $5.25, and it lowered the fourth quarter instead.
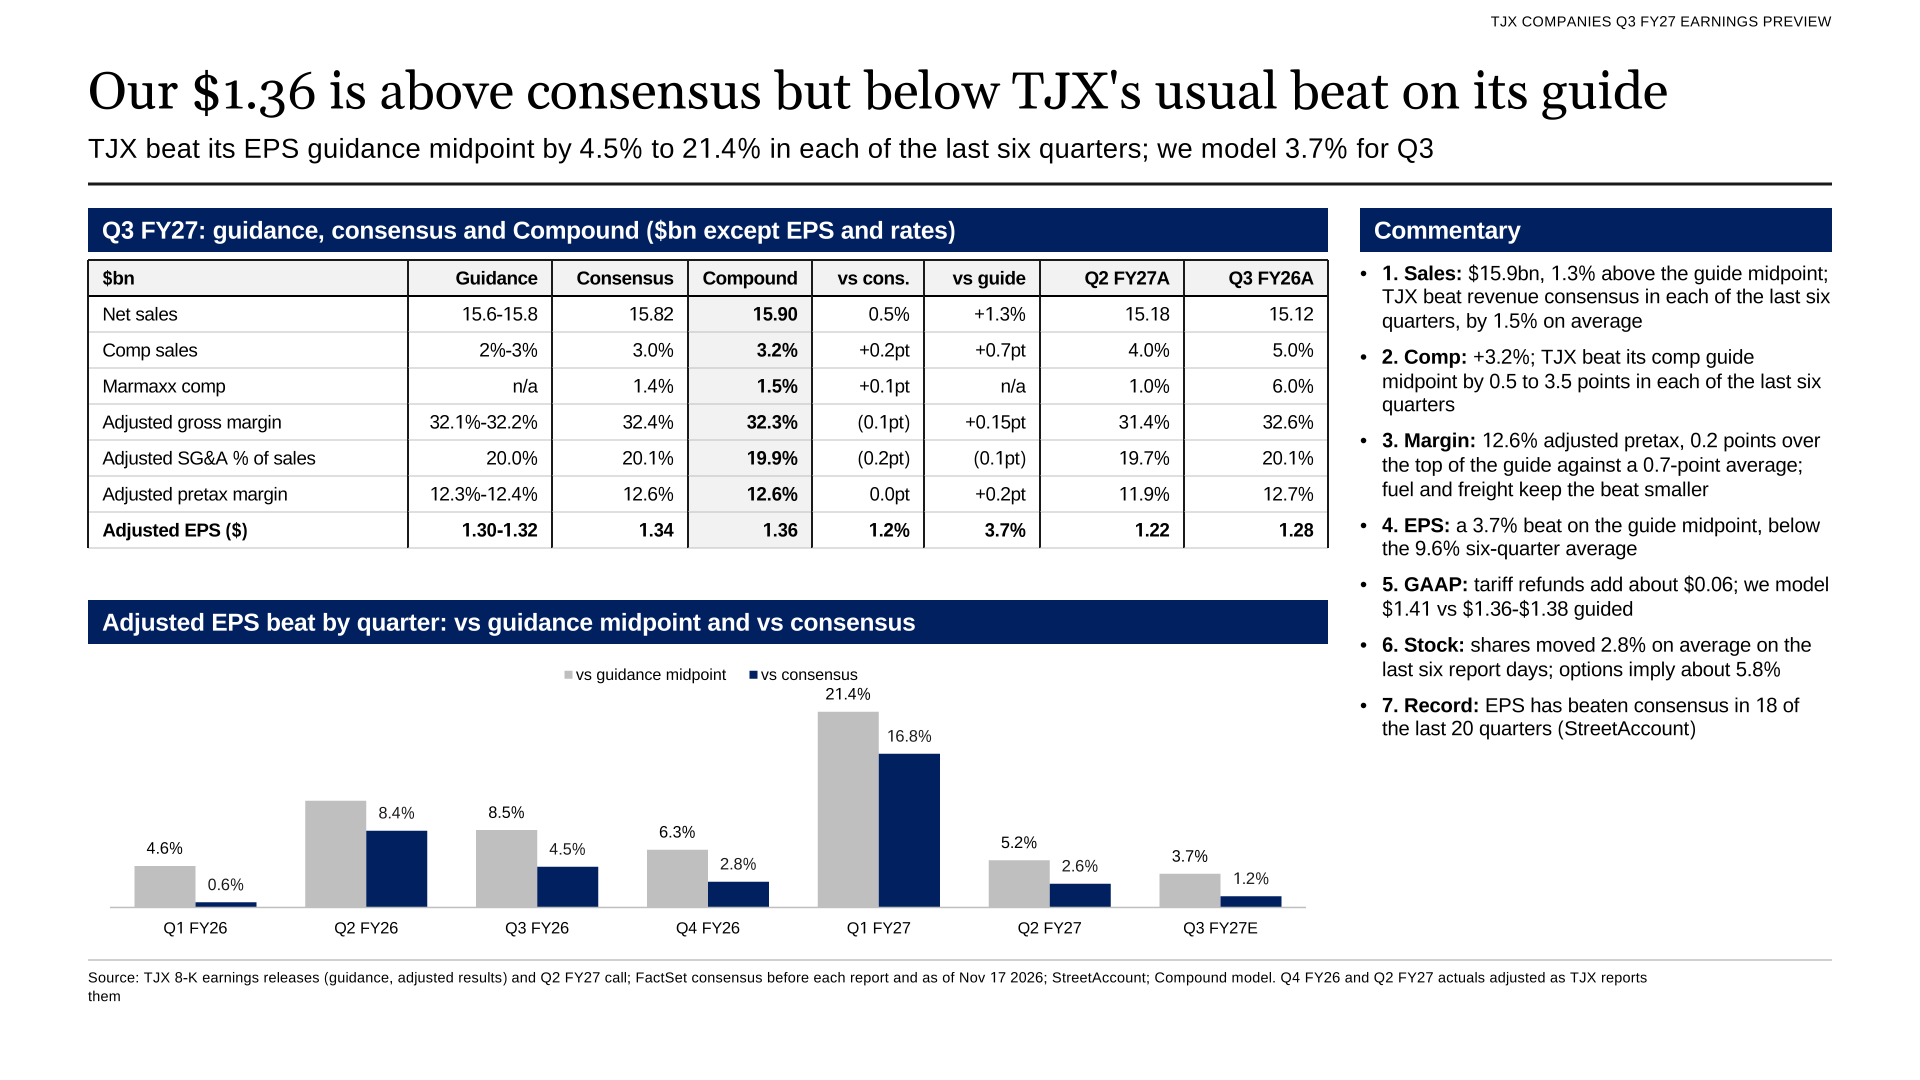
Slide 3 of our Nov. 17 preview deck: the forecast and TJX's EPS beat history going into the report.
We score our previews against results; our NVIDIA third-quarter preview is another example.
Stock reaction
TJX shares closed at $129.85 on Nov. 17, down 13.9% from $150.85 on Aug. 18, the last close before the second-quarter report, according to FactSet prices. Pre-market trading was thin when we published, and we had no reliable quote for the move. Options had priced a move of about 5.8%, StreetAccount reported on Nov. 16.
What to watch next
- Nov. 18, 11:00 a.m. ET: TJX's earnings call. Listen for November trading, the Marmaxx trend and how much extra fuel cost is in the fourth-quarter guide.
- Nov. 19, after the close: Ross Stores reports third-quarter results, according to FactSet's calendar.
- Nov. 24, before the open: Burlington Stores reports third-quarter results.
- Holiday season: whether sales pick up after the warm start Herrman described, with Marmaxx expected to improve further in the fourth quarter.
- Late February: fourth-quarter results. TJX reported last year's fourth quarter on Feb. 25, 2026; fiscal 2027 ends Jan. 30, 2027.
 TJX Q3 FY27 earnings model with actuals (Excel)Our preview model with TJX's reported Q3 results added on the Preview tab: division sales and comps, adjusted and GAAP income statements, cash flow, balance sheet, guidance and consensus track record, sensitivity tables and the tariff refund analysis, with formulas and sources.Download · Free
 TJX Q3 FY27 earnings preview deck (PowerPoint)The ten-slide preview deck published before the report: forecast vs consensus, track record, division sales, margins, the FY27 guide, the EPS bridge and tariff refunds, the share price, cash flow and what to watch.Download · Free
More from Compound News
Target Q3 Earnings: $2.65 EPS vs $2.08 Consensus
Target's third-quarter EPS of $2.65 included $0.50 of tariff refunds; excluding them, $2.15 beat the $2.08 consensus and our $2.10. Sales of $27.07 billion beat both, and Target raised its full-year outlook.
Read article →
Lowe's Q3 Earnings: $3.10 EPS vs $2.88 Consensus
Lowe's adjusted EPS of $3.10 beat the $2.88 consensus and our $2.94, but $0.34 came from tariff refunds. Comparable sales rose 1.8%, and Lowe's raised its sales outlook to about $92.5 billion while holding EPS at about $12.25.
Read article →
Best Buy Q3 Earnings Preview: $1.52 EPS vs $1.49 Consensus
Best Buy reports Tuesday before the open. Our model has comparable sales up 2.6%, inside the 1% to 3% guide.
Read article →