Ross Stores Q3 Earnings: $1.91 EPS vs $1.87 Consensus
Ross Stores beat the $1.87 consensus and our $1.89 forecast with EPS of $1.91 on an 8% comp, then trimmed its fourth-quarter EPS guide by a cent. The new full-year range of $8.75 to $8.84 came in a cent below what we expected.
Ross Stores reported fiscal third-quarter EPS of $1.91 on Thursday, Nov. 19, above the FactSet consensus of $1.87, Compound's $1.89 forecast and the company's guidance of $1.75 to $1.83, according to its earnings release. Sales rose 12% to $6.26 billion, against $6.25 billion consensus and our $6.27 billion.
Comparable store sales rose 8% on top of a 7% gain a year earlier, driven primarily by customer traffic, Ross said. That was half a point below our 8.5% forecast and a tenth of a point below the 8.1% FactSet comp consensus StreetAccount cited after the release. Operating margin was 12.3%, up 70 basis points and above the company's 11.7% to 12.0% plan.
Ross trimmed its fourth-quarter EPS outlook to $2.16 to $2.25, from $2.17 to $2.26, below the $2.27 consensus, and kept its comparable sales outlook at 4% to 5%. It raised its fiscal 2026 EPS range to $8.75 to $8.84, from $8.61 to $8.77. The shares fell 6.6% to $205.35 in after-hours trading, StreetAccount reported.
Results vs consensus and our forecast
| Q3 FY26 | Consensus | Compound | Actual | Actual vs consensus | Actual vs Compound |
|---|---|---|---|---|---|
| Sales | $6.25B | $6.27B | $6.26B | +0.1% | -0.3% |
| Comparable store sales | n/a | +8.5% | +8% | n/a | -0.5 pts |
| Operating margin | 12.2% | 12.3% | 12.3% | +4 bps | -2 bps |
| Operating income | $763M | $770M | $767M | +0.4% | -0.4% |
| EPS | $1.87 | $1.89 | $1.91 | +$0.04 | +$0.02 |
| Q4 EPS | $2.27 | $2.29 | $2.16-$2.25 guide | -$0.07 at midpoint | -$0.09 at midpoint |
| FY26 EPS, incl. Q2 refunds | $8.50 | $8.86 | $8.75-$8.84 guide | +$0.30 at midpoint | -$0.07 at midpoint |
Consensus is the FactSet mean as of Nov. 17 and Compound figures are from our Nov. 17 preview, both as published in it. FactSet showed no comp consensus when we published. Full-year EPS includes about $0.60 a share of tariff refunds booked in the second quarter, and the FactSet full-year mean mixes estimates with and without them.
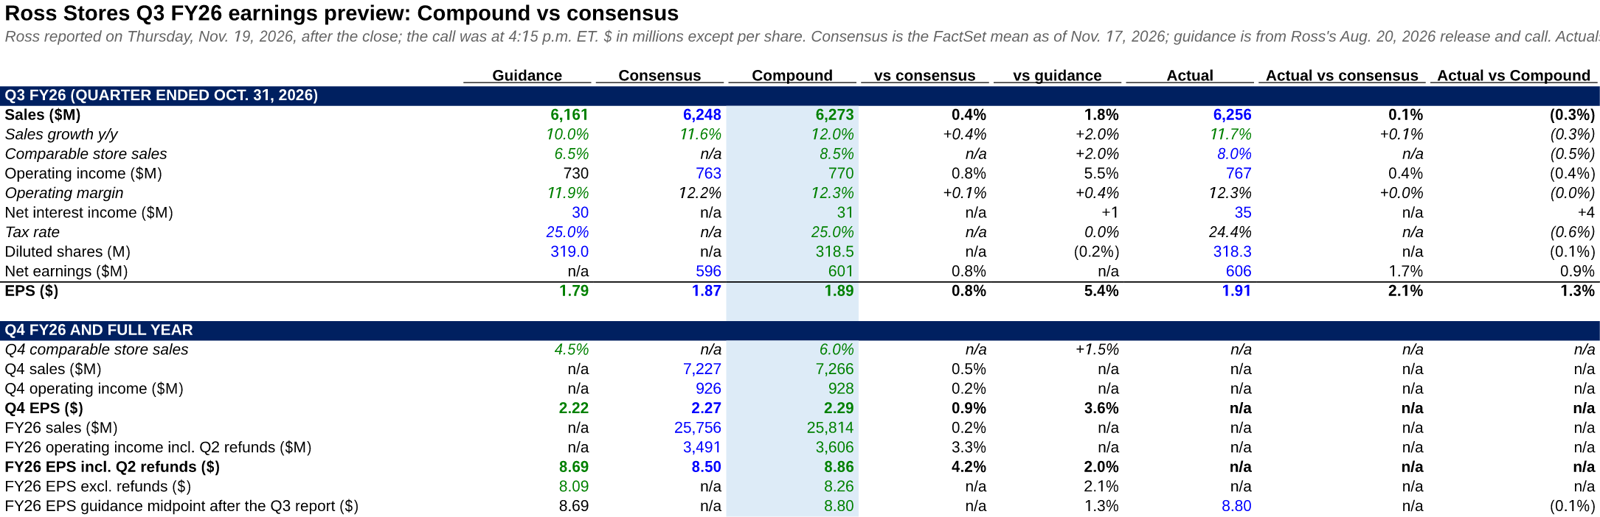
The Preview tab of our model, now with Ross's reported figures beside consensus and our estimates.
Guidance
For the fourth quarter, Ross kept its comparable sales outlook at 4% to 5%, against a 9% gain a year earlier, and set EPS at $2.16 to $2.25, a cent below the August range at both ends. FactSet consensus was $2.27, and our model had $2.29. On the call, Ross guided fourth-quarter sales growth of 7% to 9% and operating margin of 12.1% to 12.4%, against 12.8% consensus, StreetAccount reported. Our model had 12.8%.
For fiscal 2026, Ross now expects EPS of $8.75 to $8.84, including about $0.60 a share of IEEPA tariff refunds booked in the second quarter. We had expected about $8.76 to $8.85 on a small fourth-quarter raise; the new range is a cent lower at both ends because Ross trimmed the quarter instead.
| Outlook | New guidance | Before the report | Consensus | Compound |
|---|---|---|---|---|
| Q4 EPS | $2.16-$2.25 | $2.17-$2.26 | $2.27 | $2.29 |
| Q4 comparable sales | +4% to +5% | +4% to +5% | +5.1% | +6.0% |
| Q4 operating margin | 12.1%-12.4% | n/a | 12.8% | 12.8% |
| FY26 EPS, incl. Q2 refunds | $8.75-$8.84 | $8.61-$8.77 | $8.50 | $8.76-$8.85 expected range |
Q4 comp and operating margin consensus are FactSet figures as StreetAccount reported them after the release.
What drove the quarter
Results exceeded our expectations as our marketing initiatives continue to attract more customers while our compelling combination of great brands at exceptional values and an enhanced store experience continued to resonate. As a result, customer traffic remained the primary driver of our comparable store sales growth.
CEO Jim Conroy said that in the release. Comparable store sales rose 8% on top of a 7% gain a year earlier, and sales grew 12% to $6.26 billion. Ross opened 51 stores in the quarter, 41 Ross and 10 dd's DISCOUNTS, completing its plan of 115 for the year, and ended with 2,377 stores.
By our calculation from the release, gross margin, which in Ross's accounts includes buying, occupancy and distribution costs, was 28.7%, up from 28.0% a year earlier, and SG&A held at 16.4% of sales. Net interest income was $35 million and the tax rate 24.4%. Net income rose 18% to $606 million.
Inventory was $3.54 billion, up 13% from a year earlier. Ross bought back 1.4 million shares for $319 million and said it remains on track to repurchase $1.275 billion of stock this year. The board declared a quarterly dividend of $0.445 a share.
How our forecast did
We had the margin almost exactly. Operating margin came in at 12.3%, matching our 12.3% and above the guide; we had modeled 70 basis points of expansion and Ross reported 70. The split was different: gross margin rose 0.7 points against our 0.85, and SG&A was flat as a share of sales where we had expected 0.15 points of deleverage.
We were too high on the comp and on sales. Our 8.5% comp assumed a 15.5% two-year stack; Ross's 8% gives 15%, and sales finished $17 million below our $6.27 billion. EPS still came in two cents above our $1.89, and the gap was below the operating line: net interest income of $35 million against our $31 million, and a 24.4% tax rate against our 25%.
Our guidance call missed on the fourth quarter. We expected Ross to lift its fourth-quarter EPS range to $2.19 to $2.28; it trimmed the range by a cent, and the full-year range landed a cent below our expected $8.76 to $8.85. We had expected a smaller EPS beat than Ross's recent average, and it was: 2.1% over consensus, against 7.1% on average in the prior six quarters. The comp beat the top of guidance by 1 point, after beats of 3 to 9 points in each of the four quarters before.
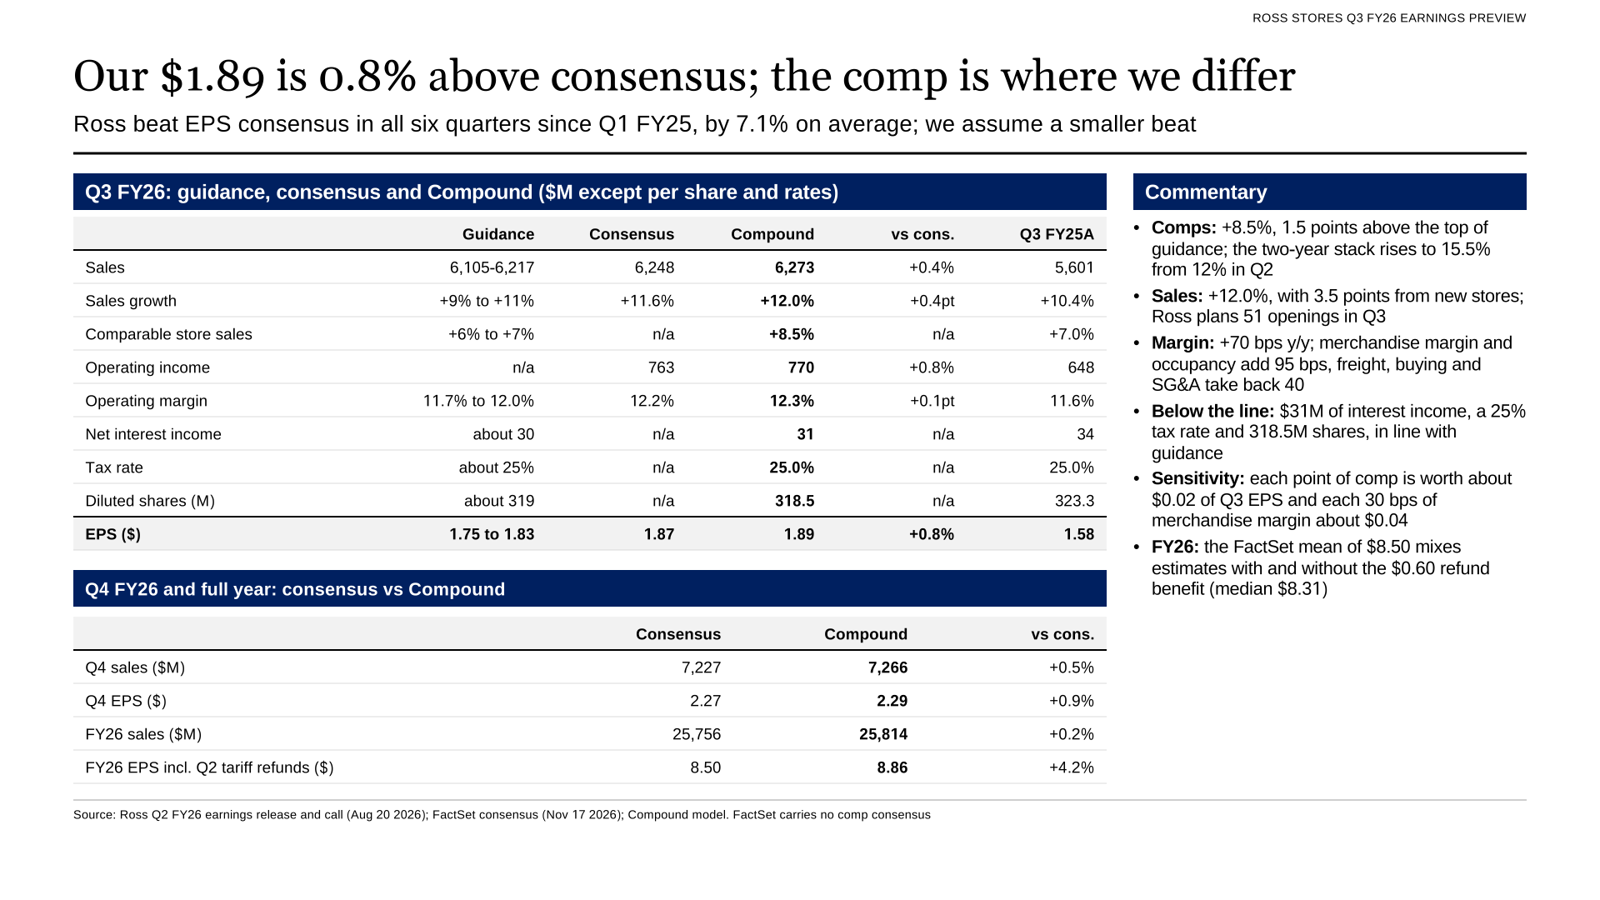
Slide 3 of our Nov. 17 preview deck: our forecast against consensus and guidance going into the report.
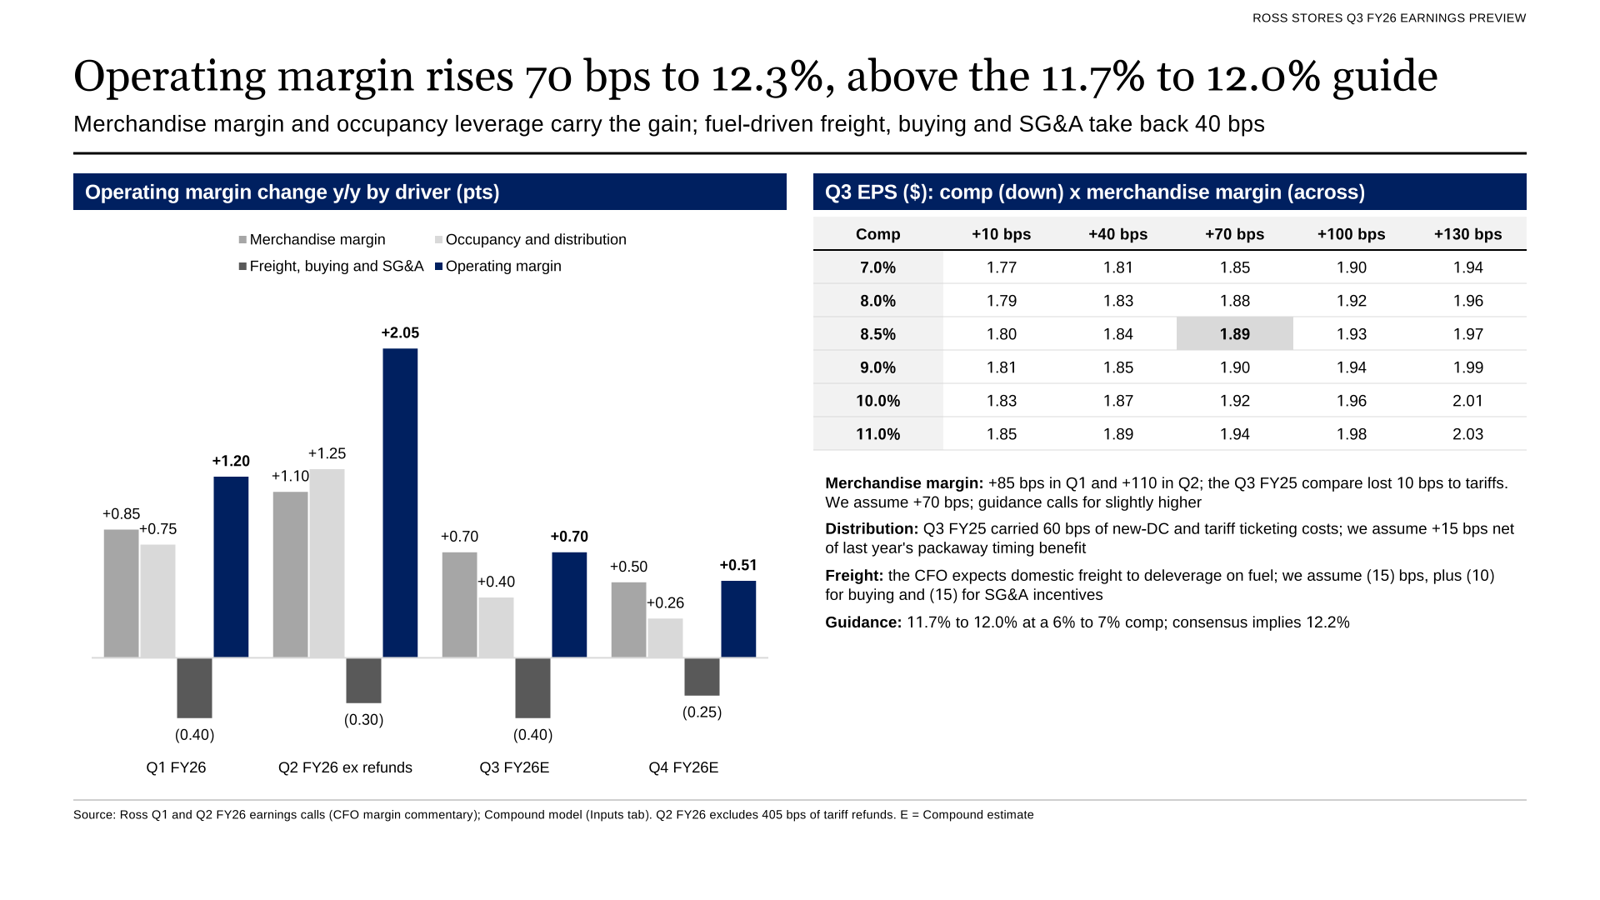
Slide 7: the 70 basis point margin gain we forecast, which Ross matched.
We score our previews against results; our NVIDIA third-quarter preview is another example.
Stock reaction
Ross shares fell 6.6% to $205.35 in after-hours trading on Thursday, from a $219.88 close, StreetAccount reported. StreetAccount's post-market summary said the comp missed consensus by 10 basis points and that fourth-quarter EPS guidance came in below consensus. The shares had closed at $222.99 on Nov. 16, up 39% from a year earlier, according to FactSet prices.
What to watch next
- The call transcript: the CFO's margin breakdown by component and any comment on November sales.
- Nov. 24, about 6:45 a.m. ET: Burlington Stores reports third-quarter results, according to FactSet's calendar.
- Holiday season: Ross's fourth-quarter guide calls for a 4% to 5% comp against a 9% gain last year and operating margin of 12.1% to 12.4%.
- Early March 2027: fourth-quarter results and the first fiscal 2027 outlook. FactSet projects Ross's report for March 9, 2027; FY27 EPS consensus was $9.04 on Nov. 17.
 Ross Stores Q3 FY26 earnings model with actuals (Excel)Our preview model with Ross's reported Q3 results added on the Preview tab: comps and store build, adjusted and GAAP income statements, operating margin bridge, quarterly cash flow and working capital, guidance and consensus track record, and data-table EPS sensitivities, with formulas and sources.Download · Free
 Ross Stores Q3 FY26 earnings preview deck (PowerPoint)The 11-slide preview deck published before the report: forecast vs consensus, track record, sales bridge, comps vs guidance, margins, guidance, cash flow, share price and what to watch.Download · Free
More from Compound News
Walmart Q3 Earnings: $0.65 EPS vs $0.64 Consensus
Walmart's adjusted EPS of $0.65 matched our forecast and beat the $0.64 consensus. Revenue of $188.8 billion topped both. The new full-year range of $2.84 to $2.89 came in a cent or two below what we expected.
Read article →
TJX Q3 Earnings: $1.34 EPS vs $1.34 Consensus
TJX matched the $1.34 consensus on adjusted EPS and beat on sales and comparable sales, but cut its fourth-quarter outlook on fuel costs. Our $1.36 forecast was $0.02 too high.
Read article →
Target Q3 Earnings: $2.65 EPS vs $2.08 Consensus
Target's third-quarter EPS of $2.65 included $0.50 of tariff refunds; excluding them, $2.15 beat the $2.08 consensus and our $2.10. Sales of $27.07 billion beat both, and Target raised its full-year outlook.
Read article →