Zoom Q3 Earnings Preview: $1.55 EPS vs $1.49 Consensus
Zoom reports Monday after the close. Our model puts revenue 0.5% above consensus and EPS at $1.55 against $1.49, but expects a Q4 guide below the Street. We estimate Contact Center at about 41% of Zoom's growth.
Zoom Communications reports fiscal third-quarter results on Monday, Nov. 23, after the market closes, with a webinar at 2 p.m. PT, according to the company's Oct. 29 announcement.
Compound's model forecasts Q3 revenue of $1,285.7 million, 0.6% above the $1,277.5 million midpoint of Zoom's guidance and 0.5% above the FactSet consensus of $1,279.0 million. We forecast non-GAAP EPS of $1.55 against a consensus of $1.49 and guidance of $1.46 to $1.48.
The stock closed at $91.52 on Nov. 17, down 9.3% from $100.92 on Aug. 25, the day of the second-quarter report. It fell 7.0% the next day.
We built an 11-page earnings preview deck on the model, in the format of our Nvidia preview. The slides below come from it, and the deck and the Excel model are free to download at the end.
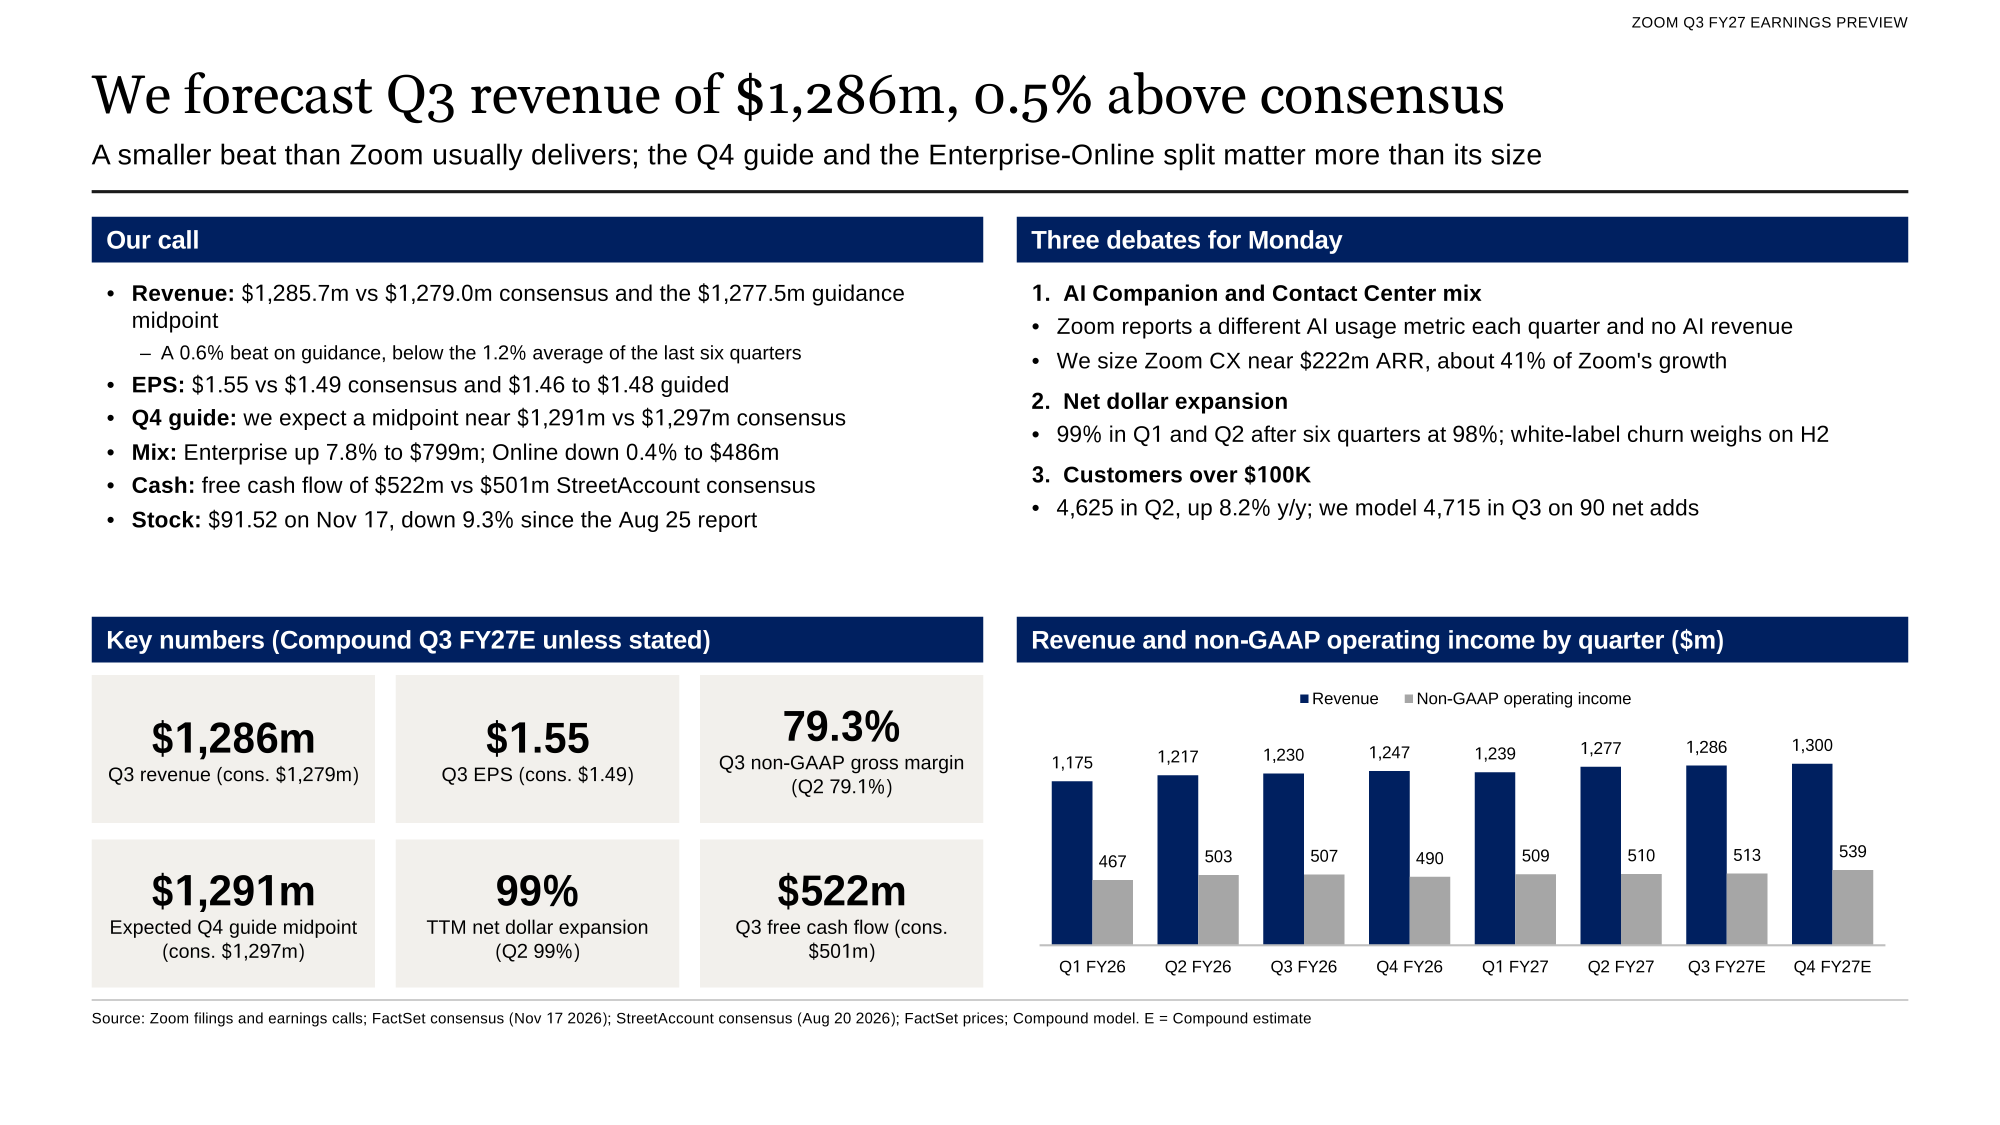
Executive summary: our call against consensus and the three debates for Monday.
Forecast vs consensus
| Q3 FY27 | Guidance | Consensus | Compound | Compound vs consensus |
|---|---|---|---|---|
| Revenue | $1,277.5M | $1,279.0M | $1,285.7M | +0.5% |
| Enterprise revenue | n/a | $784.4M | $799.2M | +1.9% |
| Online revenue | n/a | $496.1M | $486.4M | -1.9% |
| Non-GAAP gross margin | n/a | n/a | 79.3% | n/a |
| Non-GAAP operating income | $512.5M | $514.0M | $513.0M | -0.2% |
| Non-GAAP EPS | $1.47 | $1.49 | $1.55 | +4.5% |
Consensus is the FactSet mean as of Nov. 17. Enterprise and Online consensus is StreetAccount's Q3 figure from Aug. 20, set before Zoom reported Q2; StreetAccount had not published its Q3 preview by Nov. 17. Guidance figures are midpoints.
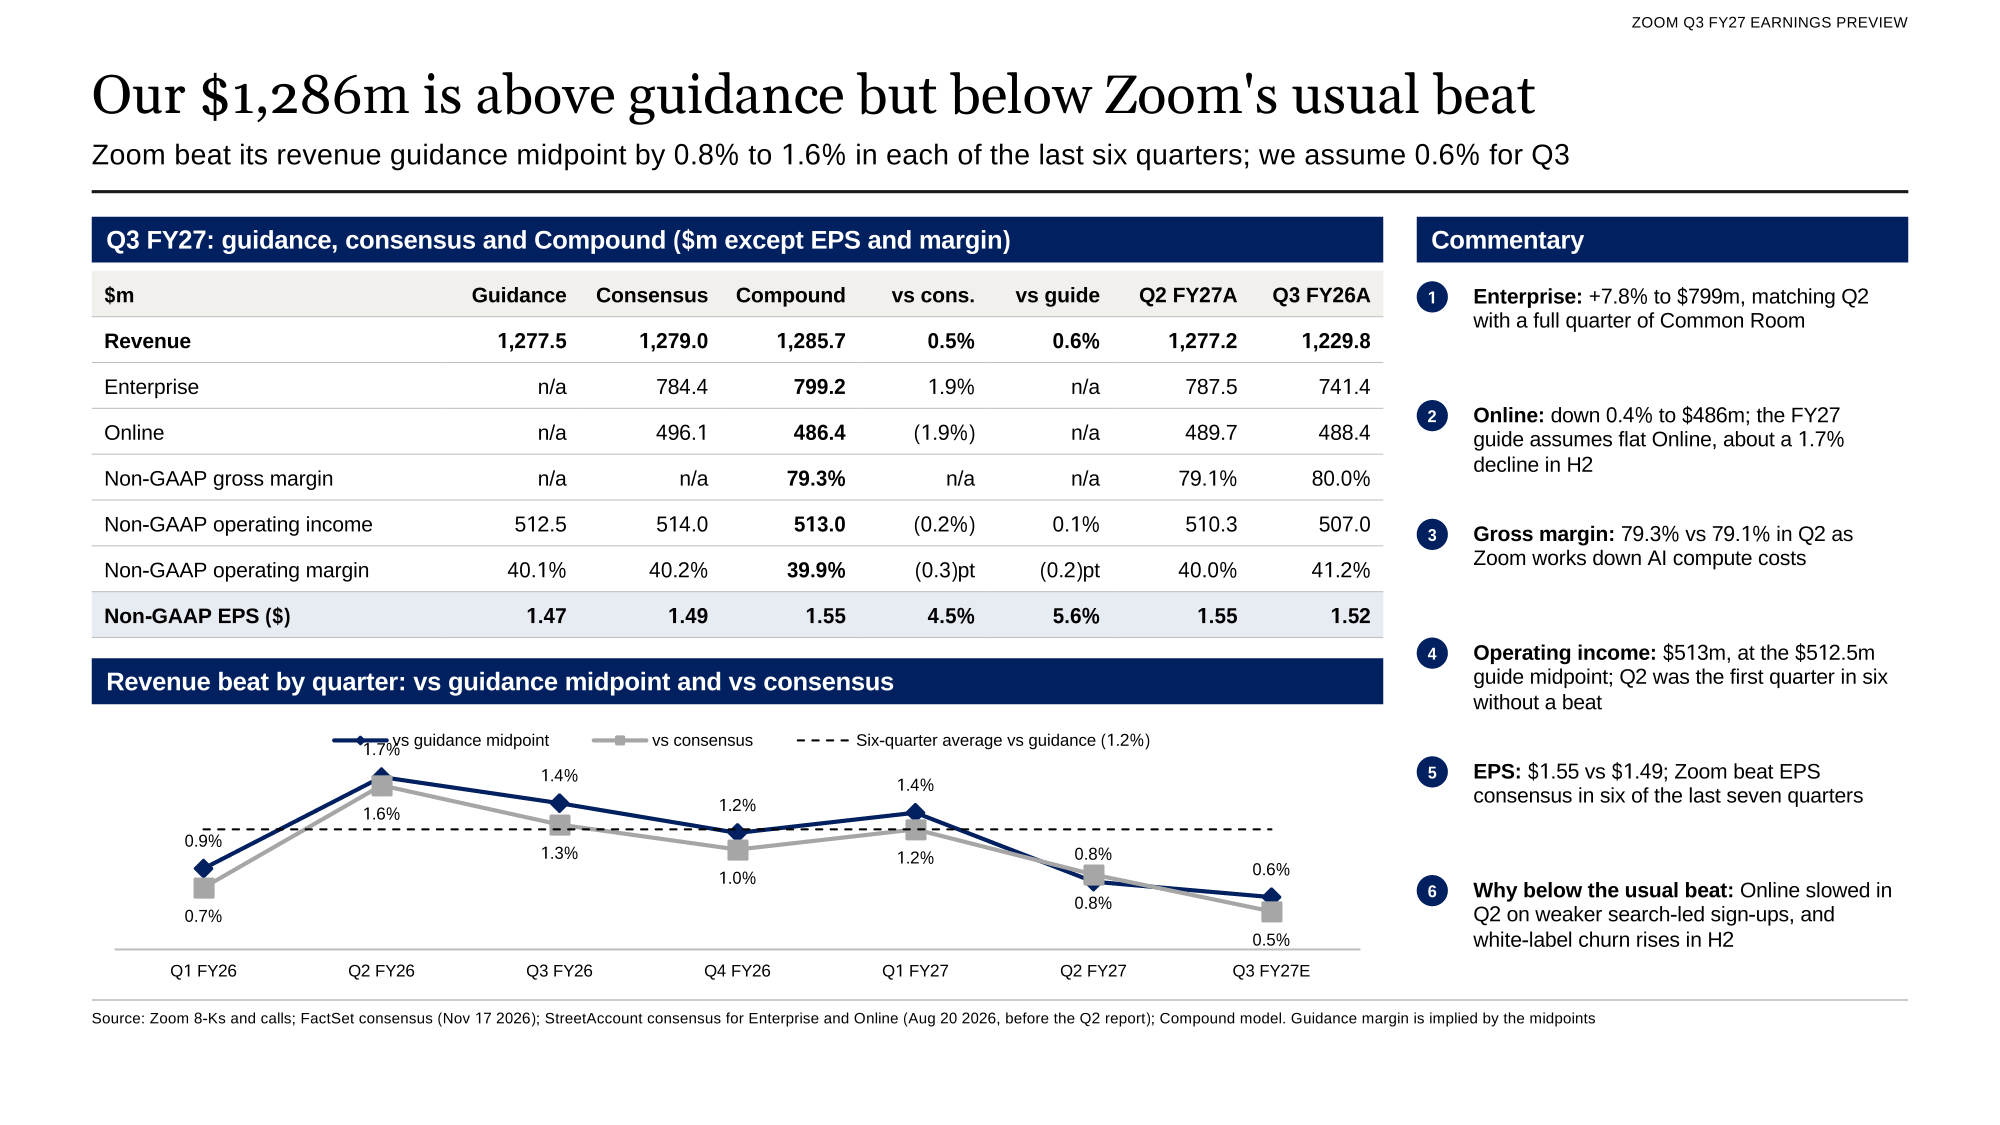
Zoom beat its revenue guidance midpoint by 0.8% to 1.6% in each of the last six quarters; we assume 0.6%.
How we built the forecast
The model grows each customer type from the same quarter a year earlier. Enterprise revenue rises 7.8% to $799.2 million, the same rate as in the second quarter, which Zoom called its fastest Enterprise growth in three years. Online revenue falls 0.4% to $486.4 million, after growth of 0.6% in Q2, according to Zoom's Q2 release.
Zoom beat the midpoint of its revenue guidance by 0.8% to 1.6% in each of the last six quarters, an average of 1.2%. Our 0.6% sits below that range for two reasons Zoom gave on its Aug. 25 call. CFO Michelle Chang said the full-year outlook assumes "flat online growth" after changes at "the top of funnel" as buyers move from search to AI. A flat year for Online implies a decline of about 1.7% in the second half. She also said churn from a white-label deal, which cut about 40 basis points from Q2 growth, "will come in a touch more in the second half."
We put non-GAAP gross margin at 79.3%, after 79.1% in Q2, when Zoom said AI usage spiked with new products. Operating income of $513.0 million sits at the $512.5 million guidance midpoint. Q2 was the first quarter in six in which Zoom did not beat its operating income midpoint. In our model, EPS beats guidance on a 19.5% tax rate, $63 million of other income and 298.8 million diluted shares; Zoom's guidance uses about 301 million and excludes buybacks.
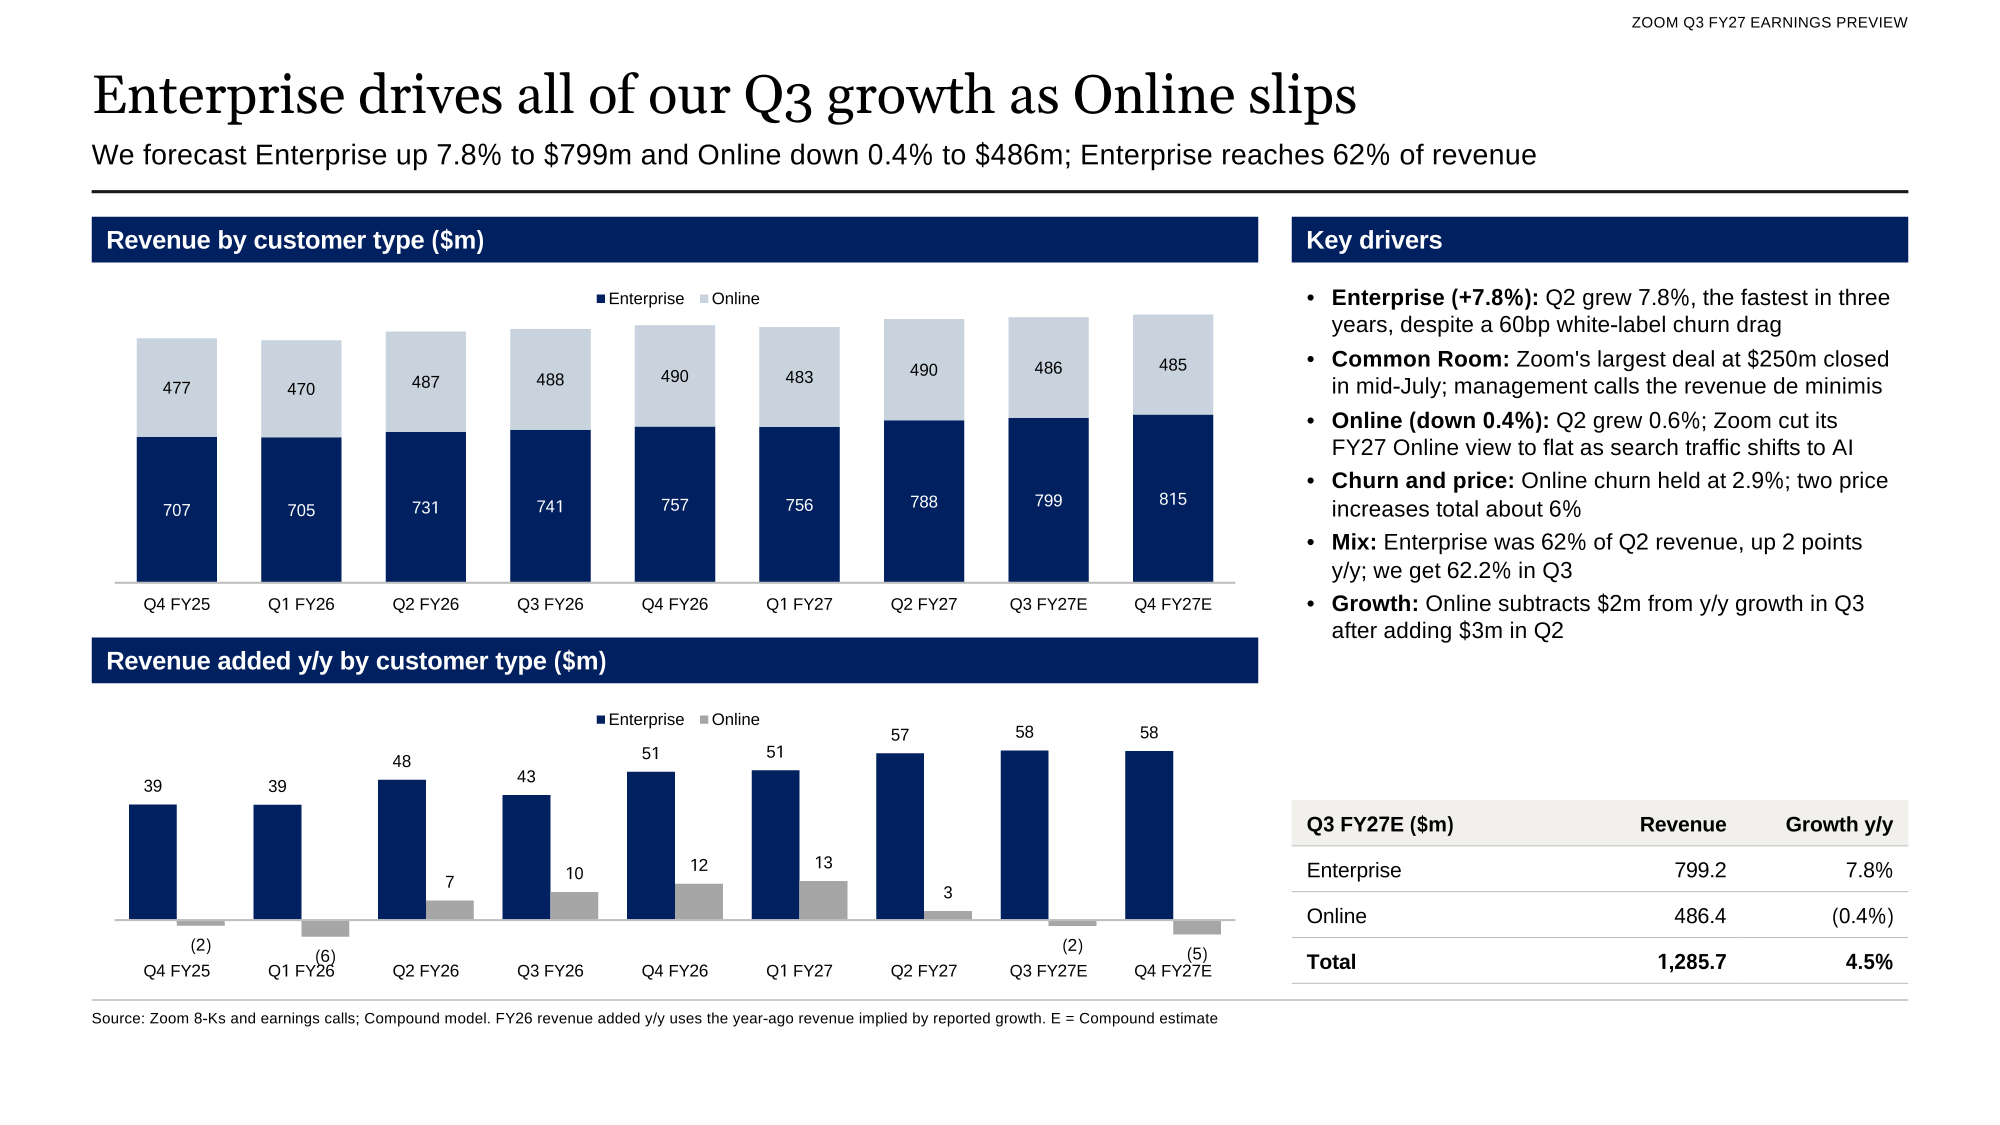
Enterprise supplies all of the year-over-year growth in our Q3 estimate.
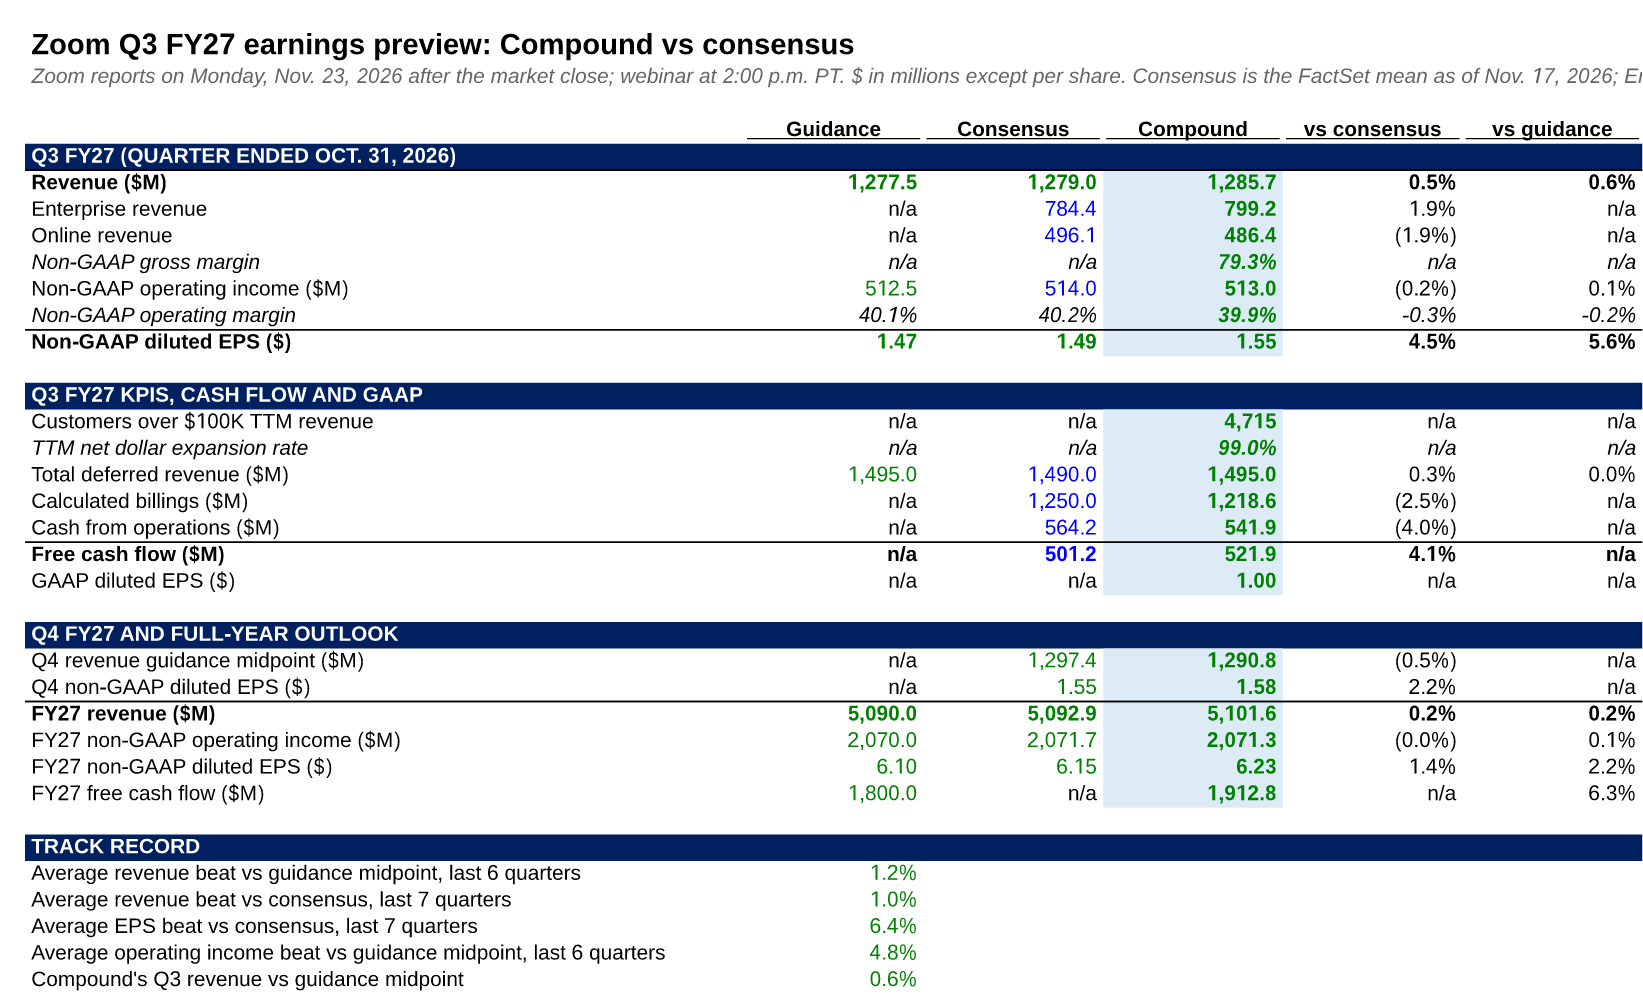
The Preview tab of the Excel model, which links every estimate to its drivers.
AI Companion and Contact Center
Zoom does not report revenue for AI Companion or for Zoom CX, its Contact Center and Virtual Agent business. Each call brings a different usage measure. AI Companion monthly active users grew more than four times in the year to Q2 FY26 and more than tripled in the year to Q4 FY26. Paid users rose 184% in Q1 FY27, and licensed monthly active users of AI features in Zoom Workplace rose 125% in Q2 FY27. AI Companion comes with paid licenses; Zoom charges extra for Custom AI Companion.
Contact Center gives more to work with. Zoom called CX "a triple-digit million ARR business, growing in high double digits" in Q1 FY26 and has described high double-digit growth since. On the Q2 FY27 call, an analyst placed the $100 million milestone five quarters earlier, and Chang said "you can sort of guesstimate from there." Our base case grows $100 million at 70% a year to about $222 million of ARR at the end of Q3, 4.3% of Zoom's revenue run rate. That would make CX about 41% of the run-rate revenue Zoom added over the year. At 50% and 90% growth, the share is 27% and 56%.
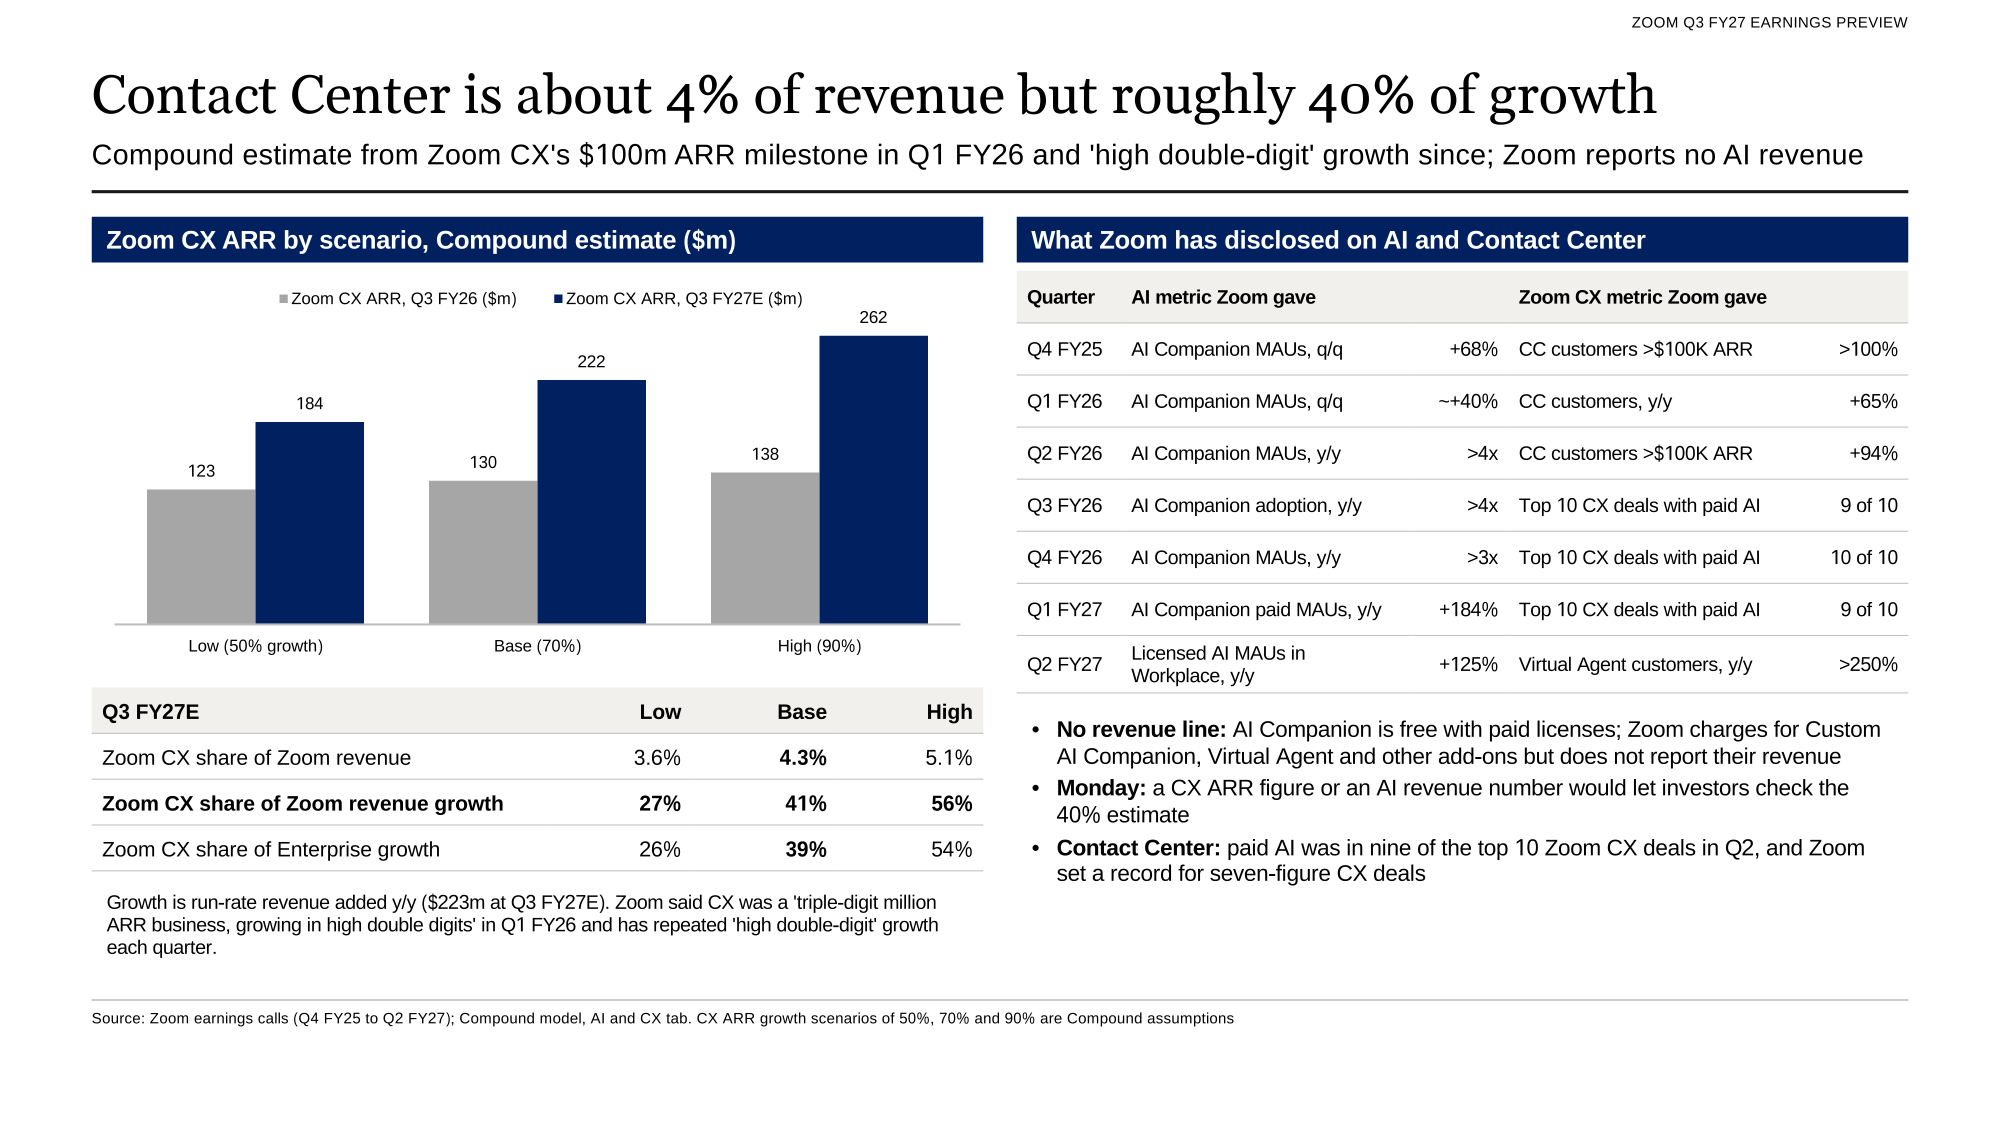
Zoom CX ARR is a Compound estimate; the scenario growth rates are assumptions.
Net dollar expansion and customers over $100,000
Zoom's trailing 12-month net dollar expansion rate for Enterprise customers was 98% for six straight quarters and 99% in Q1 and Q2 FY27. Enterprise revenue grew 7.8% in Q2, about 9 points faster than existing customers expanded, so new customers, new products and acquisitions carried the growth. We hold the rate at 99%.
Customers contributing more than $100,000 of trailing 12-month revenue reached 4,625 in Q2, up 8.2%, and made up 33% of revenue. Net additions ranged from 66 to 105 a quarter over the last six quarters. We model 90, for 4,715.
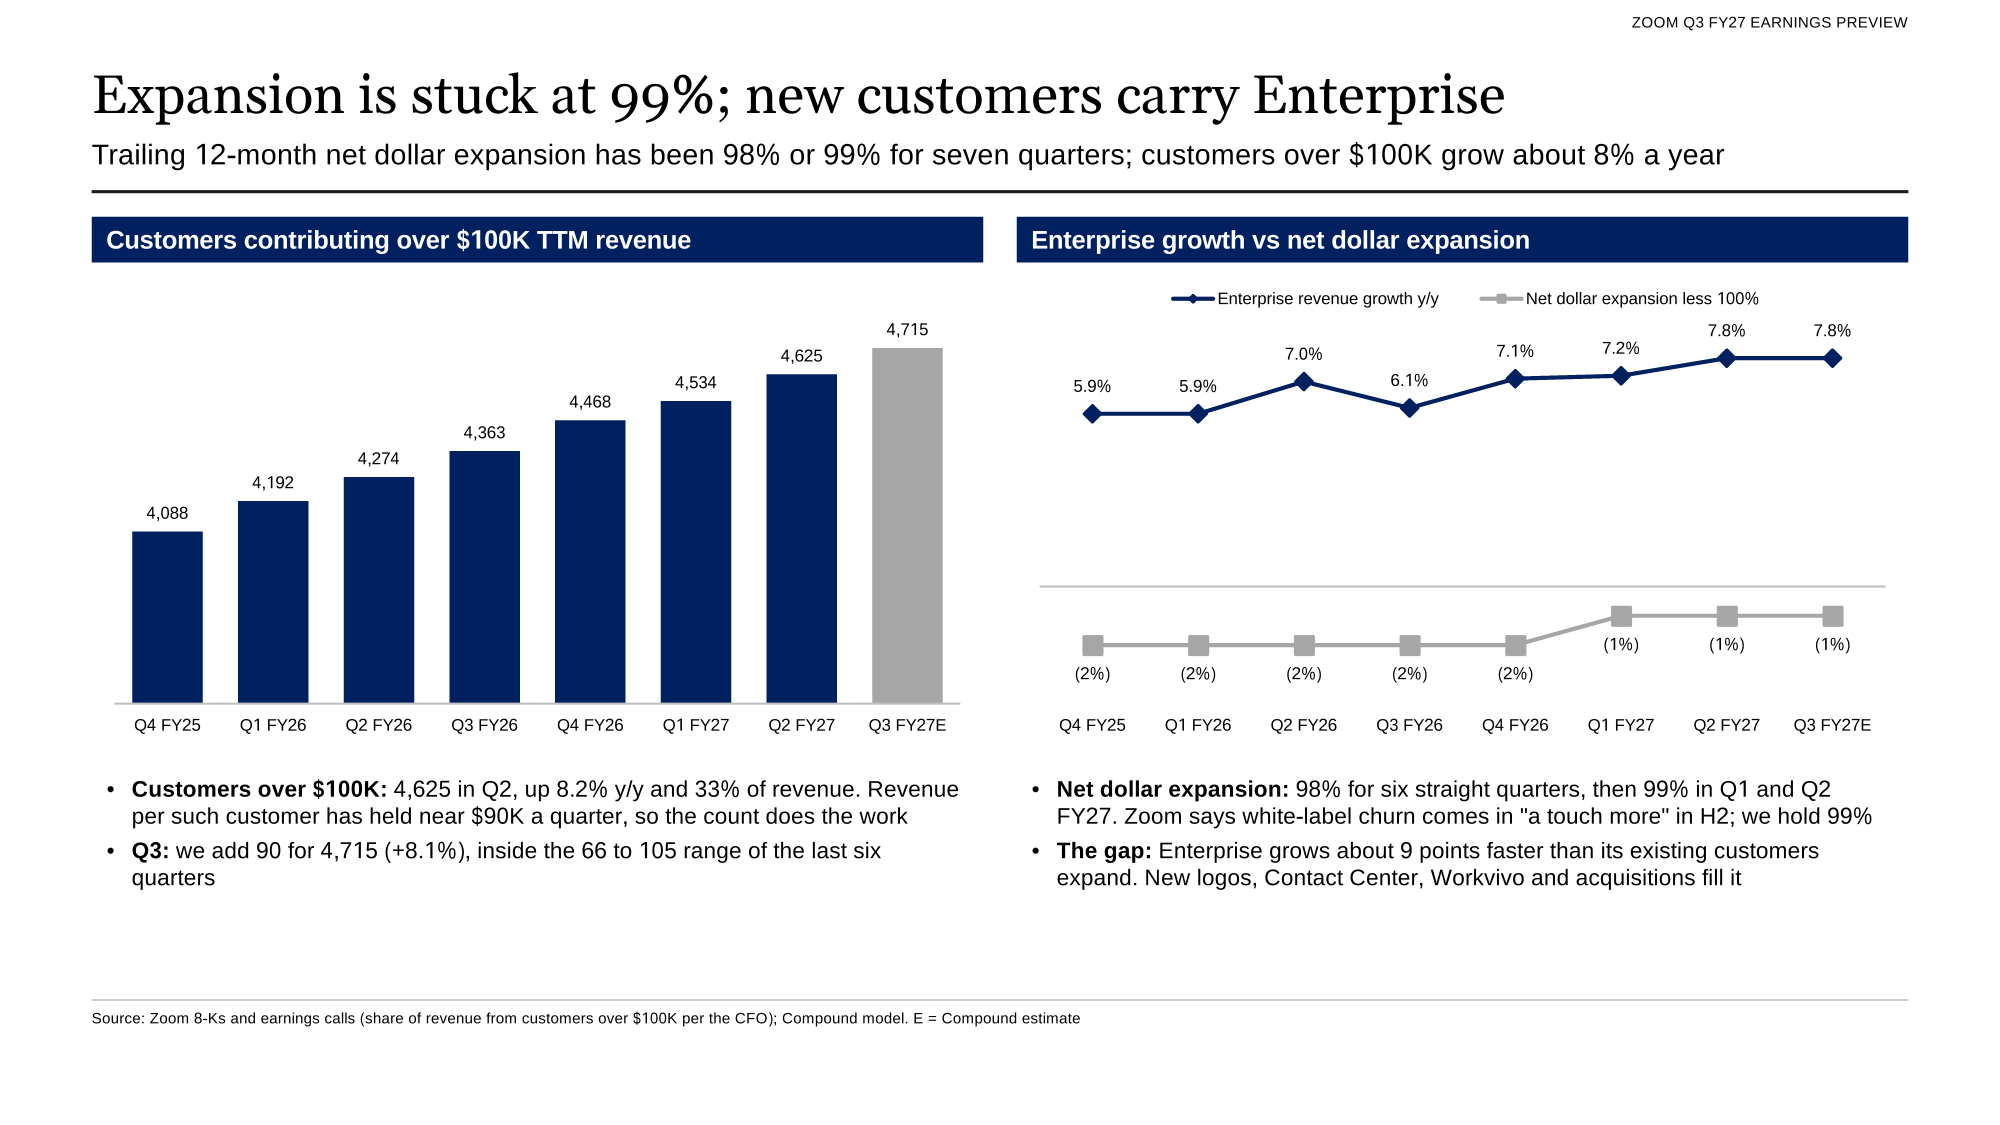
Enterprise growth runs about 9 points ahead of net dollar expansion.
Q4 guidance
FactSet consensus for fourth-quarter revenue is $1,297.4 million, with estimates from $1,289.8 million to $1,317.5 million. Last year Zoom guided Q4 0.2% above its Q3 revenue. We expect a guide 0.4% above our Q3 estimate, a midpoint of about $1,290.8 million, 0.5% below consensus. A repeat of last year's step would put the midpoint at $1,288.5 million, below every FactSet estimate.
Zoom's full-year guidance calls for revenue of $5.085 billion to $5.095 billion, non-GAAP EPS of $6.08 to $6.12 and free cash flow of $1.78 billion to $1.82 billion. Our model has $5,101.6 million, $6.23 and $1,912.8 million.
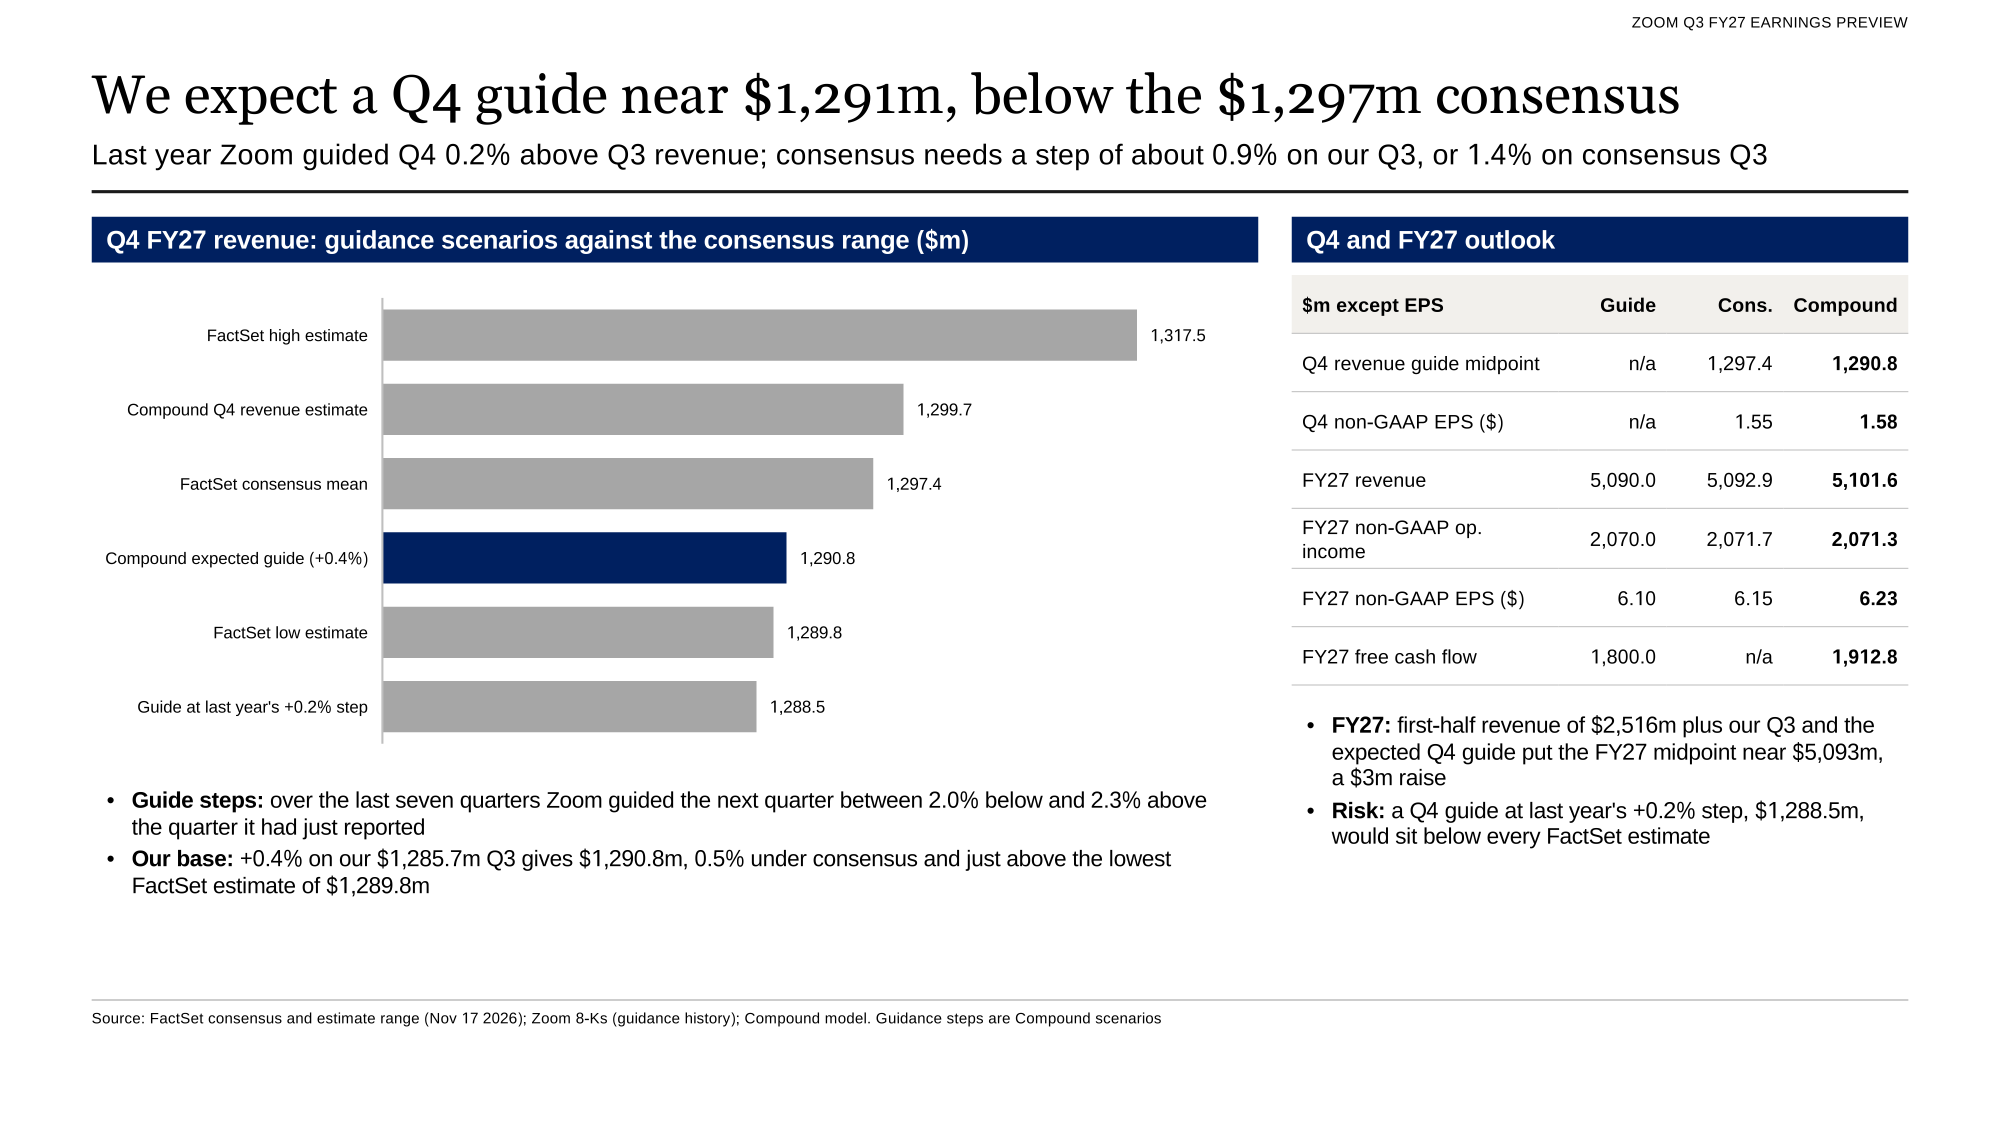
Guidance scenarios against the consensus range for Q4 revenue.
Cash flow and contracted revenue
Remaining performance obligations rose 14% to $4,535.9 million at July 31, with non-current RPO up 25%, according to Zoom's Q2 10-Q and call. Zoom guided Q3 deferred revenue up 3% to 4%. We forecast Q3 free cash flow of $521.9 million, against $501.2 million in StreetAccount's Aug. 20 consensus and $614.3 million a year earlier, when receivables fell to 31 days of sales.
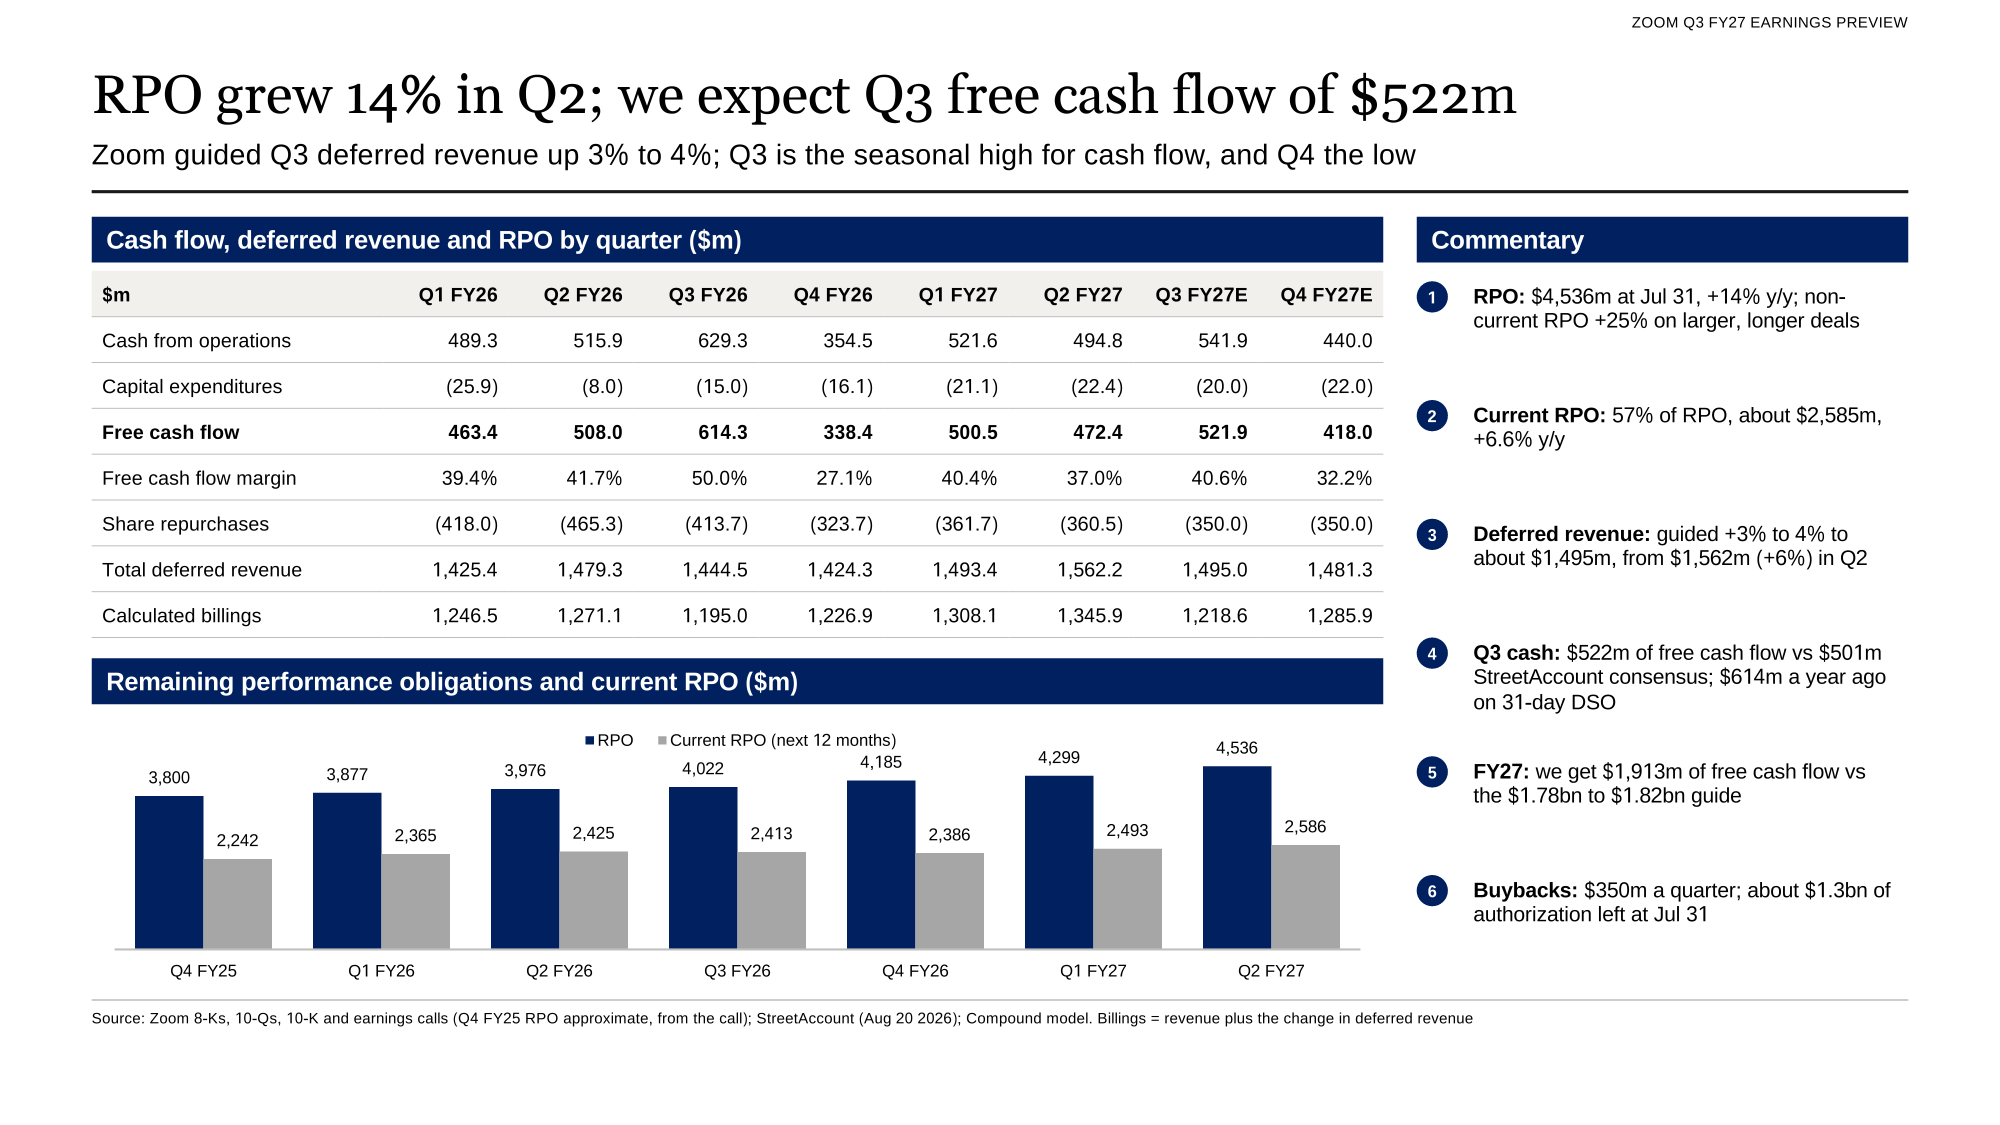
Q3 is Zoom's seasonal high for cash flow.
Anthropic stake
Zoom carried its preferred stock in Anthropic at $3,134.5 million at July 31, after an unrealized gain of $1,612.7 million in Q2, its 10-Q shows. StreetAccount reported that Anthropic plans to sell 825 million shares at $70 to $78 each and to begin trading Nov. 19 or 20. Q3 closed Oct. 31, so a listing would most likely show up in Zoom's Q4 GAAP results. Zoom excludes these gains from non-GAAP EPS.
On Nov. 12, Anthropic said Claude can join video calls as a visible participant, in a beta called Claude Meetings. Zoom shares ticked down on the news, StreetAccount reported.
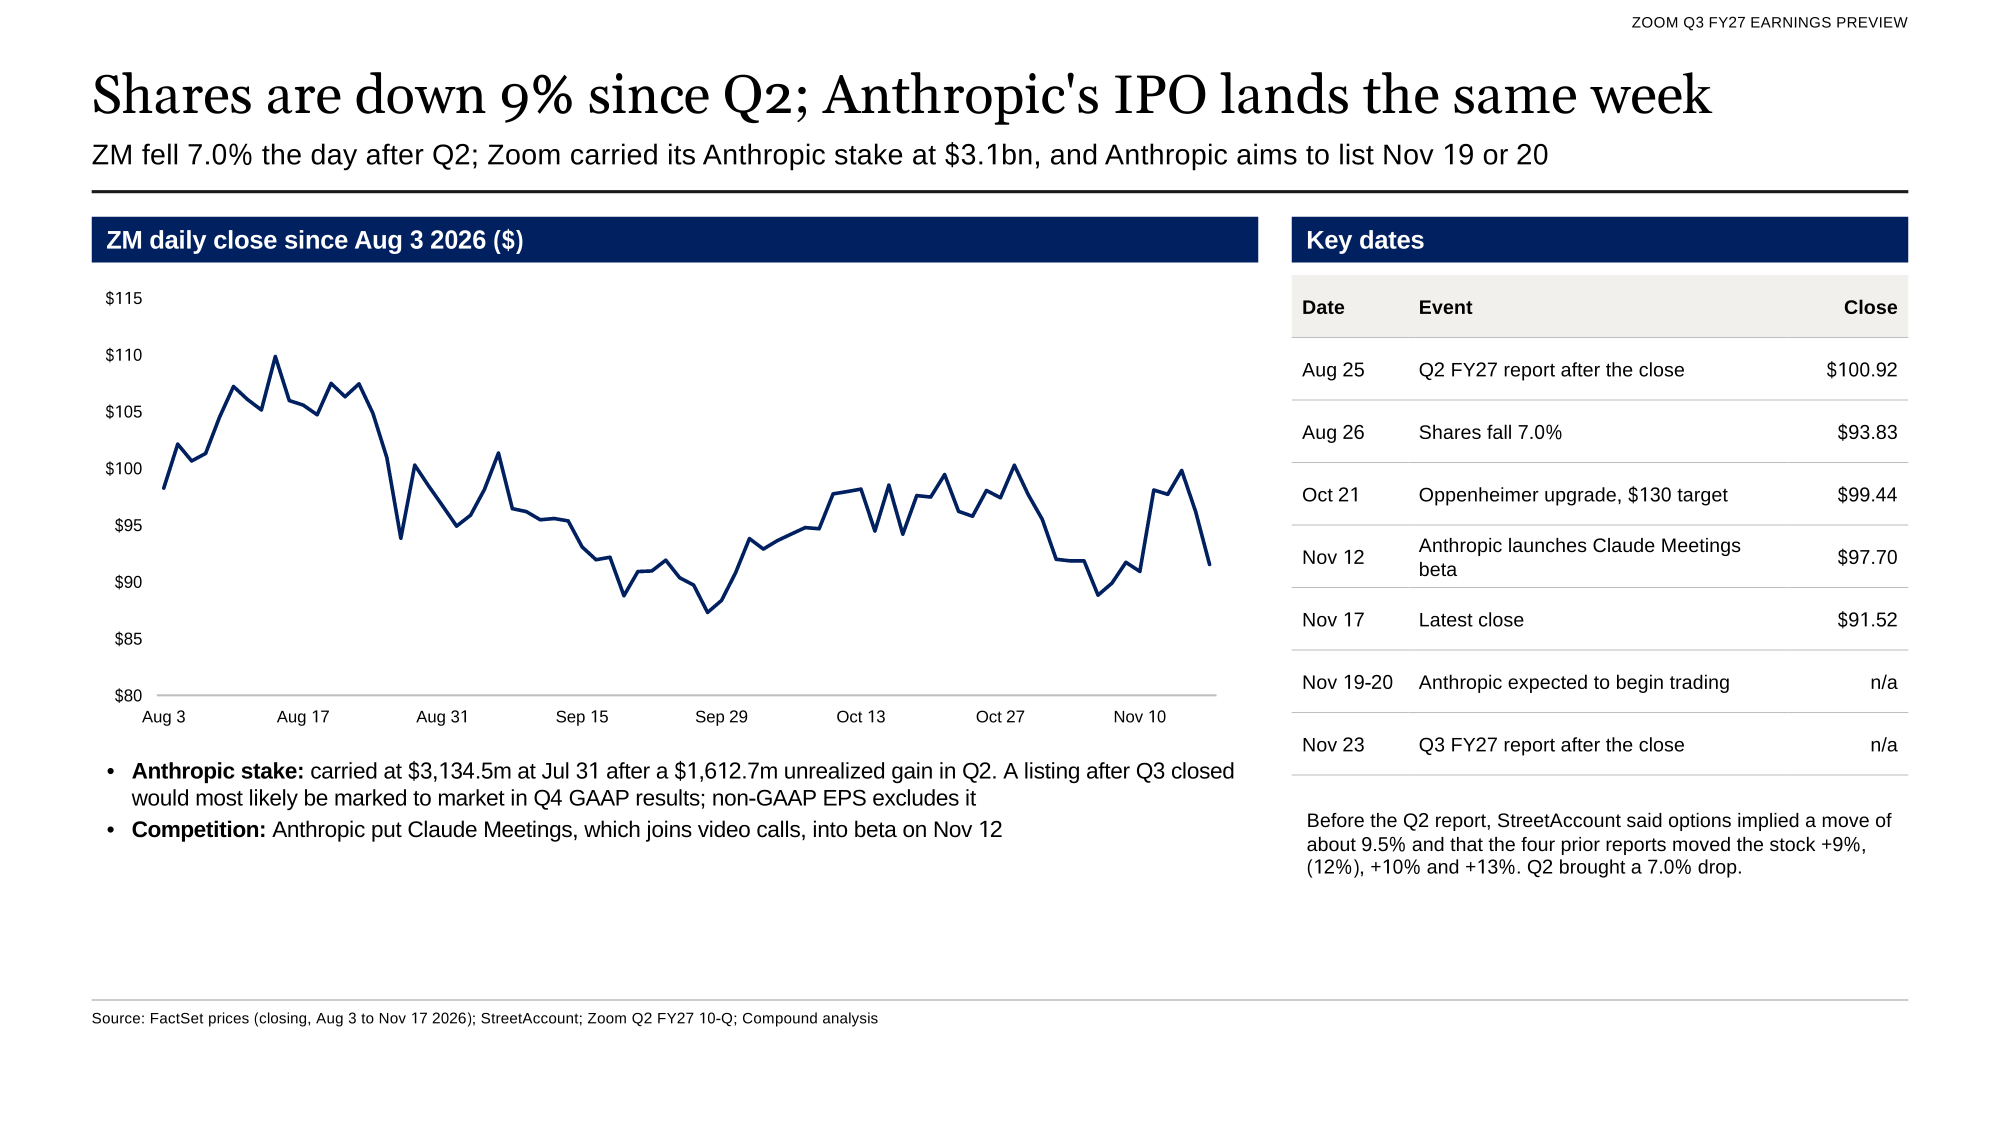
ZM since August, with the dates that moved it.
What to watch on Monday
- Q4 revenue guidance against the $1,297.4 million consensus and our $1,290.8 million.
- Online revenue against our 0.4% decline and Zoom's flat full-year assumption.
- Net dollar expansion at 99% or higher.
- Net additions of customers over $100,000 against our 90.
- Any revenue or ARR figure for Zoom CX or AI products.
- Gross margin against 79.1% in Q2.
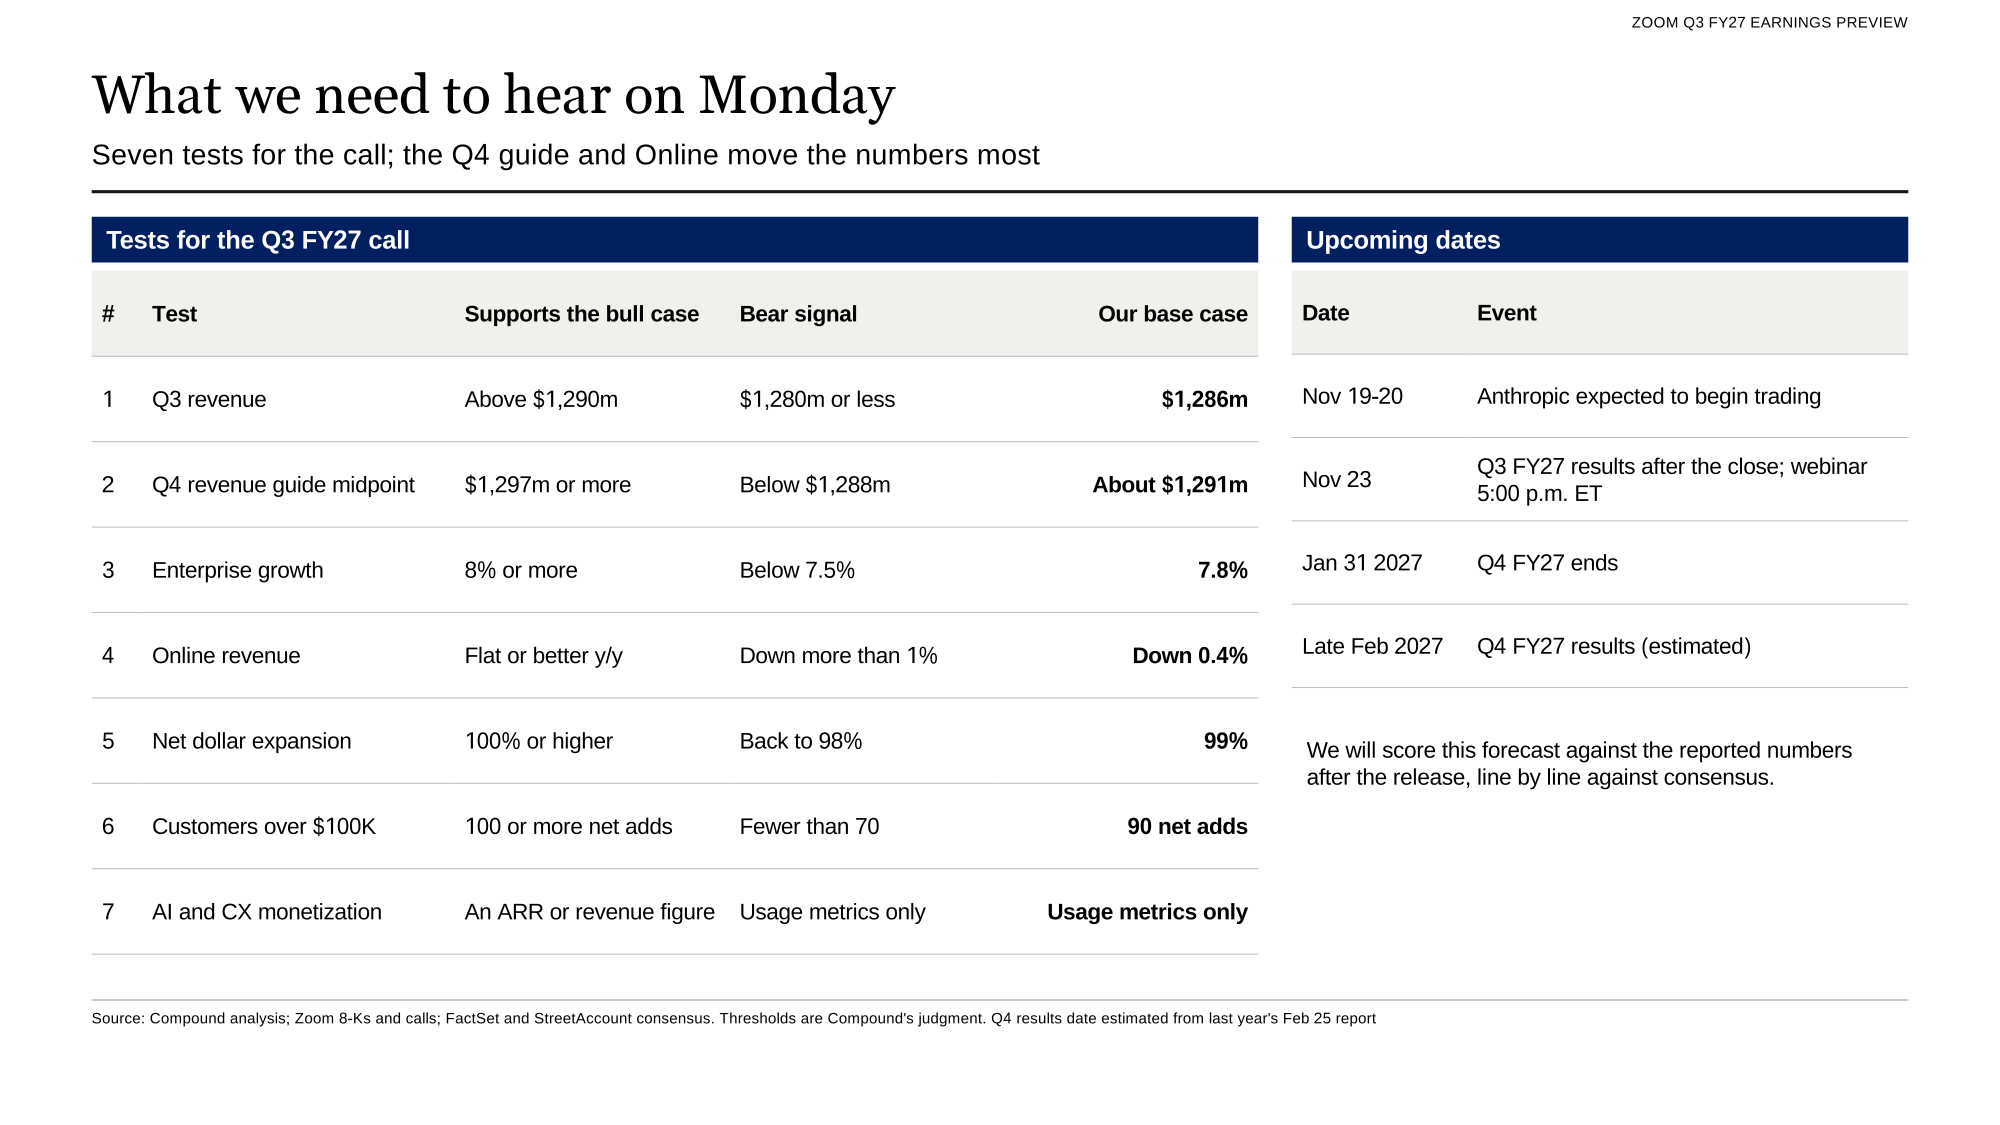
Seven tests for the call, with what would support the bull and bear cases.
We will score this forecast against the reported numbers after the release.
 Zoom Q3 FY27 earnings preview deck (PowerPoint)The 11-page preview: executive summary, forecast against consensus, revenue by customer type, net dollar expansion and $100K customers, AI Companion and Contact Center, margins, Q4 guidance scenarios, cash flow and RPO, the share price and the Anthropic stake, and the checklist for the call.Download · Free
 Zoom Q3 FY27 earnings model (Excel)Quarterly model from Q4 FY25: Enterprise and Online revenue, customer metrics and RPO, non-GAAP and GAAP income statements, cash flow, balance sheet and working capital, guidance and consensus track record, Compound's Q3 and Q4 estimates, native data-table sensitivities and the AI and Contact Center analysis, with formulas and sources.Download · Free
 Zoom Q3 FY27 earnings preview deck (PDF)The same 11 pages as a PDF.Download · Free
More from Compound News
Snowflake Q3 Earnings Preview: $0.69 EPS vs $0.60 Consensus
Snowflake reports Wednesday after the close. Our model puts product revenue 3.5% above the guidance midpoint and EPS at $0.69 against a $0.60 consensus. Remaining performance obligations have fallen for two quarters.
Read article →
Salesforce Q3 Earnings Preview: $3.51 EPS vs $3.45 Consensus
Salesforce reports Wednesday, Dec. 2, after the close. Our model puts third-quarter revenue at $11.50 billion, 0.3% above consensus, and non-GAAP EPS at $3.51 against $3.45. We expect the fourth-quarter revenue guide to land about 1.3% below the Street.
Read article →
Marvell Q3 Earnings Preview: $1.11 EPS vs $1.10 Consensus
Marvell reports Tuesday, Dec. 1, after pre-announcing Q3 revenue at its $3.15 billion guidance midpoint. Our model puts EPS at $1.11 against $1.10 and the Q4 revenue guide at about $3.75 billion. The stock is down 40.9% since Oct. 28.
Read article →